

This article first appeared in The Edge Malaysia Weekly on September 14, 2026 - September 20, 2026
ELECTRICAL engineering services firm HE Group Bhd (KL:HEGROUP) expects to set a new record high order book of RM400 million by the end of the current financial year ending Dec 31, 2026 (FY2026) as a beneficiary of the data centre (DC) boom.
Already, its outstanding order book stands at an all-time high of RM300 million, with nearly half consisting of DC-related jobs.
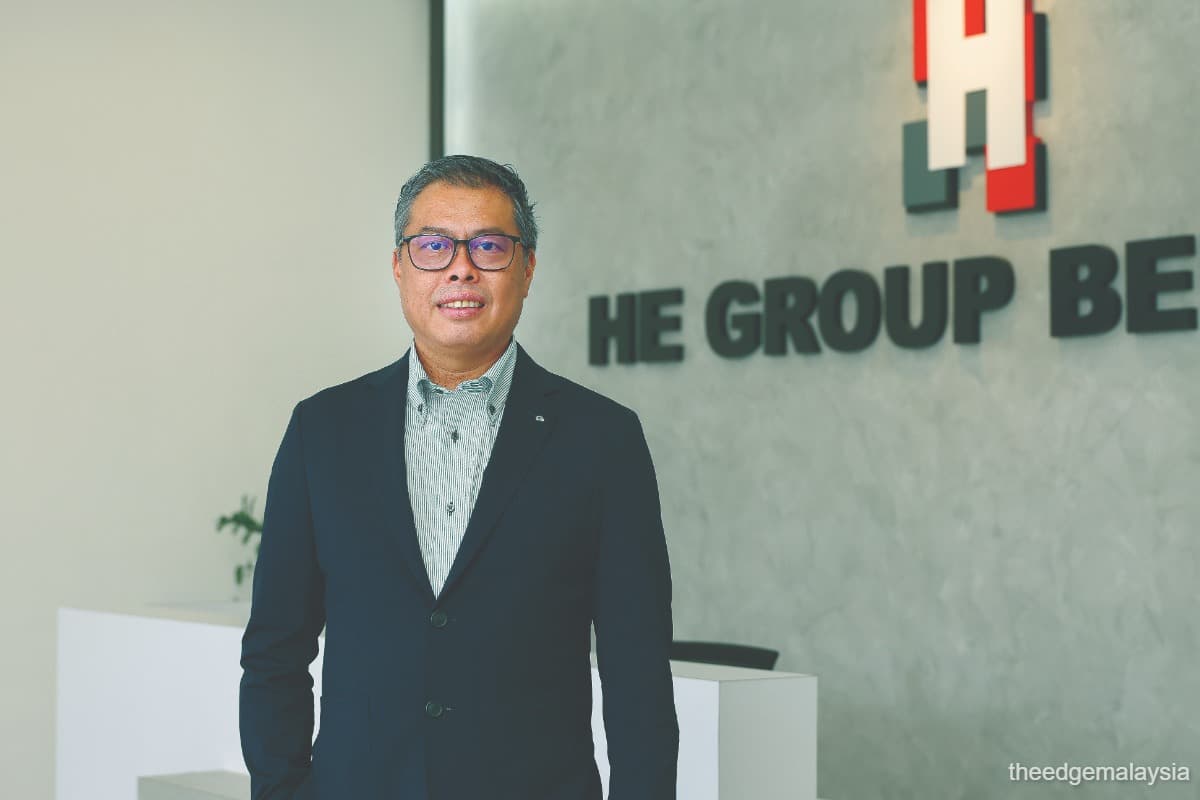
“At least in the next five years, it will still be mostly driven by DCs. Of course, as a company policy, we won’t put everything in one basket. So, we are still diversified into infrastructure and semiconductors. We are aiming for these three sectors,” says managing director Amos Haw Chee Seng, 48, in an interview with The Edge.
Haw is the largest shareholder with a 23.42% stake, followed by executive director Eng Choon Leong who holds 15.36%.
Beyond its core engineering business, HE Group is looking for more opportunities in renewable energy to build a recurring income stream.
“We are already involved in some solar farms. If there is an opportunity, we hope that we can become an asset owner. Although it is very capital-intensive, with our status as a listed company, we believe it is quite easy for us to raise funds as long as the business and financing models are viable. This is part of the company’s sustainability efforts,” Haw says.
The share price of HE Group, which transferred its listing status to the Main Market from the ACE Market in November 2025, has more than tripled from its debut price of 28 sen in January 2024.
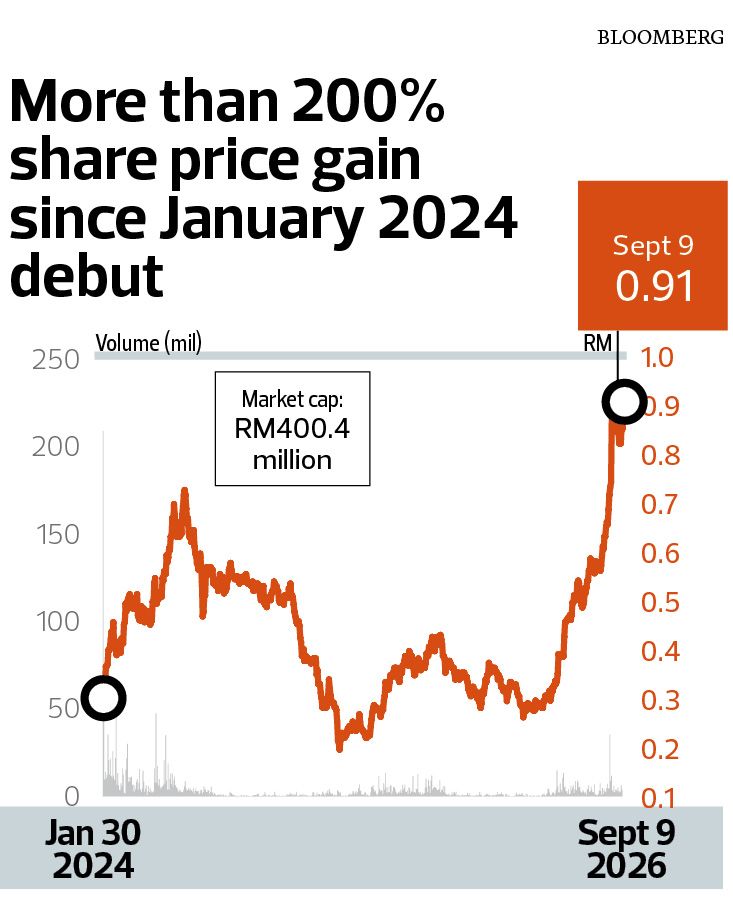
At last Wednesday’s closing price of 91 sen, the group was valued at RM400.4 million. The stock is trading at trailing and forward 12-month price-earnings ratios of 31 times and 21.2 times respectively.
HE Group is involved in four business segments, namely power distribution system; electrical equipment hook-up and retrofitting; other building systems and works; and trading of electrical products. Within the power distribution system value chain, it primarily services the end-user premises by converting high-voltage power from the substations into lower and safer voltages.
Apart from DCs, its end-user industries include semiconductors, medical devices and electronic products as well as servicing a wide range of critical applications such as industrial plants, industrial and commercial substations.
Haw says Malaysia’s 7gw DC pipeline offers tremendous opportunities for market players within the next five years. In view of the robust DC development, he shares that the group is also keen to undertake fibre maintenance projects for DCs.
“When there is a change in tenants for any DC, the fibre has to be changed. The most important thing is that we have to keep looking for recurring income to stabilise the company,” he says.
Among the sizeable contracts secured by HE Group in recent months are a RM102 million subcontract for a DC in Johor and an RM86 million award for the construction of a substation in Selangor.
Rising margins, broader capabilities
Notably, the group’s net margin has been on an upward trend, expanding to 8.9% in FY2025 from 6.6% in FY2024 and 5.4% in FY2023, reflecting its cost management and efficient project execution amid transitional project cycles.
This came despite a lower net profit of RM11 million in FY2025 against RM13.7 million in FY2024, mainly due to the completion of several major projects.
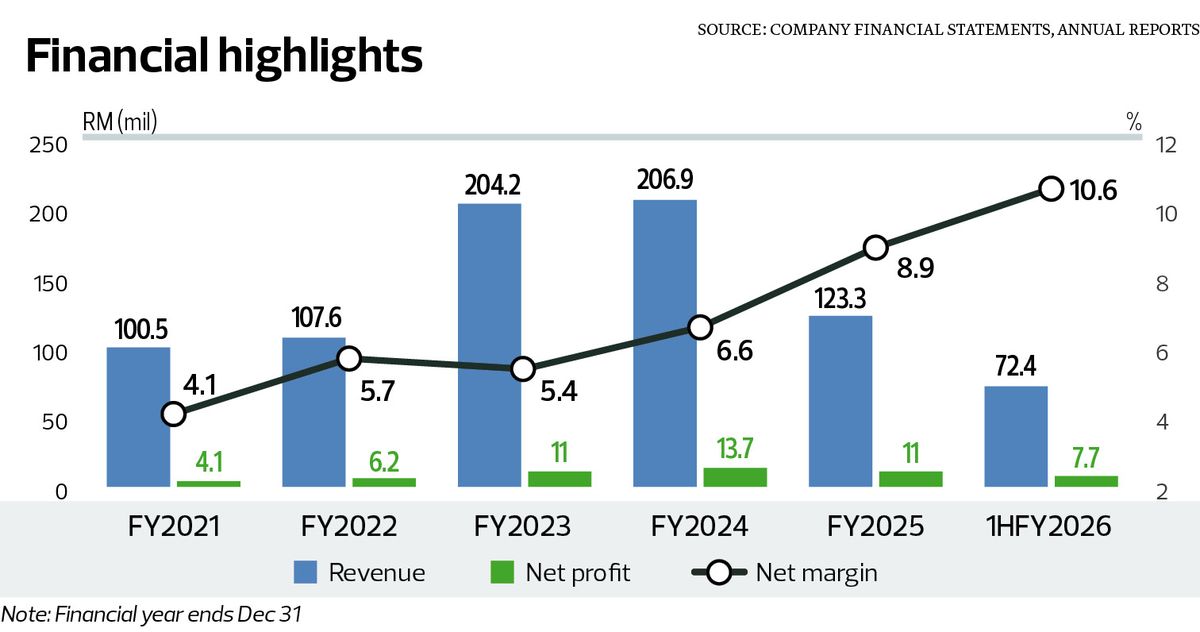
In 1HFY2026, it posted a net profit of RM7.67 million, up 26.7% from RM6.05 million in the same period a year ago, lifting its net margin to 10.6%.
Haw believes the group can sustain its margins by continuing to provide added value to its clients.
At the same time, HE Group is looking to become an integrated mechanical, electrical and process utility (MEP) engineering service provider. Currently, the provision of mechanical and process utility systems is subcontracted to third parties.
“It is not because of better margins or more jobs, but we can take on a bigger scope of jobs. One of our targets is to become an EPCC (engineering, procurement, construction and commissioning) or EPCM (engineering, procurement and construction management) player. We need the mechanical and process utility people to equip us to become an EPCC or EPCM,” Haw notes.
To achieve this, the group plans to embark on mergers and acquisitions to acquire suitable firms and broaden its capabilities.
“We have been very carefully looking through a few companies with thorough due diligence, but no conclusion yet, mainly because of the price and they were not able to meet our conditions by providing a profit guarantee. So, these two factors are the blocking points,” Haw explains.
Capacity concerns
Meanwhile, PublicInvest Research, in an Aug 12 note, highlighted concerns that HE Group’s order book was approaching its maximum capacity of RM400 million.
However, Haw does not think the group is operating at its maximum capacity.
“Post-IPO (initial public offering), our historical order book peak was RM260 million to RM280 million, which is not too far compared to our current order book of around RM300 million.”
He adds that the group is actively expanding its team to cope with rising business volumes.
Beyond Malaysia, HE Group is considering expanding into Indonesia and Thailand, which are emerging as DC hotpots.
But there are challenges, particularly rising raw material costs. About 70% of its raw materials comprise copper, whose price on the London Metal Exchange recently hit an all-time high of US$14,779 per tonne.
“El Niño has caused copper prices to suddenly spike over the last few weeks. I have never seen such a high price in my career. We need to be very sensitive as we cannot simply raise prices after we get the fixed-price contracts. So far, things have been good.
“We also need to work very closely with our suppliers. They are willing to hold the materials at old prices with a certain percentage of downpayment,” Haw explains.
Meanwhile, he acknowledges that finding suitable talent has become increasingly challenging. HE Group currently employs more than 120 local staff, mainly engineers, site supervisors and project managers, and may consider hiring foreign talent if local shortages persist.
Overall, analysts are positive on HE Group’s outlook, with a consensus target price of RM1.06 based on two “hold” calls and a “buy”.
PublicInvest raised its FY2026-FY2028 earnings forecasts by an average of 11%, reflecting larger-than-expected tender book conversion, based on a FY2026 replenishment target of RM280 million.
The research house says the focus has shifted from order book replenishment to execution, making execution discipline and prudent resource management increasingly critical.
Maybank Research recently downgraded the group to “hold” from “buy” on valuation considerations, following its strong share price rally of more than 150% this year.
Nonetheless, the research house expects its earnings to be supported by its order book, equivalent to 2.4 times FY2025 revenue.
“Year-to-date new job wins stood at RM268 million and we expect the job win momentum to continue in 2H2026, backed by its RM1 billion tender book, of which a significant portion comprises DC projects. For FY2026, we are maintaining our full-year job replenishment expectation of RM350 million,” the research house said in an Aug 18 note.
The group remained in a net cash position of RM46.24 million as at end-June 2026, which Haw says will put it in a stronger position to take on larger jobs going forward.
HE Group is among a number of companies affected by the resignation of its auditors, TGS TW PLT, which cited internal review of its portfolio and resource management considerations. HE Group says an announcement on the appointment of new auditors will be made in due course.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.