

This article first appeared in Capital, The Edge Malaysia Weekly on September 14, 2026 - September 20, 2026
Healthcare
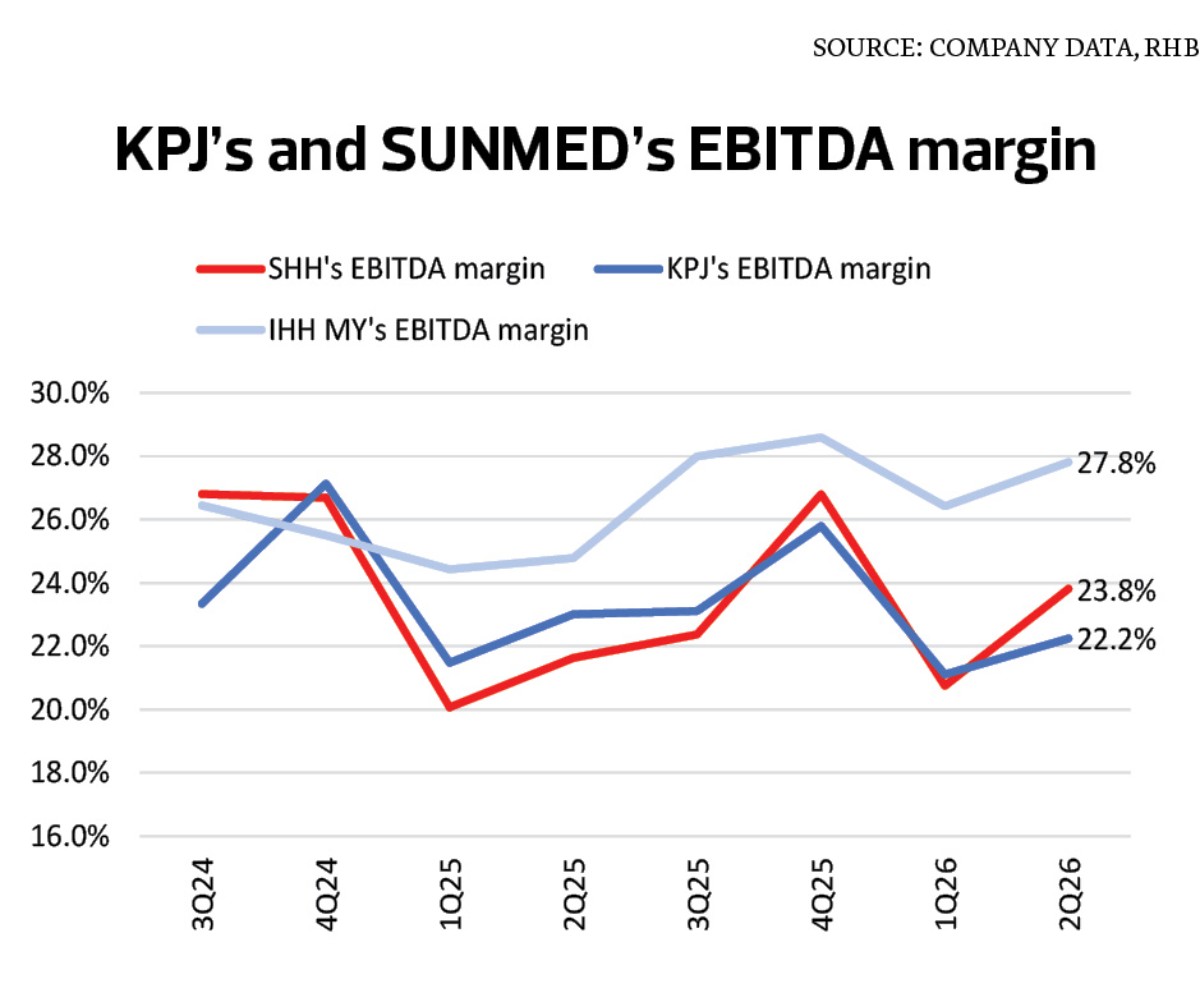
RHB RESEARCH (SEPT 7): The June reporting quarter results came ahead of expectations, and we see earnings growth momentum sustaining into the second half from filling existing and newly added bed capacity, alongside cost initiatives. Our sector rating is still anchored by the inherent inelasticity of clinical demand, which continues to provide a defensive shelter against potential domestic inflationary pressures and broader geopolitical volatility.
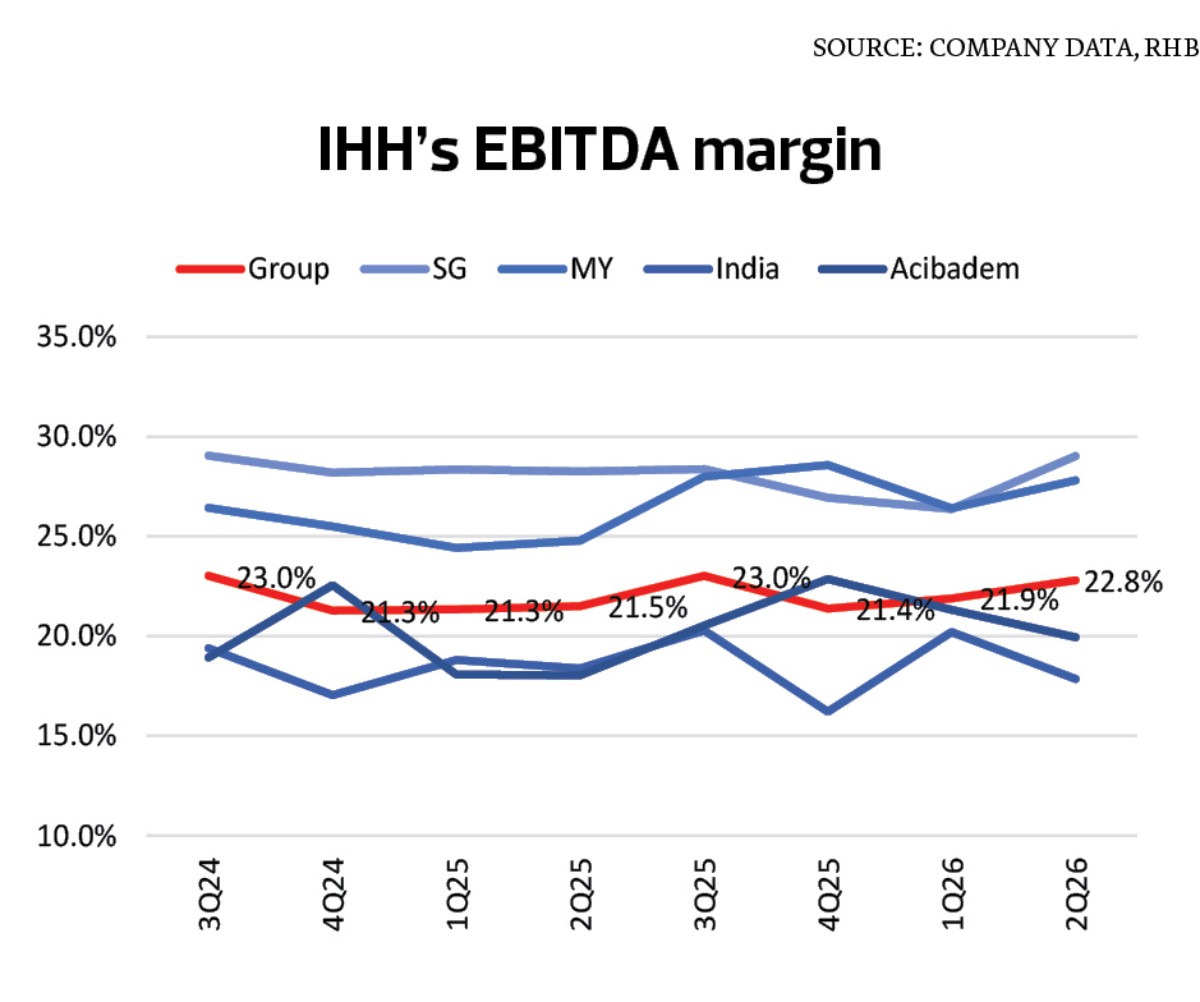
Our earnings estimates and target price (TP) revisions were generally positive following the sector’s robust post-festive season rebound in 2Q26. Notably, we upgraded IHH Healthcare Bhd (KL:IHH) to a “buy” with a higher TP of RM9.54 after its 1HFY26 core earnings of RM1 billion (+22% y-o-y) came in at 52% and 50% of our and consensus estimates.
The quarter was overshadowed by the resignation of KPJ Healthcare Bhd (KL:KPJ) president and managing director Chin Keat Chyuan on Aug 21, which wiped out RM1.9 billion of market cap over three sessions and, for us, removes the visibility that underpinned KPJ’s top pick status.
IHH is our new sector top pick. It offers a stable management team, upward earnings revisions, and trades at an undemanding 12.8 times 12-month forward EV/Ebitda (close to its five-year mean). Three caveats: (i) IHH’s earnings upgrade is driven entirely by Türkiye, where translation and Malaysian Financial Reporting Standard (MFRS) 129 effects add volatility; (ii) Full patient volume recovery in Singapore will likely still rely on price-discounted packages; and (iii) the Delhi High Court-ordered forensic audit at Fortis Healthcare Ltd — being an investigative exercise — carries no immediate balance sheet impact, but may create a trading overhang while it is conducted. We would view the resulting weakness as an entry point.
Sunway Healthcare Holdings Bhd’s (KL:SUNMED) 1HFY26 core earnings of RM123 million (+49% y-o-y) accounted for 42% of our and consensus full-year estimates — in line, given our expectation of a stronger 2HFY26.
Operating metrics were the sector’s strongest: bed occupancy rate of 73% (75% ex-Sunway Medical Centre Ipoh); double-digit patient admissions growth in y-o-y and q-o-q terms; inpatient revenue intensity rose 19% y-o-y; and adjusted Ebitda margin up 3.1 percentage points (ppts) q-o-q to 23.8% on lower gestation drag.
The soft spot is the foreign patient contribution, at 12.6% of revenue (-2.2 ppts q-o-q) on slower patient inflows from Indonesia. With 385 beds available for licensing and payor pressure easing, we expect further margin expansion in 2HFY26. At 32.7 times 12-month forward EV/Ebitda, its valuation leaves no room for slippage, but we believe the premium is sustainable on above-peer growth and light institutional positioning.
Bursa Malaysia Bhd
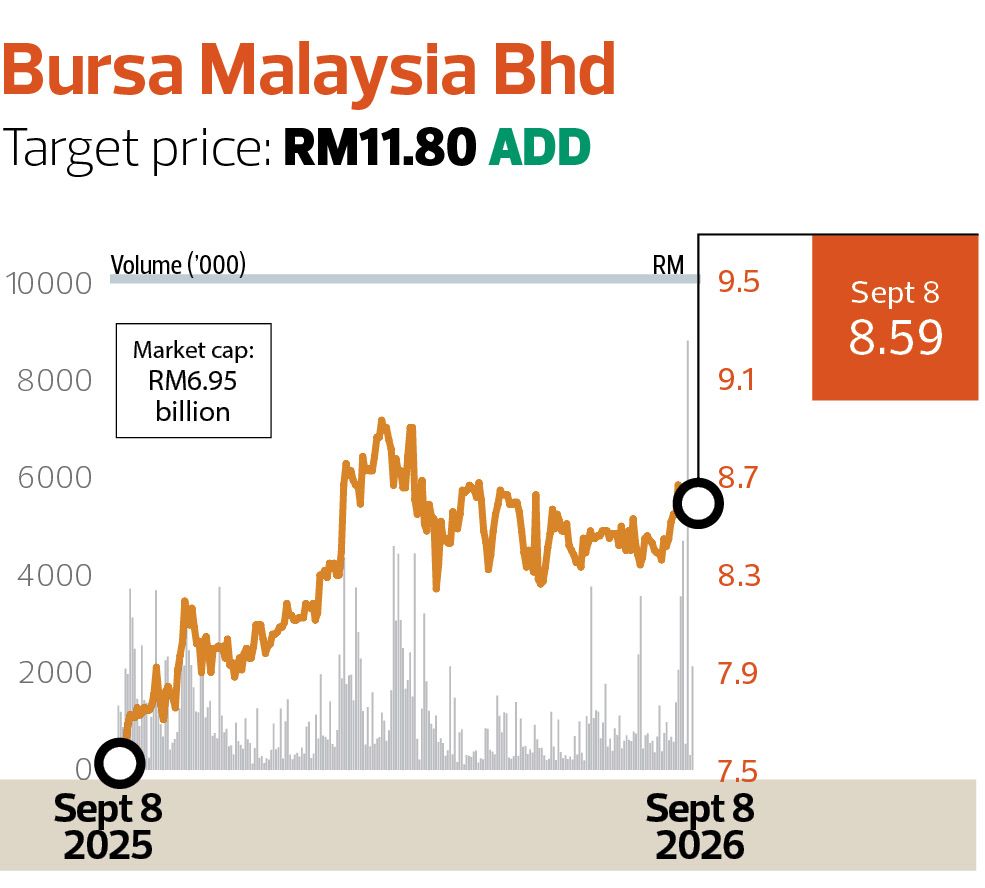
Target price: RM11.80 ADD
CGS INTERNATIONAL (SEPT 7): On Sept 3, we hosted a physical meeting for Bursa Malaysia Bhd (KL:BURSA) with more than 20 institutional investors to discuss its “MY Value Up” programme. Bursa stated that public listed companies (PLCs) would start to submit their value-up plans towards end-2026 and that the information will be uploaded to a micro site. Participation in “MY Value Up” is voluntary, at least in 2026/27.
The following are the key takeaways from the meeting: (i) participation in the “MY Value Up” programme is not confimed to the 88 companies selected by Bursa but open to all PLCs; (ii) some of the 88 companies highlighted that it could be a challenge for them to provide some of the financial targets as their earnings are affected by external factors that are beyond their control; and (iii) Bursa may introduce a new index that includes companies with outstanding performance under the criteria of “MY Value Up”.
We are positive on the impact of the implementation of “MY Value Up” on the equity market given its aim to improve the transmission of information from PLCs to investors and enhance PLCs’ commitments to maximise shareholder value. In turn, this could increase trading activity in the market, in our view.
QES Group Bhd
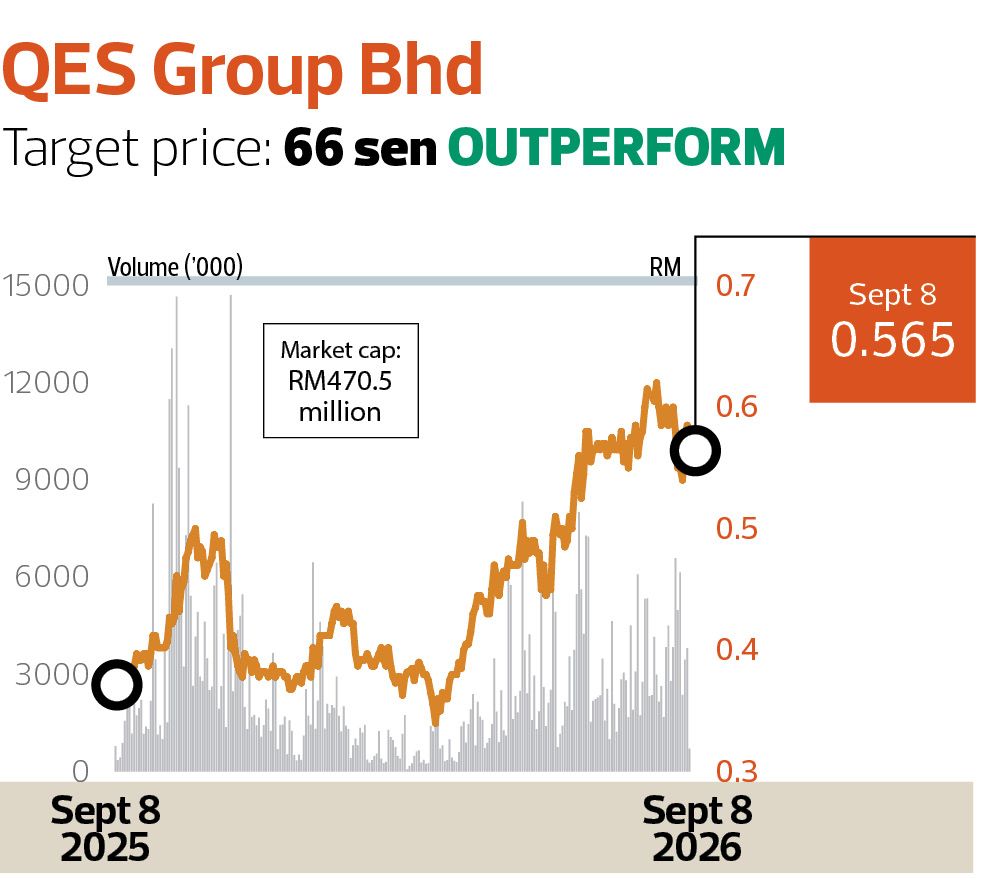
Target price: 66 sen OUTPERFORM
PUBLICINVEST RESEARCH (SEPT 7): We recently attended a physical briefing hosted by the QES Group (KL:QES), which was represented by group managing director Chew Ne Weng and Unicomp Technology vice-president (international operations, strategy and mergers and acquisitions) Sean Lyu. (Unicomp will indirectly hold 10% of QES upon completion of a private placement exercise.) The key highlight of the briefing was the two collaboration projects with China’s players, namely, X-ray inspection and advanced packaging tools. These projects would play a key role in the group’s revenue target of RM500 million by FY2030, a decent CAGR of 14%. On a more positive note, the outstanding order book has risen from July’s RM137 million to RM155 million, implying that it has secured an estimated RM45 million in new orders in the last month.
To our surprise, the group has also received some inspection machine orders from two US-based optical photonics players, namely, Customer C and Customer T. Though it only made up 10% of the current order book under the value engineering segment, it is likely to gain traction from this area in view of the aggressive expansion plans by the US optical photonics players.
To free up the extra floor space for new production lines in the Shah Alam plant, the group is phasing out some ageing Computer Numerical Control tooling machines.
Hong Leong Industries Bhd
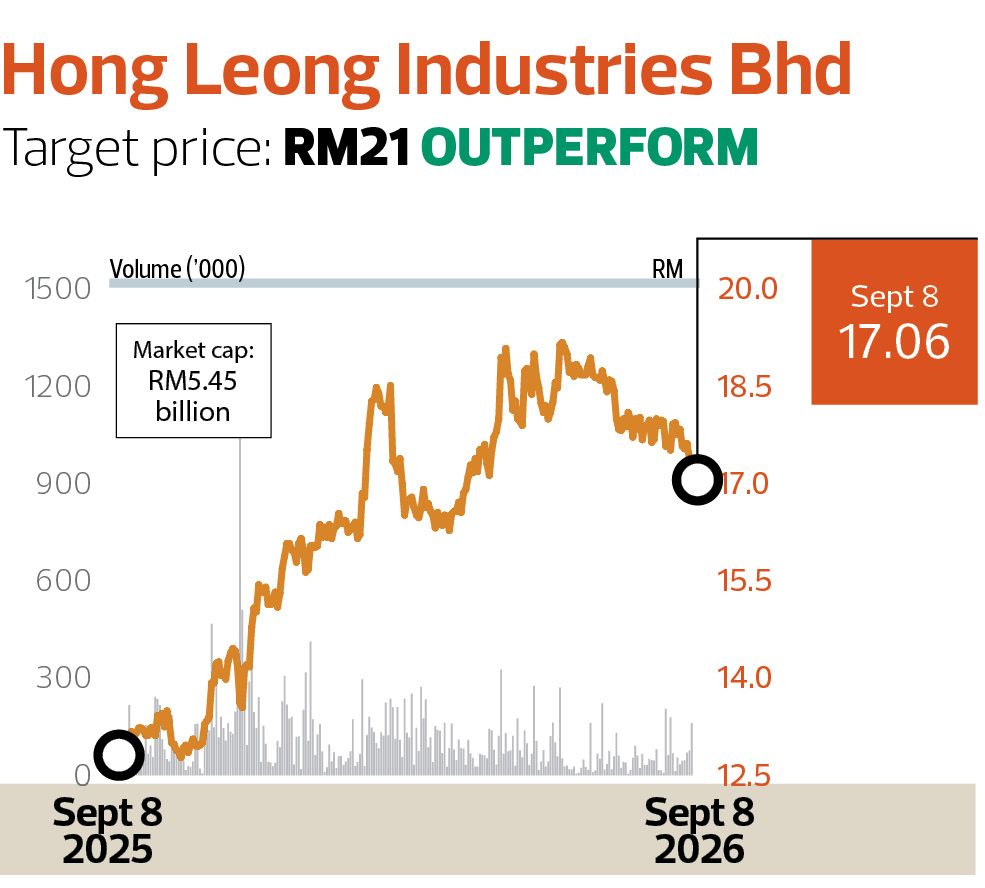
Target price: RM21 OUTPERFORM
KENANGA RESEARCH (SEPT 8): Hong Leong Industries (KL:HLIND) is riding towards the next phase of sustaining its earnings base by focusing on higher-margin big bikes; untapped market of Yamaha Genuine spare part market (RM2 billion-RM3 billion); and brand loyalty rewards application.
Meanwhile, by riding sticky brand loyalty (on Yamaha’s reliable product quality and strong resale value), it is well positioned to sustain its performance amid intensifying competition from Chinese manufacturers. Over the next two to three years, it plans to introduce a total of 15 to 17 new models that are expected to boost volume and margins.
We continue to like Hong Leong Industries: (i) as it is a strong proxy to the booming gig economy given the critical role of motorised two-wheelers in executing online delivery transactions; (ii) for its association with the strong Yamaha motorcycle brand in Malaysia and the brand’s market leader position in the local motorcycle segment; and (iii) for its solid war chest with a net cash of RM2.1 billion that could be deployed for earnings-accretive acquisitions. Its dividend yield is also attractive at 6%.
We maintain our forecasts, TP of RM21 and “outperform” call. It offers an attractive dividend yield of 6%.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.