


This article first appeared in Capital, The Edge Malaysia Weekly on September 14, 2026 - September 20, 2026
BURSA Malaysia Bhd (KL:BURSA) will welcome three new ACE Market listings this week, spanning upstream oil and gas (O&G) services, industrial engineering, and food and beverage manufacturing.
Upstream O&G services provider United Asiapac Energy Bhd (KL:UNIPAC) is slated to join the bourse on Sept 14, followed by coffee and tea extract powder blend manufacturer Butterfield FB Bhd (KL:BFIELD) the next day. Mechanical engineering services provider Pioneer Heat Holdings Bhd (KL:PIONEER) is slated to list on Sept 17.
United Asiapac’s listing was postponed from Aug 19, to allow the company time to issue a supplementary prospectus containing clarifications and details of a new contract. The supplementary prospectus was issued on Aug 21.
Butterfield will be the largest of the three companies, with an initial public offering (IPO) market capitalisation of RM384 million based on its issue price of 48 sen per share. United Asiapac is valued at an IPO market capitalisation of RM192.5 million at 35 sen per share, while the smallest, Pioneer Heat, will make its debut with a market capitalisation of RM86.7 million at its 25 sen IPO price.
Butterfield is raising RM72 million in gross proceeds, United Asiapac RM48.7 million, and Pioneer Heat RM21.7 million.
Butterfield’s existing shareholders are also offering for sale 72 million shares, or 9% of its enlarged share base, to raise RM34.56 million, while Pioneer Heat’s shareholders are offering 17.35 million shares, or 5% of its enlarged share base, to raise about RM4.34 million. United Asiapac has no offer-for-sale component.
Research houses see upside for United Asiapac and Butterfield. Mercury Securities’ fair value for United Asiapac is 39.5 sen, 12.9% higher than its IPO price. Public Investment Bank values Butterfield at 56 sen, 16.7% higher than its IPO price of 48 sen. On Pioneer Heat, TA Securities ascribed a fair value of 24 sen, one sen below its IPO price.
United Asiapac Energy Bhd
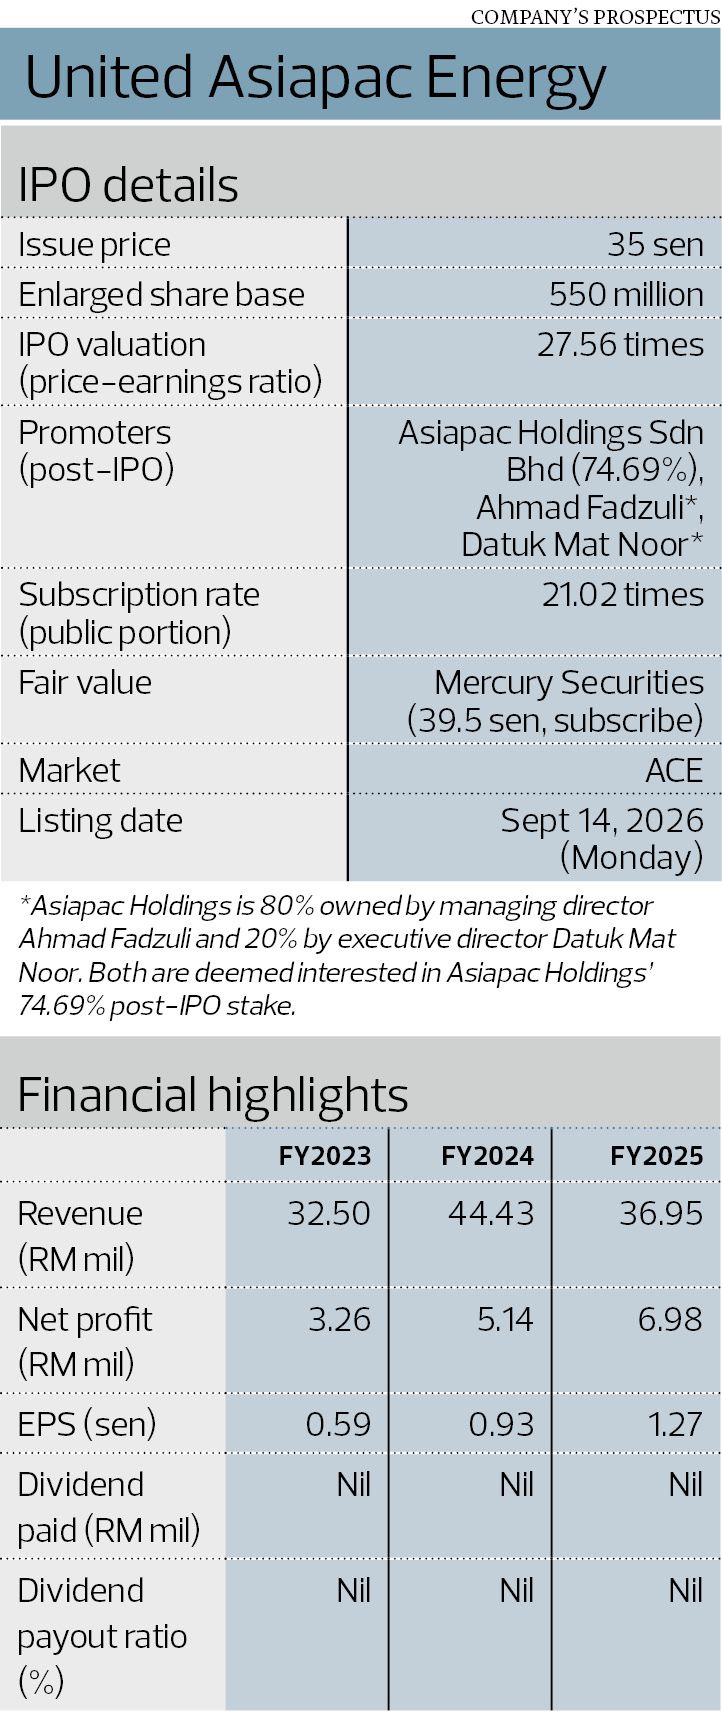
United Asiapac specialises in well intervention services for Malaysia’s upstream O&G industry, including fishing, plug and abandonment (P&A), sidetracking and other specialised services. Established in 2013, the group operates across Peninsular Malaysia, Sabah and Sarawak, and has limited operations in Singapore.
The group earns from both specialised equipment and manpower deployment. Equipment accounted for 79.7% of revenue in the nine months ended February 2026, with manpower services contributing the remaining 20.3%. Mercury noted that United Asiapac can continue charging daily equipment rental and manpower standby rates even when active well intervention work is delayed.
Mercury estimates that the company had about 21% of Malaysia’s fishing and P&A market based on its FY2025 revenue of RM37 million. Industry expenditure is projected to rise from RM175.9 million in 2025 to RM445.2 million by 2029, a compound annual growth rate (CAGR) of 26.1% that will aid the group’s performance.
Mercury described United Asiapac as a “leading player in Malaysia’s expanding well intervention market ... Backed by an established track record, long-standing operator relationships, and eight PETRONAS SWEC licences, UAEB is well positioned to capture a larger share of this growth”.
Petroliam Nasional Bhd (PETRONAS) is expected to have 663 contracted wells between 2025 and 2028, including 293 P&A wells. United Asiapac holds eight PETRONAS Standardised Work and Equipment Category (SWEC) licences covering its core activities.
PETRONAS’ capital expenditure (capex) was skewed towards upstream activities. PETRONAS spent RM54.2 billion on capex in 2024, of which 52%, or about RM28 billion went towards upstream operations.
The group’s revenue increased from RM32.5 million in FY2023 to RM44.4 million in FY2024, before falling 16.8% to RM37 million in FY2025 despite the number of fields serviced increasing to 43 from 38.
Mercury attributed the weaker top line to better project planning and equipment utilisation by clients, which reduced rental billings.
Profitability, however, moved in the opposite direction. Gross margins increased from 24.3% in FY2023, to 39.3% in FY2025. Meanwhile, profit after tax and minority interest (Patami) margins climbed from 10% in FY2023 to 18.9% in FY2025, driven by the group’s shift towards owning, rather than renting, equipment used in its jobs. Equipment rental costs fell from 44.8% of equipment revenue in FY2023, to 25.3% in FY2025. For 9MFY2026, it fell to 12.5%.
Mercury says United Asiapac “consistently demonstrated superior profitability compared to both global and local oilfield service peers”, underpinned by its specialised capabilities and capital-efficient operating model. Mercury compared United Asiapac’s 9MFY2026 gross and profit after tax (PAT) margins of 56.2% and 29.2% respectively with local peer averages of 25.4% and 12.2%.
That earnings profile, however, comes with substantial customer concentration as PETRONAS Carigali was its largest customer in FY2025, contributing RM29.47 million, or 79.76%, of the group’s RM36.95 million revenue.
PETRONAS-related projects continued to account for about 73% of revenue in the nine months ended February 2026. Mercury noted that while “most contracts are awarded through competitive tenders and are project-based in nature, there is no assurance that existing contracts will be renewed or that the group will continue to secure new projects upon expiry”.
About 47.7% of United Asiapac’s IPO proceeds will be used to acquire more well intervention tools, equipment and DNV-certified cargo baskets within 36 months of listing. The spending includes a break-out unit for its Kemaman base, allowing tools to be assembled and tested in-house, while the cargo baskets will allow multiple sets of equipment to be deployed simultaneously across project sites.
United Asiapac also plans to expand into e-line, slickline and wireline recovery services as well as hydrocarbon well cleanout services. The expansion follows enquiries from existing and prospective customers seeking integrated well intervention services from a single provider.
The group’s ongoing projects carried a total purchase order value of RM61.1 million, of which RM27.3 million remained outstanding as at the prospectus’ latest practicable date, for services through February 2027.
United Asiapac subsequently reported FY2026 revenue of RM52.26 million and net profit attributable to shareholders of RM15.41 million, up from RM36.95 million and RM6.98 million respectively in FY2025. Mercury forecasts FY2027 revenue of RM56.1 million and core net profit of RM16.3 million.
Mercury ascribed a 39.5 sen fair value based on 13.3 times FY2027 earnings, representing a 20% premium to the five-year historical average price-earnings ratio (PER) of selected local O&G service providers. Following the IPO, Asiapac Holdings will retain a controlling 74.69% stake in United Asiapac.
The group does not have any formal dividend policy at present.
TA Securities Holdings Bhd was the principal adviser, sponsor, underwriter and placement agent. United Asiapac’s public portion was oversubscribed 21.02 times.
Butterfield FB Bhd
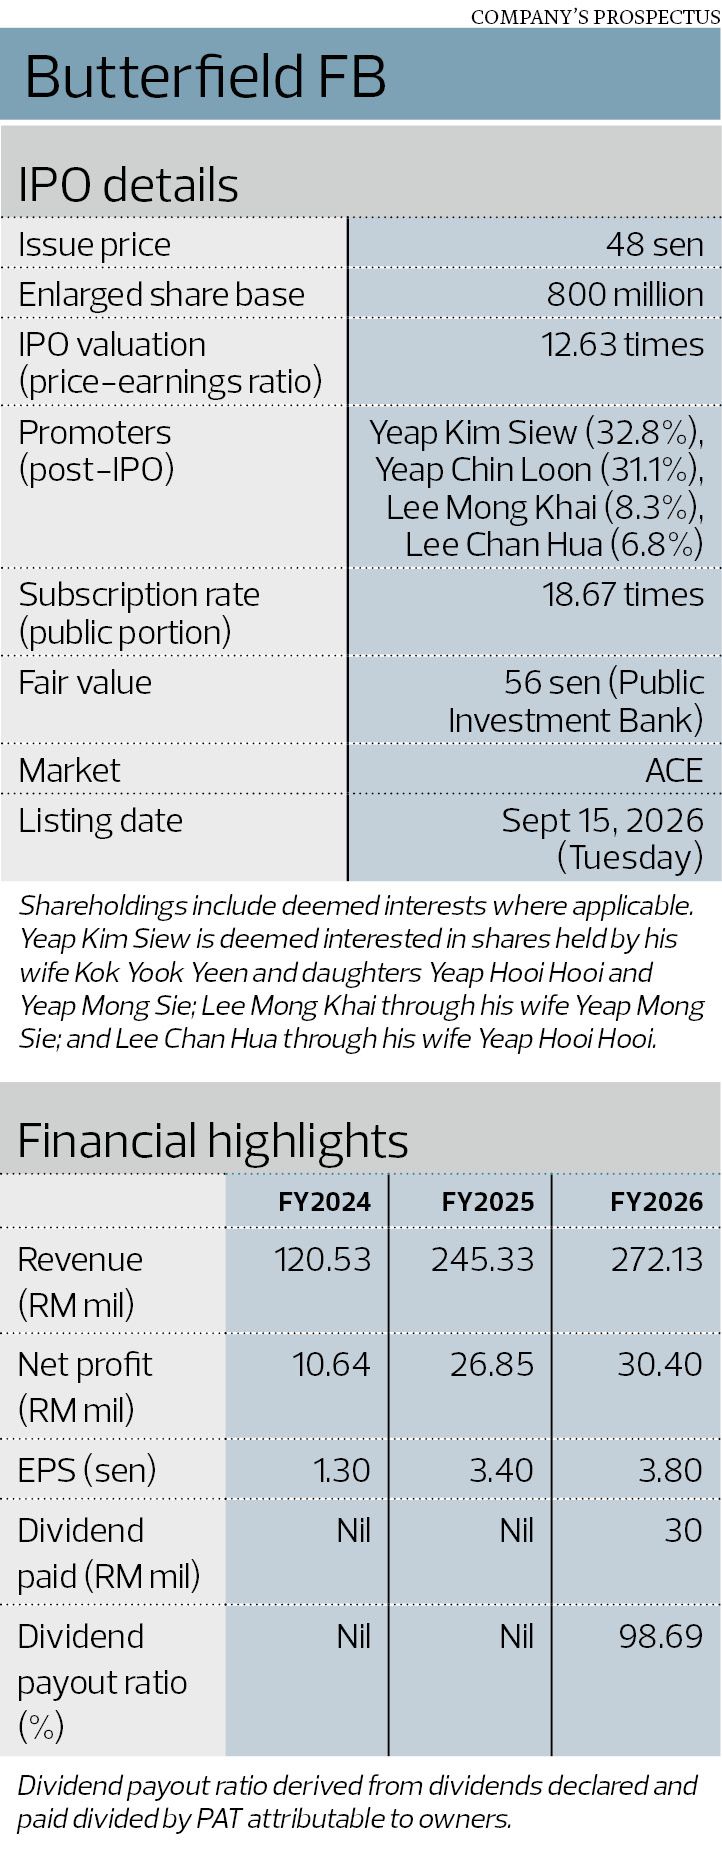
Butterfield FB is a manufacturer of coffee and tea extract powder blends that also sells food ingredients and instant beverage premixes. The group provides end-to-end services from formulation all the way to delivery. As at July 20, 2026, Butterfield had 151 coffee and tea formulations, comprising 98 coffee and 53 tea blends, all halal certified.
PublicInvest highlighted Butterfield’s proprietary formulations and in-house product development as one of its competitive advantages. “BFIELD retains ownership and confidentiality of its formulations, which deliver distinctive taste profiles that are difficult to replicate, supporting consistent product quality and continued customer engagement.”
Malaysia and Thailand are the group’s key markets, accounting for 57% and 38% of FY2026 revenue respectively. Butterfield had an estimated 11.8% share of Malaysia’s coffee and tea extract powder blend market in 2025 according to data from Smith Zander, cited by PublicInvest.
Revenue nearly tripled to RM272.1 million in FY2026 from RM97.9 million in FY2023, mainly driven by stronger demand for its products, amid higher sales volumes and average selling prices (ASPs).
Manufacturing accounted for 78.1% of FY2026 revenue, led by coffee extract powder blends at 71.6%, while tea extract powder blends contributed 6.5%. Food ingredients accounted for another 19.3% of revenue while instant beverage premixes contributed 2.6%.
Gross margins have improved from 18.8% in FY2023 to 21.7% in FY2026; as have net profit margins, from 8.9% in FY2023 to 11.2% in FY2026.
“The improvement in FY2026 was supported by higher coffee extract powder blend ASPs and the use of lower-cost inventory,” PublicInvest says.
Customer concentration was flagged as a key risk, as its largest customer, Aik Cheong Group, contributed 16.6% of FY2026 revenue. The group’s relationship with Aik Cheong has lasted 17 years; its average relationship with its top five customers is around 13 years.
The group’s many local and international certifications “reinforce product quality, credibility and market reputation, supporting further growth in local and export markets”, adds PublicInvest.
More than half of the proceeds to be raised (RM72 million) will be used for working capital. Another RM15.2 million is earmarked for expanding its Bukit Minyak, Penang, premises, while RM13 million is allocated for strategic investments or mergers and acquisitions.
The Bukit Minyak expansion will add a fourth manufacturing line and raise annual production capacity by about 48% to 12,597 tonnes, while storage capacity will increase 17% to 22,698 tonnes. Existing production and storage facilities were 71.7% and 93.9% utilised respectively in FY2026.
Butterfield has also expanded its matcha production amid growing demand. The group’s third manufacturing line, which began operations in February 2026, has annual capacity of 312 tonnes, dedicated to matcha powder blends. It is targeting 300 tonnes of annual matcha sales within the next two to three years.
Net profit is expected to edge up to RM31.2 million in FY2027, from RM30.4 million in FY2026. PublicInvest expects it to grow to RM41.6 million by FY2029, representing a three-year CAGR of about 11%.
It ascribed Butterfield a fair value of 56 sen, based on 13 times CY2027 earnings, representing a discount of roughly 10% to the Bursa Malaysia Consumer Products and Services Index’s PER of about 15 times.
“Despite its stronger profit margins and more robust gearing profile in comparison with its closest peer, we believe the discount is justified, given BFIELD’s relatively small market capitalisation and reliance on a key customer,” PublicInvest says.
Butterfield currently has no formal dividend policy.
M&A Securities Sdn Bhd was the principal adviser, sponsor, underwriter and placement agent. Its public portion shares were oversubscribed by 18.67 times.
Pioneer Heat Holdings Bhd
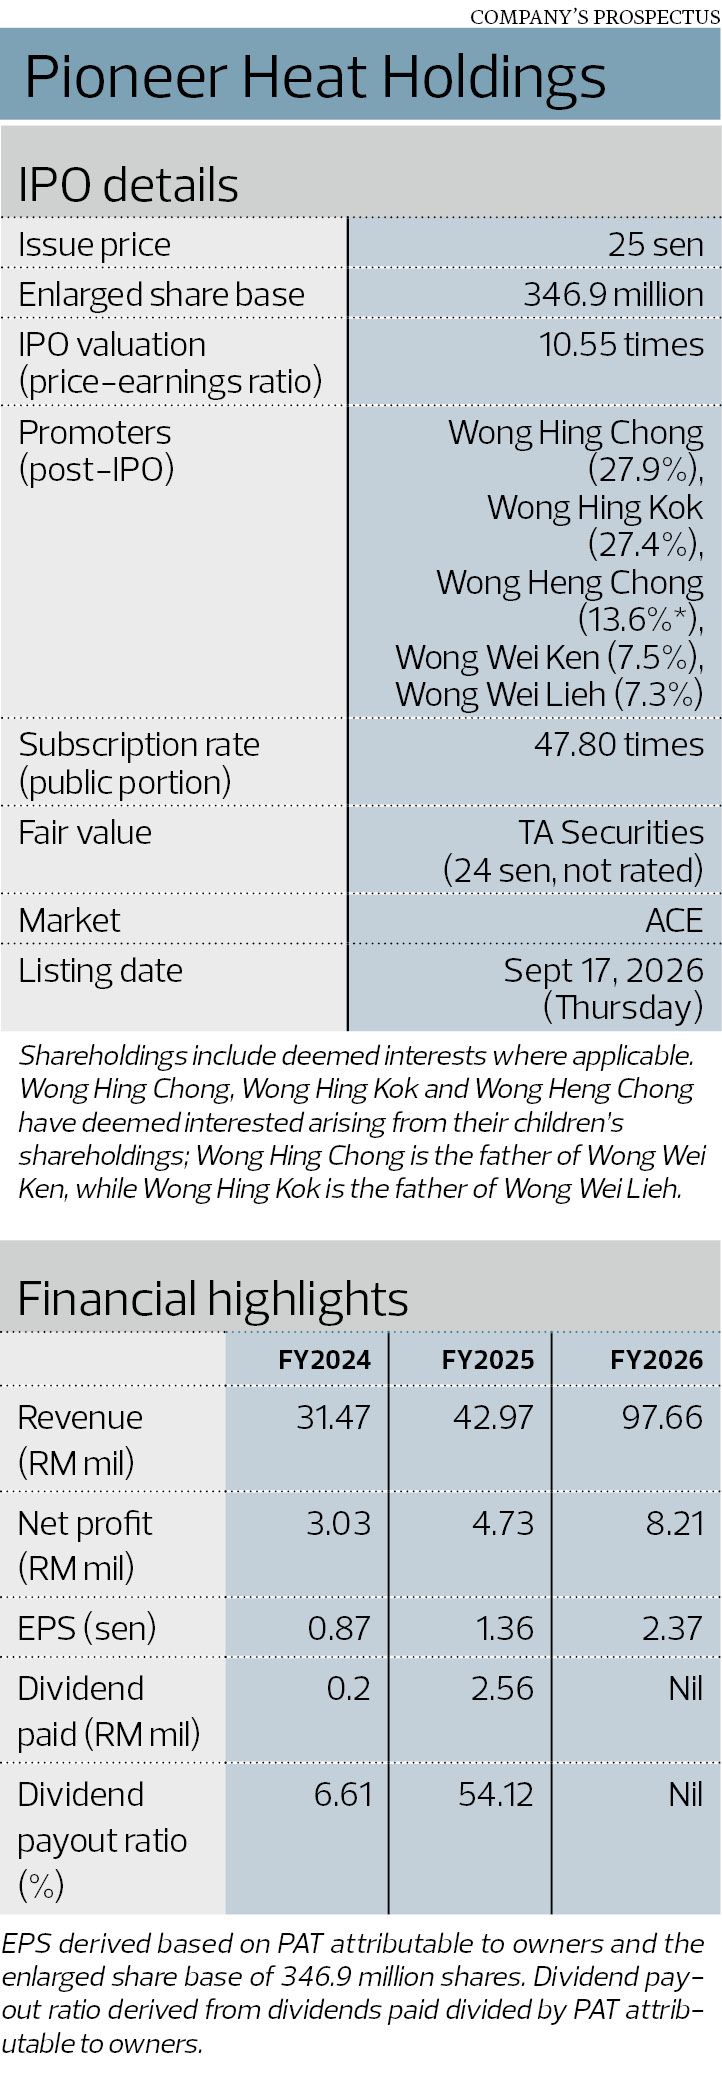
Established in 1997, Pioneer is involved in mechanical engineering services and civil engineering projects across the O&G, petrochemical, utility and manufacturing industries.
The group’s core expertise is in piping system engineering, alongside specialised services including heat treatment, flange management and non-destructive testing (NDT). Its mechanical engineering business spans engineering, procurement, fabrication, installation, commissioning, repair and maintenance across the life cycle of industrial plants.
Mechanical engineering was the largest contributor to revenue, accounting for 75.5% of the group’s RM97.7 million FY2026 revenue, with civil engineering accounting for the remainder.
TA Securities highlighted the breadth of Pioneer Heat’s services as one of its main competitive advantages. “The ability to support customers across different stages of a plant’s life cycle also provides opportunities for recurring maintenance works and repeat projects, strengthening customer relationships and supporting long-term business sustainability.”
Growth accelerated in FY2026 as revenue surged 127.3% to RM97.7 million from RM43 million in FY2025, while core net profit rose 57.3% to RM8.2 million from RM5.2 million a year earlier. The improved performance was mainly due to higher revenue recognised from Project Basil in Kuantan, Pahang, and the commencement of Project Tankr and Project Brex.
Pioneer Heat maintains a sizeable in-house technical workforce of around 252 employees.
The group’s future remains supported by activity in Pioneer Heat’s end markets. Data from Smith Zander cited by TA shows that Malaysia’s selected mechanical engineering services industry grew at a CAGR of 8.58% to RM8.68 billion between 2022 and 2025. The value of construction work done for non-residential buildings, meanwhile, grew 11.48% annually to RM51.63 billion over the same period.
TA Securities pointed to PETRONAS’ 14 scheduled downstream plant turnarounds over the next two years as one of the factors expected to support demand for mechanical and civil engineering services.
The largest portion of the IPO proceeds, RM7.9 million, will be used for working capital. Of the remaining cash, RM4 million is earmarked for a new headquarters in Sendayan, Negeri Sembilan, RM4 million for machinery and equipment, RM2.07 million for a new Sarawak office and workshop, and RM3.7 million for listing expenses.
On Sarawak, “the group intends to strengthen its presence in East Malaysia through the establishment of a new office and workshop in Bintulu, Sarawak, supported by the continued demand for its mechanical engineering services in the region”, TA Securities says.
On future earnings, TA expects core earnings growth of 17.2% in FY2027, and 9.2% in FY2028. Core profit margins are assumed at 9% and 8.8% respectively.
TA nevertheless identified dependence on three major customers and cited another key risk in revenue and earnings volatility due to project-based operations.
“At the IPO price of RM0.25 per share, Pioneer is valued at 10.5x FY26 core EPS (earnings per share). We derive a fair value of RM0.24 per share, by applying a target PER of 8.0x to CY28 EPS.”
Post-IPO, Pioneer Heat is expected to move from net debt of 0.3 times to a net cash position of 0.4 times. The group currently has no formal dividend policy.
Malacca Securities Sdn Bhd is the principal adviser, sponsor, underwriter and placement agent. The IPO was oversubscribed by 47.8 times.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.