

This article first appeared in The Edge Malaysia Weekly on August 31, 2026 - September 6, 2026
WHAT does Kerjaya Prospek Group Bhd (KL:KERJAYA) see in mechanical and electrical (M&E) engineering player ES Sunlogy Bhd KL:SUNLOGY) that warrants a 31% stake purchase?
The answer could lie in a straightforward strategic fit: Kerjaya Prospek brings the construction capabilities and project pipeline, while ES Sunlogy provides the M&E expertise needed for increasingly complex projects.
“Kerjaya Prospek will be the main contractor and we will be the arm for its M&E,” ES Sunlogy CEO Sam Teo Chee Tong tells The Edge in an interview.
Kerjaya Prospek first subscribed for a 9.09% stake in ES Sunlogy on July 16, before acquiring 21.91% equity interest from other shareholders on Aug 14 and 17 through direct business transactions. In total, Kerjaya Prospek has invested RM64.31 million, or an average of 26.94 sen per share, for the 31% stake — at a discount of more than 30% to the prevailing market price.
The two companies have worked together since 2020, with ES Sunlogy acting as a subcontractor for Kerjaya Prospek. The enlarged shareholding could now take that relationship a step further, with the two groups looking to collaborate on mixed-use developments, industrial projects and infrastructure tenders.
Industrial projects could be particularly significant. As Malaysia continues to attract semiconductor and high technology manufacturing investment, M&E can account for a substantial part of the construction package. Teo also sees potential in hospital projects, where ES Sunlogy has M&E experience.
Teo says the investment was made in a friendly manner and does not signal a change in control at ES Sunlogy. Kerjaya Prospek has indicated that it does not intend to trigger a mandatory general offer.
“I would not say that Kerjaya Prospek will be coming in and stepping into ES Sunlogy and then taking over ES Sunlogy,” he says, describing Kerjaya Prospek instead as a “strategic partner”.
The timing of the partnership is notable. ES Sunlogy is entering a new phase of growth, shifting its focus towards industrial M&E and higher-value power infrastructure while selectively expanding into renewable energy (RE) and battery energy storage systems (BESS).
Building a bigger M&E business
ES Sunlogy had an unbilled order book of about RM307 million as at July 31, providing revenue visibility into the next two financial years. More significantly, its tender pipeline has swelled to RM3.86 billion, a historical high for the group.
But management is not looking to chase the largest possible order book.
Teo says the group remains selective, assessing prospective projects based on their technical requirements, execution capabilities, commercial terms, duration and probability of success.
“We want to grow sustainably rather than expand at any cost,” he adds.
The composition of the tender pipeline also reflects the group’s shift towards higher-value work. Industrial projects account for about 29% of the pipeline, with opportunities in semiconductor and high-tech manufacturing, while infrastructure and solar projects make up another 52%. Commercial and residential projects account for the remaining 19%.
The changing mix could also support margins, as industrial and infrastructure projects typically have shorter execution periods than residential developments.
Residential projects can take three years or longer to complete, tying up manpower and increasing exposure to unforeseen costs. Industrial and infrastructure jobs, by comparison, are typically completed within 12 to 18 months.
“The margin will be better due to the shortened completion of the project,” says Teo.
The group already has a track record in industrial M&E, having undertaken projects for multinational semiconductor companies across key manufacturing hubs in northern and southern Malaysia and the Klang Valley. Teo expects demand to remain supported by continued foreign direct investment and the expansion of high-value manufacturing capacity in the country.
Data centres are another potential source of work, given the number of projects in the pipeline in the country.
“More importantly, we are not only concentrated on the data centre side. Industry and utilities are also an important sector that we are going aggressively into,” he emphasises.
The broader strategy, therefore, is to build a more technically demanding, high-tech M&E business, with industrial projects and power infrastructure becoming key growth areas rather than relying solely on the current data-centre investment cycle.
Moving into higher-voltage infrastructure
Alongside industrial M&E, ES Sunlogy is seeking to establish itself in higher-voltage power infrastructure.
The group had historically been licensed to undertake electrical work of up to 132kV, including substations, upgrading works and interconnection facilities linking solar farms to the grid.
Last year, ES Sunlogy upgraded its licence to undertake projects of up to 275kV, allowing it to move into higher-voltage transmission and substation work.
It subsequently secured a project from Tenaga Nasional Bhd (KL:TENAGA) involving a 275/33kV main transmission intake in Lembah Beringin, Selangor.
Teo sees Tenaga-related work as an important focus for the next two to three years as ES Sunlogy builds its track record and relationship with the national utility.
The group is also pursuing private-sector opportunities, including substations and grid interconnection facilities for RE projects.
The move into 275kV work could give ES Sunlogy an edge in a less crowded market, given the licensing requirements and technical expertise needed to undertake such projects.
“I would say the challenges are still there. You need the licence for Tenaga to build 275kV,” says Teo.
Solar, BESS provide additional growth pillars
RE is another part of ES Sunlogy’s strategy, providing a recurring-income component alongside its project-based M&E business.
The group currently has interests in two solar farms with an effective combined capacity of about 30.68mw.
For the nine months ended April 30, 2026, the solar assets generated about RM6.8 million in revenue, accounting for 5% of the group’s revenue of RM165 million.
The group plans to participate in the Large Scale Solar 6 (LSS6) programme as a developer, targeting at least 100mw with a BESS component. It intends to partner with another party while retaining a majority stake.
Results of the LSS6 tender are expected in 2027.
Beyond Peninsular Malaysia, ES Sunlogy is also involved in the proposed Baram solar hybrid and BESS project in Sarawak, which is currently at the development stage. The proposed project has been expanded to 310mwac firm output, powered by 930mwp of solar capacity and 1860mwh of BESS capacity, with total investment estimated at about RM3.3 billion.
Teo says ES Sunlogy is expected to hold a 45% stake in one of the parties to the consortium, translating into an effective project value of about RM450 million for the group. The consortium is targeting a decision by the end of the year, after which the group would proceed with the next stage of development and fundraising.
The group is in discussions with banks and other financiers, with a potential funding structure involving sukuk, bank financing and equity.
BESS also provides ES Sunlogy with an opportunity to expand beyond conventional M&E work, particularly in Singapore, where it has already deployed battery systems at construction sites to reduce reliance on diesel generators and lower carbon emissions.
Singapore remains a measured expansion, however. The group currently has projects worth about RM62 million there, and Teo says the immediate priority is to execute the existing projects and establish a strong track record before pursuing new tenders more aggressively.
Fundraising expected to support next phase of growth
The breadth of ES Sunlogy’s growth plans means capital and execution discipline will become increasingly important.
The group currently has about 200 employees and believes its existing workforce can support annual revenue of up to RM400 million. But as project sizes increase, working capital requirements are becoming a more important consideration.
ES Sunlogy had cash and bank balances of RM4.39 million as at April 30, while a recent private placement raised RM18.76 million, bringing its available cash holdings to about RM23.15 million. Total borrowings stood at RM82.56 million, with gearing at about 0.64 times.
Teo says ES Sunlogy may undertake another fundraising exercise in the next financial year to support the execution of sizeable contracts.
For large RE projects, the group expects to rely substantially on external financing, with bank funding potentially covering about 85% of project costs and equity making up the remaining 15%.
Capital allocation will remain focused on strengthening the M&E business and developing the people and capabilities required to undertake larger and more technically demanding projects. RE and BESS will be expanded selectively where management sees sustainable returns.
Dividends, meanwhile, are not an immediate priority. ES Sunlogy currently has no dividend policy and does not intend to introduce one for now, with management preferring to reinvest in the business.
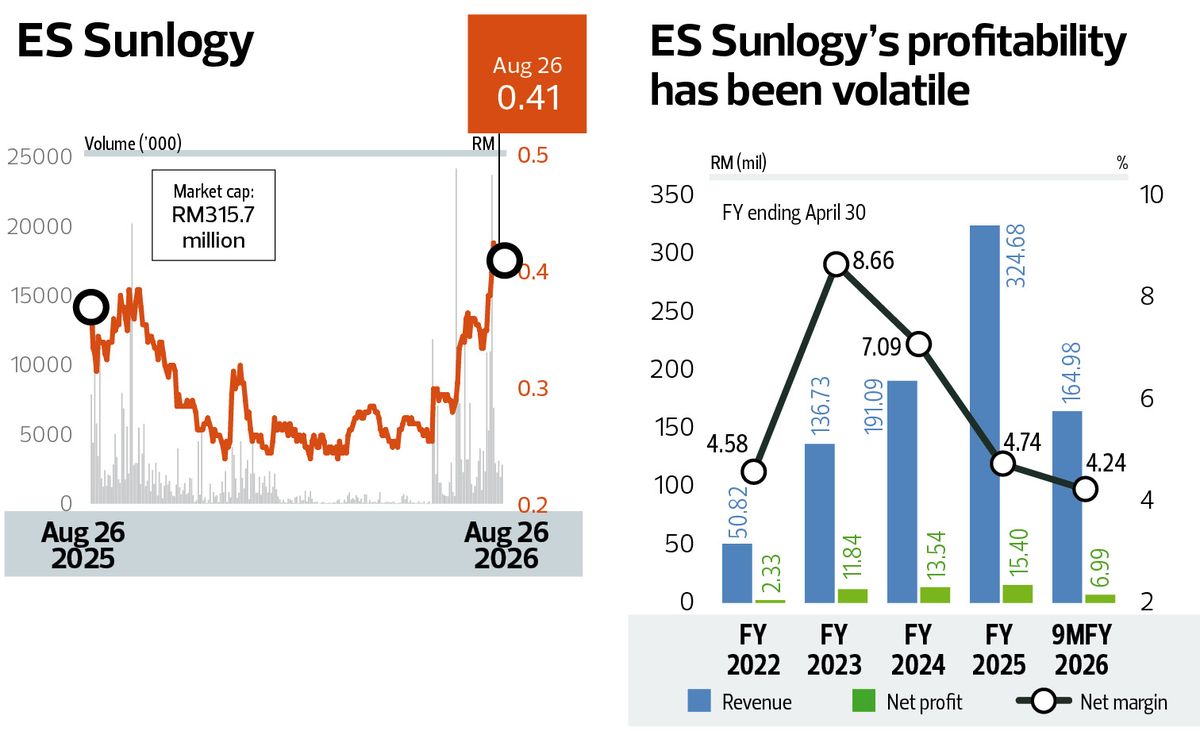
The need for capital discipline comes as the group enters a new phase of expansion after several years of strong top-line growth. Revenue rose in each of the past four financial years, more than sixfold from RM50.82 million in the financial year ended July 31, 2022 (FY2022) to RM324.68 million in FY2025, while net profit increased from RM2.33 million to RM15.4 million over the same period.
Profitability, however, has been more volatile, with net profit margin rising from 4.6% in FY2022 to a peak of 8.7% in FY2023 before easing to 7.1% in FY2024 and 4.7% in FY2025.
For 9MFY2026, revenue fell 31% year on year to RM164.98 million from RM239.18 million, while net profit declined by about 30% to RM6.99 million from RM10.03 million.
The weaker performance was mainly due to lower contributions from the M&E segment as projects were at different stages of completion compared with the previous corresponding period. Revenue from the trading segment also declined, as the previous year’s corresponding period included one-off sales of goods to subcontractors for certain projects.
ES Sunlogy was listed on the ACE Market on Feb 20, 2025, at an initial public offering (IPO) price of 30 sen per share. Its IPO promoters, executive director Chu Kerd Yee and managing director Khor Chuan Meng, now hold a stake of 20.9% and 14.8% respectively.
The stock has rallied from around 26 sen to close at 41 sen last Wednesday following news of Kerjaya Prospek’s emergence as a major shareholder, giving the company a market capitalisation of RM315.7 million. At 41 sen, the counter trades at about 25.5 times trailing earnings.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.