

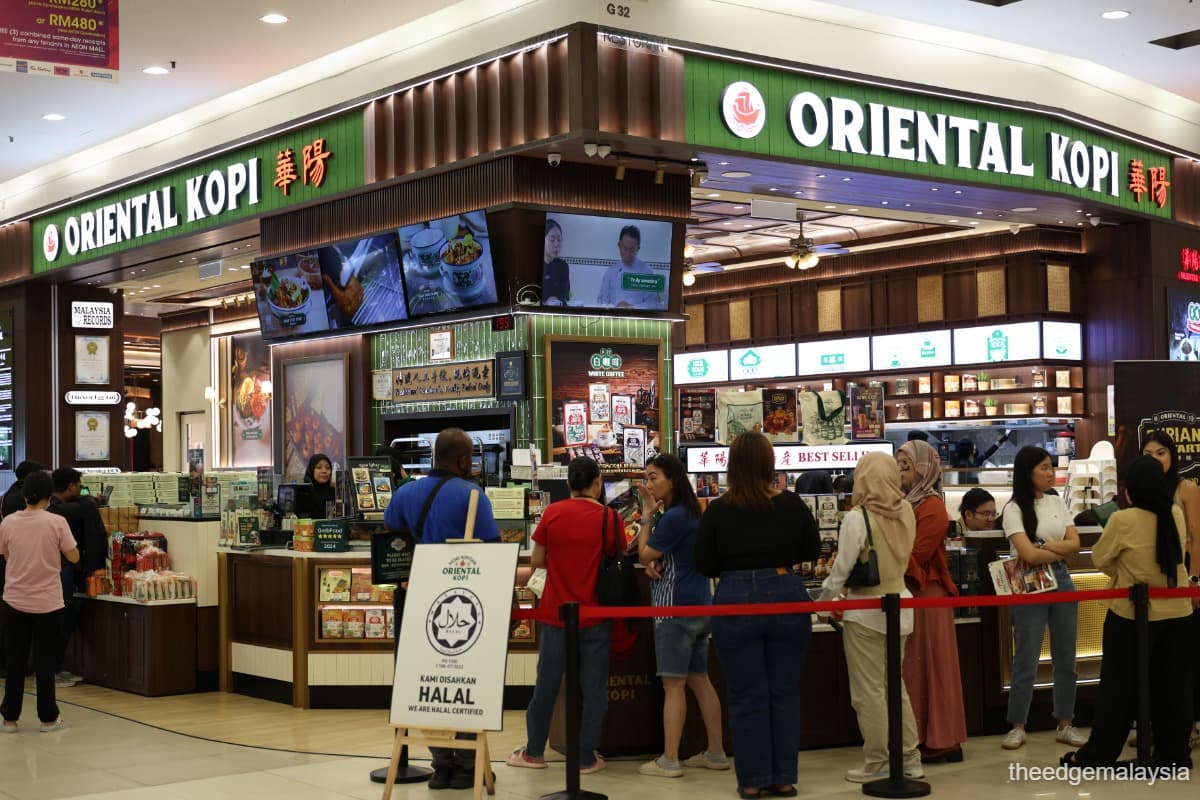
KUALA LUMPUR (Sept 1): A weaker-than-expected quarter sent Oriental Kopi Holdings Bhd (KL:KOPI) to its lowest in nearly a month during Tuesday trading while analysts cut outlook for the stock.
The consensus does not expect earnings to catch up in the remaining three months before the company’s financial year ends amid elevated costs from network expansion. Still, a majority of analysts are still bullish on the stock, betting on revenue growth as the new outlets mature.
“We expect stronger sequential earnings driven by new store openings and improving operating leverage,” Phillip Capital said and maintained the stock on ‘buy’.
Shares of Oriental Kopi fell eight sen or more than 7% to 97 sen, its lowest since Aug 5. This values the company that operates the eponymous restaurants at RM1.94 billion.
Oriental Kopi has lost more than 30% of its market value year-to-date as investors and analysts were turned off by disappointing results with its margins continuing to shrink from its aggressive expansions.
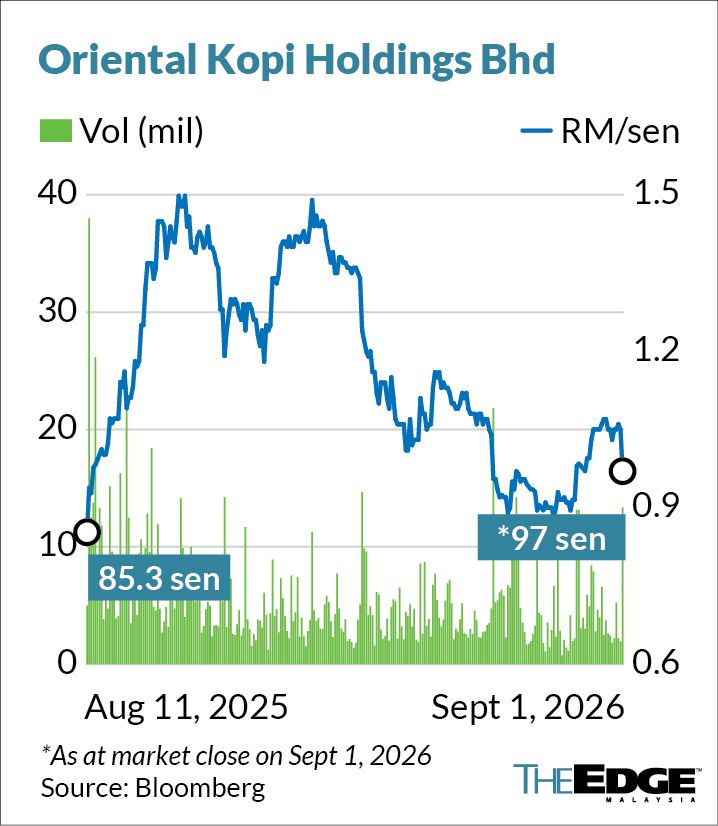
There are five ‘buy’, one ‘hold’ and one ‘sell’ call post-results with average target price of RM1.22, based on the seven research houses tracked by Bloomberg.
”We expect sales growth to remain healthy, albeit with a more gradual ramp from the enlarged outlet base as newer stores may take time to reach optimal productivity,” said RHB Research.
More importantly, RHB Research noted, is the sequential recovery in margins and the “broadly stable” operating expenditure which support “our view that operating leverage is beginning to kick in,” the house added.
Last week, Oriental Kopi reported that net profit in the three months ended June 30, 2026 (3QFY2026) was RM17 million, down over 5% when compared to the same quarter last year. Revenue, however, surged 34% year-on-year to RM156.63 million.
The consensus now expects net profit of about RM70 million on revenue of RM607 million for FY2026.