

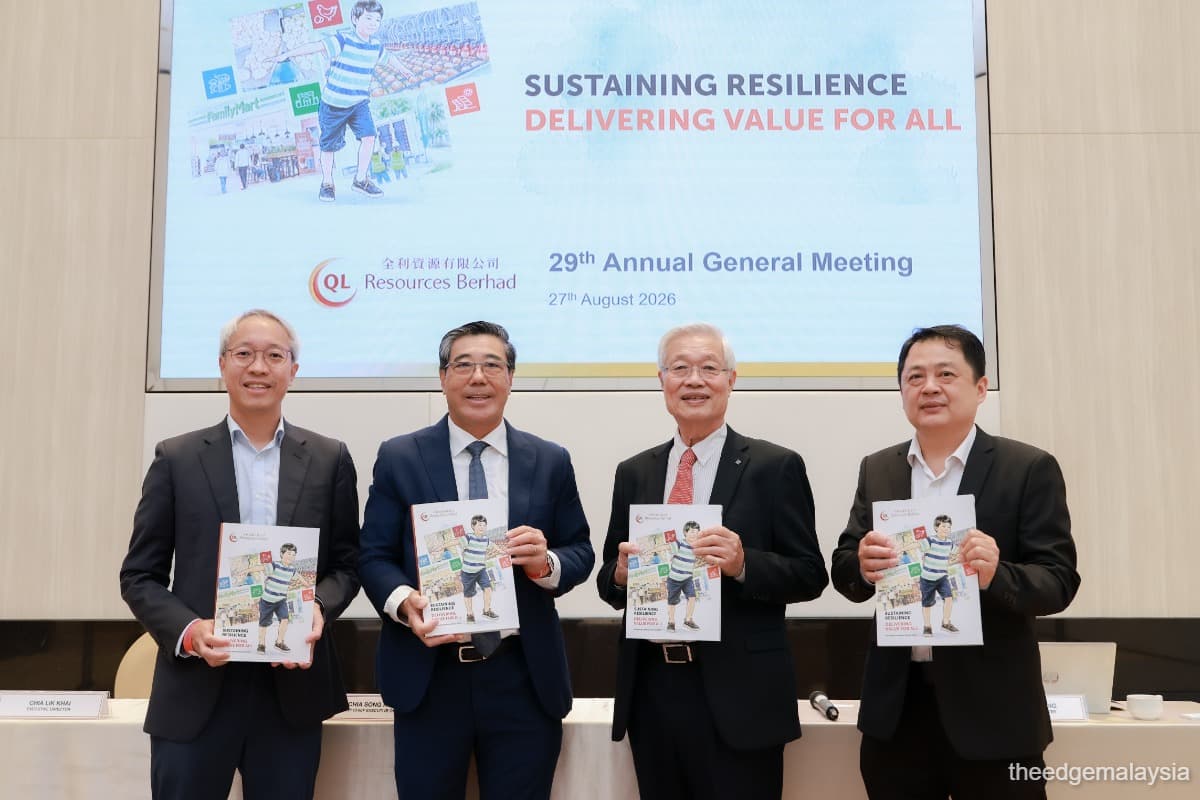
KUALA LUMPUR (Aug 27): QL Resources Bhd (KL:QL) expects egg prices to remain high over the next two quarters, supported by strong demand and tighter supply, which should help sustain margins in its livestock farming segment.
Its executive chairman Dr Chia Song Kun said at a press conference on Thursday that depressed egg prices had prompted farmers to cut production by retiring spent layers. As production takes time to recover, hot weather has also affected hen productivity, with hens laying fewer eggs. Adverse weather conditions such as haze could further disrupt production and prolong the current upcycle in egg prices.
Its group chief executive officer Chia Song Kooi said resilient demand should also support egg prices, as softer consumer sentiment could encourage consumers to eat more meals at home, with eggs remaining a staple food.
For QL Resources, higher egg prices could help offset continued pressure from feed costs. The group expects its livestock farming business to face higher feed costs, particularly for corn and soybean meal, amid rising energy and logistics costs.
Song Kooi said the group remains confident it can pass on higher costs to consumers through selling prices.
QL Resources’ largest revenue contributor, its integrated livestock farming (ILF) segment saw revenue rise 9% year-on-year (y-o-y) to RM943.02 million in the first quarter ended June 30, 2026 (1QFY2027), but profit before tax (PBT) fell 12% to RM48.56 million, mainly due to weaker egg selling prices in Peninsular Malaysia and Vietnam, and the absence of egg subsidies in Malaysia.
Meanwhile, its convenience store chain segment, which operates FamilyMart outlets, continues to face a more challenging operating environment, with profit before tax more than halving for the quarter.
Its executive director Chia Lik Khai sees subdued consumer sentiment as confidence continued to weigh on sales growth, while margins are expected to remain under pressure in the short to medium term due to higher wages, rental, transportation and sales and service tax-related costs.
The convenience-store chain’s revenue fell 1% y-o-y to RM326.55 million in 1QFY2027, while PBT dropped 54% to RM8.78 million. Softer consumer spending, market competition and higher operating costs weighed on the segment’s profitability.
Despite the weak sentiment, QL Resources plans to accelerate its store expansion, targeting about 60 new stores opening in FY2027 compared with 45 stores opened in the previous financial year. As at FY2026, the group had 490 FamilyMart stores.
Lik Khai said the group believes Malaysia’s convenience-store market has yet to reach saturation, although it will remain selective on locations for new stores.
Separately, the El Niño weather is also expected to benefit QL Resources’ palm oil and marine products businesses, with management expecting crude palm oil (CPO) prices to remain elevated and warmer weather conditions supporting productivity at its fishery segment.
Meanwhile, QL Resources is set to begin construction of its RM1.3 billion QL Innofood Park in Hutan Melintang, Perak later this year. The integrated food manufacturing hub, which will be developed in phases over the next 10 years, will produce a range of processed food products, including surimi-based products such as imitation crab sticks and fish balls, as well as chicken and flour-based products. It is expected to add 130,000 metric tons (MT) of annual production capacity upon completion.
Its existing plant in Hutan Melintang has an annual capacity of 50,000 MT for surimi-based products, and is currently running at full capacity. In addition, its Johor plant has an annual capacity of 20,000 MT for surimi-based products and flour-based products such as frozen buns and mantou.
On Wednesday, QL Resources reported a flat 1QFY2027, with net profit edging up to RM100.76 million from RM100.60 million a year earlier as costs grew faster than revenue. Revenue rose 7.8% to RM1.85 billion, driven by stronger marine products and livestock farming businesses. The marine products segment was the key performer, with pre-tax profit jumping 52% due to higher production and selling prices, offsetting weaker performance in other segments.
The company’s share price was down 1.5% to RM3.94 a share on Thursday, valuing the company at RM14.38 billion.