

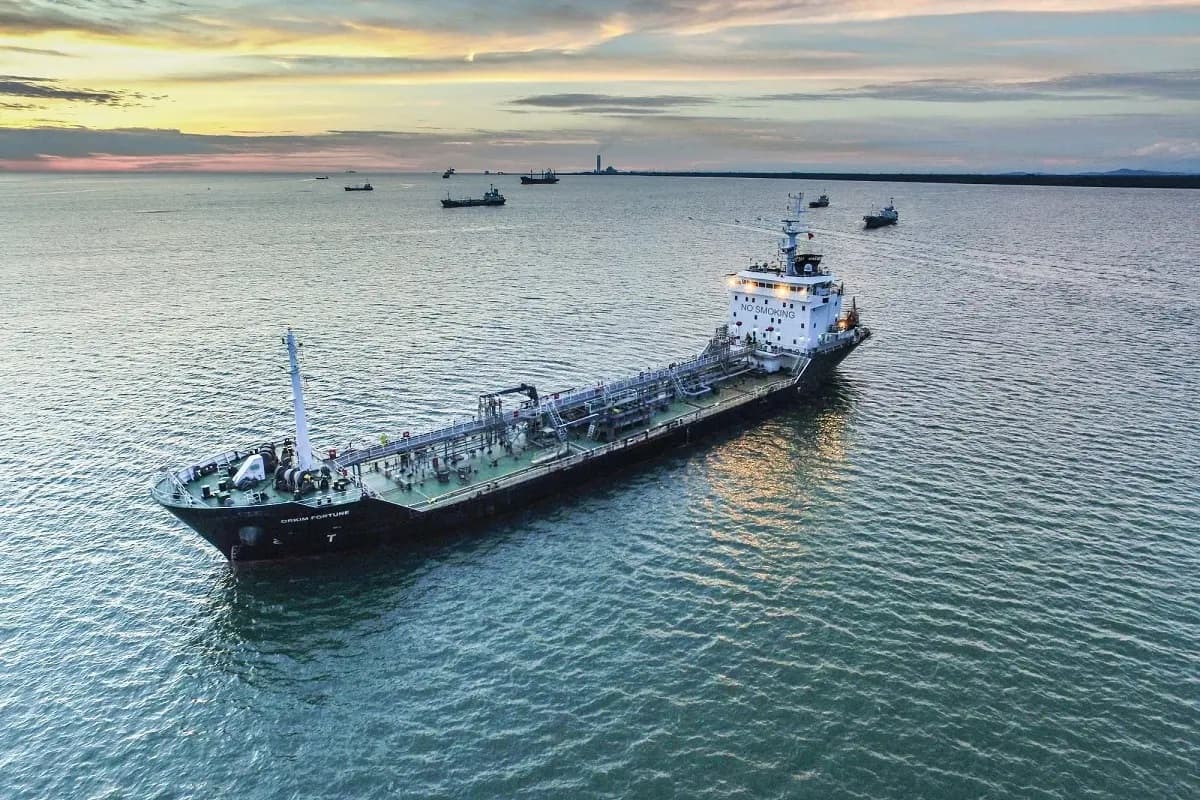
KUALA LUMPUR (Aug 24): Orkim Bhd (KL:ORKIM), the country's largest clean petroleum product (CPP) tanker operator, posted a net profit of RM22.91 million for the second quarter as fleet utilisation remained stable at about 91%.
Revenue for the quarter ended June 30, 2026 (2QFY2026), came in at RM87.34 million, with the company recording a gross profit margin of about 32%, according to its filing with Bursa Malaysia on Monday.
Orkim did not provide a year-on-year comparison because the company only listed on the Main Market in December last year.
Compared with the immediately preceding quarter, revenue was little changed from RM88.03 million, while net profit declined from RM24.11 million.
Fleet utilisation remained broadly stable at 91%, compared with 92% in 1QFY2026.
Orkim's core business is marine transportation of CPP and liquefied petroleum gas (LPG), mainly through chartering arrangements with oil majors and petroleum-product owners. As at end-June, the company owned and operated 19 vessels, comprising 17 CPP and chemical-capable tankers and two LPG carriers, compared with 18 vessels at end-2025.
The increase followed the delivery in May of Orkim Garnet, a 2026-built IMO Type II tanker capable of carrying both CPP and chemical products. The acquisition increased Orkim's total carrying capacity to 253,036 deadweight tonnes.
No dividend was declared for the quarter.
For the first half of FY2026, Orkim recorded revenue of RM175.4 million, up 14.9% from RM152.7 million a year earlier. Pre-tax profit increased 5.8% to RM47.1 million from RM44.5 million, while overall fleet utilisation remained at about 91%, compared with 92% previously.
The CPP segment remained the group's key earnings driver, with revenue rising 17.2% to RM164.2 million, mainly due to additional fleet capacity. The segment PBT increased 10% to about RM45.6 million, as contributions from the enlarged fleet more than offset higher depreciation and amortisation charges from additional vessels and higher finance costs.
The LPG business, however, recorded weaker performance as its revenue fell 11.4% to RM11.1 million, while PBT dropped 51.3% to about RM1.5 million. Orkim attributed the decline mainly to the scheduled dry-docking of one LPG vessel and the strengthening of the ringgit against the US dollar.
Looking ahead, Orkim said it remains optimistic about the rest of FY2026, supported by existing charter arrangements and continued demand for CPP and LPG marine transportation in its core markets.
"The group's fleet is largely deployed under time charter, consecutive voyage charter and contract of affreightment arrangements, which provide a degree of revenue and earnings visibility," it said.
Orkim said its concentration on Malaysia and nearby regional markets also limits its direct exposure to disruptions affecting long-haul international shipping routes. Nevertheless, the company said it continues to monitor geopolitical tensions and developments along major global shipping lanes.
Orkim raises RM100 mil from sukuk
Separately on Monday, Orkim said it has issued RM100 million in nominal value under its existing RM1 billion Sukuk Wakalah Bi Al-Istithmar Programme. The seven-year Series 2, Tranche 1 sukuk carries a periodic distribution rate of 4.20% per annum and is scheduled to mature on Aug 24, 2033.
The proceeds from the Series 2 sukuk will be used to finance the company's acquisition of future assets, finance working capital requirements, and defray fees, costs and expenses in relation to the sukuk programme.
Affin Hwang Investment Bank Bhd is the sole lead manager for the issuance.
Shares of Orkim closed half a sen or 0.6% lower at 86 sen on Monday, valuing the company at RM865 million. The stock is trading below its IPO price of 92 sen. Orkim made its Main Market debut on Dec 9, 2025.