

This article first appeared in The Edge Malaysia Weekly on August 17, 2026 - August 23, 2026
AJINOMOTO Co Inc, the parent of Ajinomoto (Malaysia) Bhd (KL:AJI), has defended its RM20 per share offer price for Ajinomoto Malaysia Bhd, saying it represents a reasonable premium and reflects the company’s business value and historical share performance.
In response to The Edge article headlined “‘Lowball’ offer raises questions about Ajinomoto’s privatisation”, Ajinomoto said Ajinomoto Malaysia should be valued based on its own historical valuation rather than that of other consumer goods companies such as Nestlé Malaysia Bhd (KL:NESTLE), which has a higher valuation multiple due to its larger scale and stronger market position.
“While we recognise that there are different views regarding appropriate enterprise value to earnings before interest, taxes, depreciation and amortisation (EV/Ebitda) multiples for consumer goods companies, we believe that valuation assessments should consider not only industry classifications but also company-specific factors such as business scale, growth prospects, profitability, financial strength and share liquidity,” it says in an Aug 13 letter to the Ajinomoto Malaysia board.
Ajinomoto said Ajinomoto Malaysia’s average EV/Ebitda multiple in the year before the proposed selective capital reduction (SCR) announcement was 4.26 times while the RM20 offer implies a multiple of 8.05 times or about 89% higher.
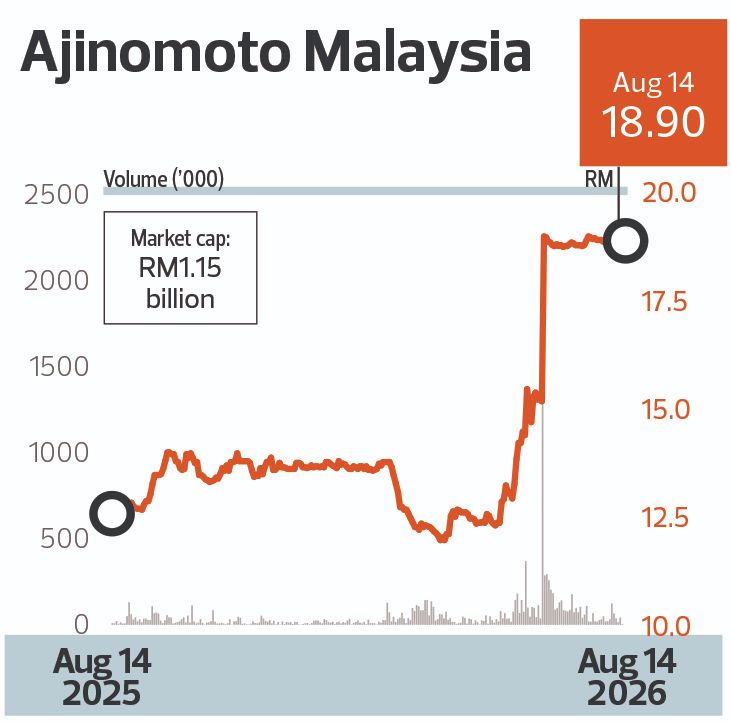
It said comparing Ajinomoto Malaysia with Nestlé Malaysia using EV/Ebitda multiples was inappropriate because Nestlé is much larger, has a stronger market position, more stable earnings and a higher market capitalisation. Ajinomoto said Ajinomoto Malaysia’s own historical valuation was therefore a more relevant benchmark.
Ajinomoto also disputed an independent analyst’s RM26.20 valuation for Ajinomoto Malaysia, saying the comparison companies used in the report were not suitable benchmarks.
It said comparing Ajinomoto Malaysia’s implied 16.9 times price to earnings ratio (PER) at the RM20 offer price with its own 44.4 times PER was inappropriate because the two companies differ significantly in scale, business mix, earnings and growth prospects.
Ajinomoto is a much larger global food and biotechnology company with a growing semiconductor-related business that supports its higher valuation. By comparison, Ajinomoto Malaysia is mainly a Malaysian seasoning manufacturer with a market capitalisation that is less than 1% of Ajinomoto’s.
Ajinomoto said the analyst’s 18 to 25 times PER valuation range was not appropriate because the four companies used for comparison were much larger and more diversified than Ajinomoto Malaysia. It noted that Ajinomoto Malaysia’s average PER in the year before the SCR announcement was 11.35 times, significantly below the analyst’s range.
Ajinomoto maintained that the RM20 offer provides shareholders with a meaningful premium and is not an attempt to acquire Ajinomoto Malaysia at an unfairly low price. Ajinomoto owns a 50.376% interest in Ajinomoto Malaysia.
Ajinomoto Malaysia is due to convene a shareholders’ meeting to vote on the proposed SCR. For the deal to go through, 75% of the 30.17 million units of minority shareholder shares must vote for it, with not more than 10% of the minority shareholders voting against it.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.