

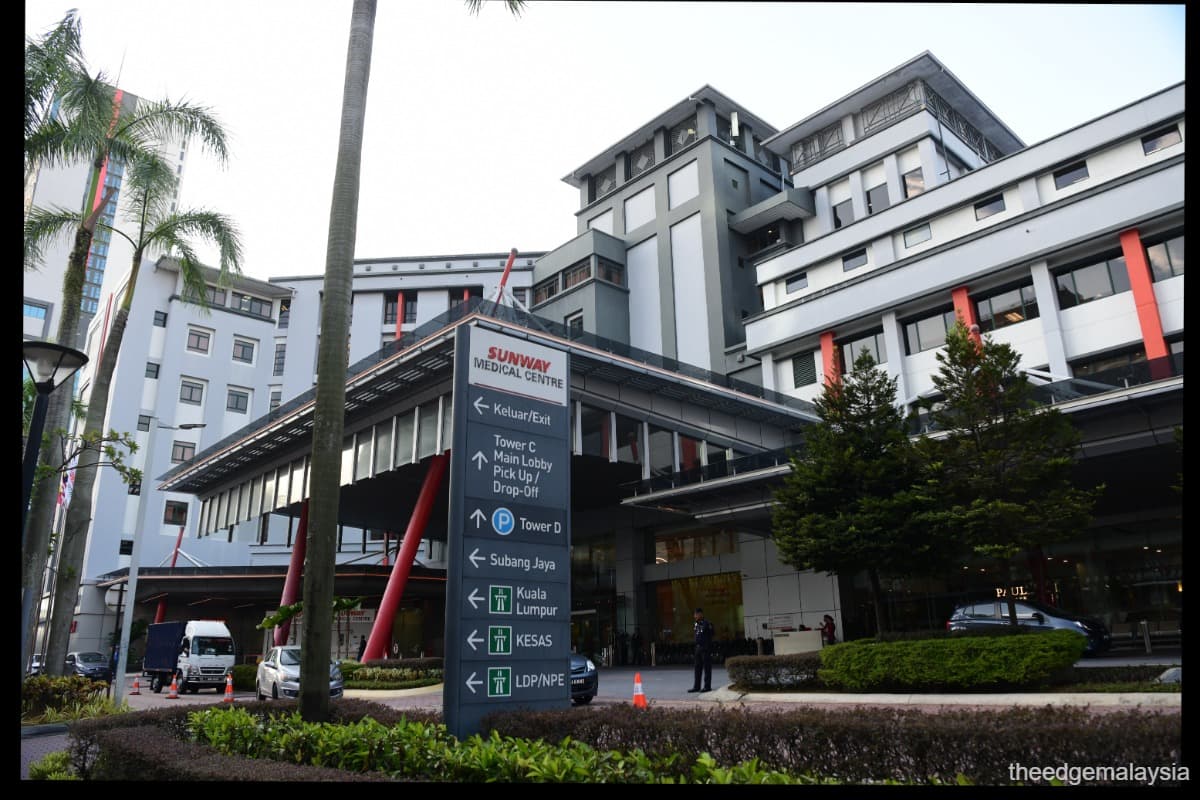
KUALA LUMPUR (Aug 21): Analysts stay upbeat on Sunway Healthcare Holdings Bhd (KL:SUNMED) despite its stretched valuation, as the group’s business fundamentals and earnings potential remain positive.
Kenanga Research on Friday said after a recent rally, Sunway Healthcare has run ahead of its valuation.
"We downgrade our call from 'market perform' to 'underperform'. The stock trades at 29 times EV/Ebitda (enterprise value over earnings before income tax, depreciation and amortisation), exceeding Indian peers’ 27 times despite their stronger growth," it said in a note.
Nonetheless, Kenanga raised Sunway Healthcare's financial year ending Dec 31, 2026 (FY2026) net profit forecast after increasing its average revenue per inpatient and Ebitda margin assumptions from 24% to 25%, while maintaining its FY2027 forecasts.
Separately, Hong Leong Investment said the recent share price rise has narrowed the stock's upside potential, and reiterated its 'hold' call on Sunway Healthcare with an unchanged target price of RM2.05, based on an unchanged 30 times FY2027 EV/Ebitda valuation multiple.
"Going into 2HFY2026, we expect the earnings momentum to strengthen sequentially, supported by seasonality — particularly in 4QFY2026, which typically delivers a higher Ebitda margin, potentially due to a more favourable mix of elective surgeries — as well as favourable operating leverage at SMC (Sunway Medical Centre) Penang, alongside with incremental contributions from SMC Damansara and SMC Ipoh," it said in a note on Friday.
Meanwhile, CIMB Securities maintained its 'hold' call and raised Sunway Healthcare’s target price to RM2.10, basing it on the expectation that the healthcare provider’s lower free float could command a scarcity premium.
"Sunway Healthcare’s premium valuation over its peers is supported by its: i) robust earnings growth outlook; ii) stronger margin profile; and iii) aggressive brownfield expansion strategy. Nonetheless, we believe Sunway Healthcare’s current valuation has largely factored in its future earnings upside," it said in a note on Friday.
CIMB Securities also noted that Sunway Healthcare's prevailing EV/Ebitda multiple of 30 times appears fair, as it represents a 16% premium to India-listed peers with comparable three-year earnings growth outlooks.
Meanwhile, Sunway Healthcare’s latest financial report shows its 1HFY2026 net profit coming in at RM125 million, representing a 46% year-on-year growth, which is broadly in line with the consensus expectations.
The strong earnings are supported by an improved case mix and better margins in SMC Damansara and SMC Ipoh, the group’s two newest hospitals.
Analysts have praised the healthcare provider for its ability to ramp up new hospitals quickly and achieve break-even in under 12 months compared to the industry’s norm of three to five years. The two newest hospitals are expected to follow the same rapid ramp-up trajectory.
The corporation’s ability to shorten its gestation period allows capital to be recycled faster, enabling the group to expand without the multi-year earnings drag typical of the industry.
Following a strong first half, analysts expect earnings to strengthen in the second half of the year, driven by higher patient volume and increased average revenue per patient, underpinned by medical tourism, higher complexity cases and bed capacity expansions.
CIMB Securities noted that beyond 2028, Sunway Healthcare plans to pursue greenfield expansions, adding over 400 beds across new developments in Seremban Sentral, Iskandar, and Putrajaya.
Medical tourism-derived margins are also expected to rise, backed by strong contributions from Cambodian and Chinese patients, although Indonesian footfall has declined due to the sharp depreciation of the Indonesian rupiah.
CIMB Securities noted that Sunway Healthcare is focused on broadening its referral and payer networks, and diversifying its patient source countries to reduce dependency on any single geography and support sustainable long-term growth in medical tourism.
Furthermore, the healthcare giant is expected to benefit from additional investment tax allowances resulting from qualifying capital expenditure spent to promote medical tourism.
Overall, CIMB Securities raised its core net profit estimates by 4% for FY2026, and by 3% for FY2027 and FY2028, after incorporating lower effective tax rate assumptions per management guidance.
As of Aug 21, the healthcare giant commands four 'buy' ratings, 12 'hold', and one 'reduce' call.