

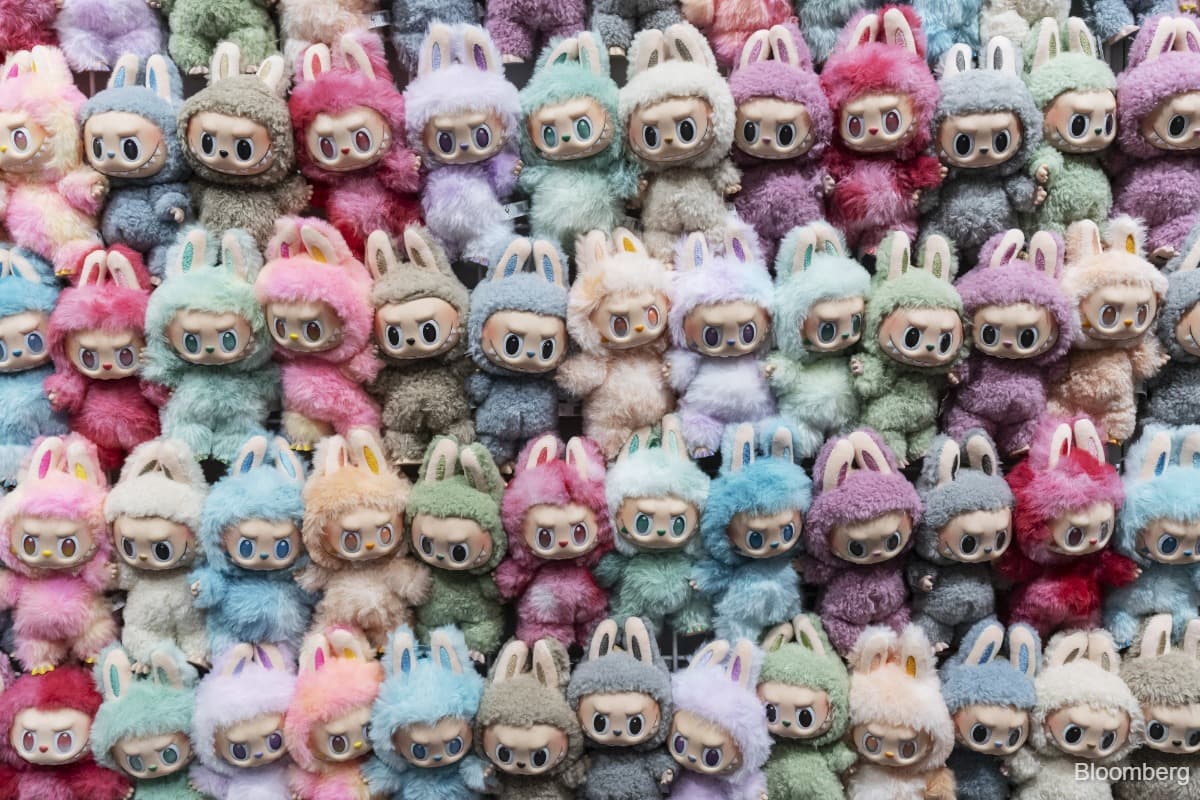
(Aug 20): Pop Mart International Group Ltd reported a sharp slowdown in first-half (1H) sales growth, with demand for its blockbuster Labubu toys cooling after last year’s explosive surge.
Revenue increased 24% to 17.2 billion yuan (RM10.36 billion) in the six months ended June, compared with a consensus estimate of 20 billion yuan. That marks a steep drop from the more than 200% growth recorded a year earlier. Net income was 5.04 billion yuan, coming in lower than the forecast of 6.6 billion yuan.
The 1H numbers highlight Pop Mart’s challenges in expanding beyond a single blockbuster character and building a durable entertainment franchise. They also reflect a broader trend of how once-viral Chinese consumer brands — from jeweller Laopu Gold Co to tea chain Chagee Holdings Ltd — that enjoyed rapid growth are finding it harder to sustain momentum as shoppers grow more selective and economic pressures hit discretionary spending.
Some Chinese labels “have achieved much success through social virality and scarcity, but that attracts trend-driven consumers chasing novelty, not loyalty”, said Olivia Plotnick, founder of Shanghai-based marketing consultancy Wai Social. “Once the conversation moves on, so do they.”

Pop Mart’s Hong Kong-listed shares have been largely flat since first-quarter results triggered a record selloff and now trade at less than half their peak about a year ago. Bearish bets are growing that the stock is still over-valued: nearly a quarter of Pop Mart’s shares on the open market are being shorted, according to S3 Partners, which analyses short positioning data.
While the US remains central to Pop Mart’s expansion, its home market in China provides a more established base of members and stores. Pop Mart has more than 80 stores in the US and plans to exceed 100 by year-end, compared with more than 400 in mainland China. Revenue in Mainland China, Hong Kong, Macau and Taiwan rose 47%. Overseas sales declined 11% year-on-year.
“We think the domestic market is still crucial for Pop Mart as it accounts for more than half of total revenue,” Morningstar Inc analyst Jeff Zhang said ahead of the results. He expects double-digit annual domestic growth over the next five years, supported by rising membership and repeat purchases.
Pop Mart is trying to inspire loyalty by building its characters into broader entertainment franchises. A Labubu movie is in the works with Sony Pictures, and physical experiences including Beijing’s Pop Land theme park and a Pop Bakery concept that recently opened in Singapore are being expanded. A collaboration between its dreamy Dimoo character and the Walt Disney Co’s Pixar was also well received by collectors.
But the company has a way to go before it becomes an intellectual property powerhouse like Disney or Hello Kitty owner Sanrio Co, whose characters have decades of stories and generational recognition behind them.
Recent data point to weakening demand, with online sales in China down 21% year-on-year in July after a 41% drop in June, according to Deutsche Bank research notes citing third-party data. If the weakness persists, the company faces mounting domestic sales pressure, the bank said.
Going forward investors will be looking for signs of re-acceleration in revenue and earnings, especially abroad, said James Ooi, a market strategist at Tiger Brokers. A larger dividend payout could also help restore confidence, he said.
“The bigger lesson is that emotional consumption is highly volatile,” Ooi said. “Sustaining growth requires repeat purchases and a strong pipeline of new IPs, rather than reliance on one blockbuster character.”
Uploaded by Felyx Teoh