

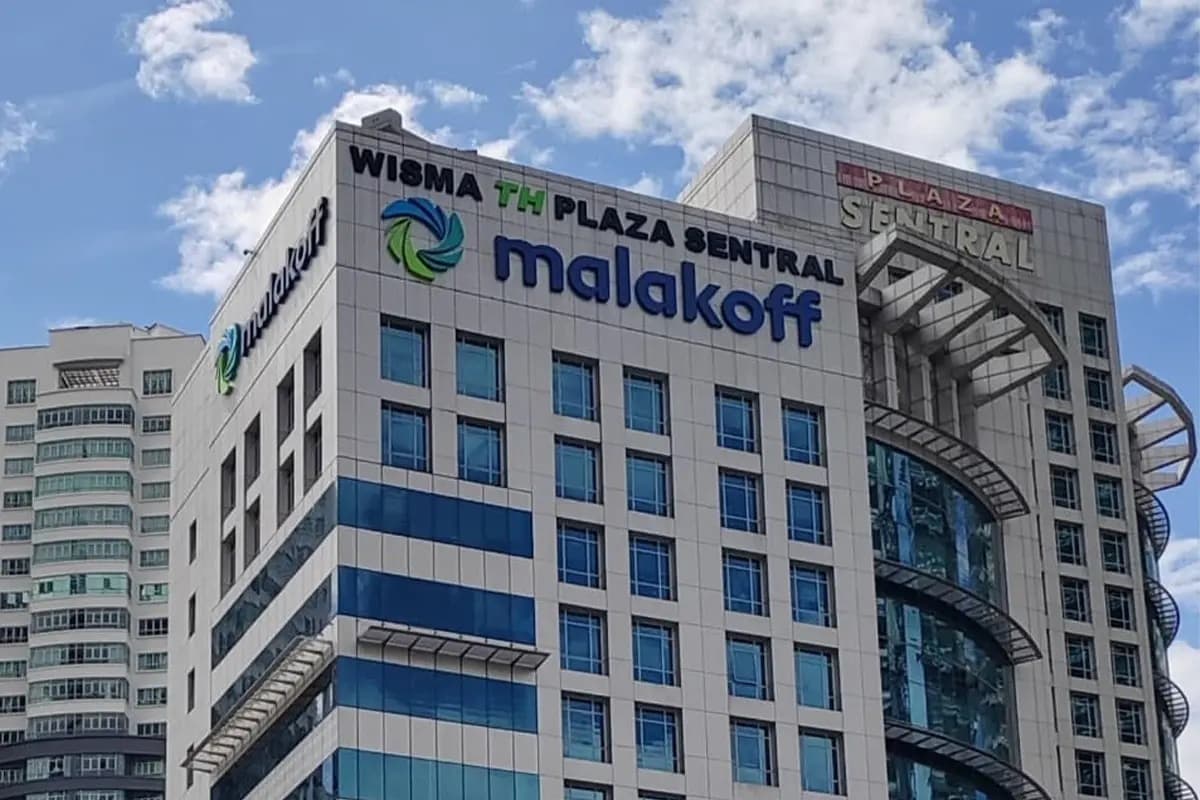
KUALA LUMPUR (Aug 18): Malakoff Corp Bhd’s (KL:MALAKOF) performance is expected to pick up in the second half of the year, after equipment failures and higher-than-average tax rates led to a softer first half, analysts said.
RHB Research said Malakoff Corp’s first half ended June 30, 2026 (1HFY2026) earnings came in below expectation at 30% of its full-year estimate.
“However, its performance met the consensus projection, at 46% of the full-year figure,” it said in a note on Tuesday.
Malakoff saw flat quarter-on-quarter (q-o-q) growth in 2QFY2026, raking in a total of RM32 million in earnings.
Meanwhile, revenue increased by 39% q-o-q, mainly due to improved fuel margins recorded at Tanjung Bin Energy (TBE) and Tanjung Bin Power (TBP).

The research house attributed weaker earnings to a steam turbine generator rotor failure in a 2,100MW coal-fired power plant in Johor, which was owned by TBP. This led to a topline decline of 19% year-on-year for the group.
Meanwhile, Malakoff reported a high effective tax rate (ETR) of 51% in the second quarter, which resulted in an average 40% ETR for the first half (vs 21% a year earlier).
“The higher tax rate was due to expenses that were non-tax deductible.”
RHB expects Malakoff’s performance to pick up in the second half, as TBP earnings should improve since the rotor resumed operating this month.
“Separately, the conveyor belts at the Tanjung Bin jetty resumed operations in June, with the complete removal of debris onsite.
“We make no changes to FY2026-2028F EPS (earnings per share), as we await further guidance from management at the company’s analyst briefing on Aug 18,” it said.
RHB maintained its ‘buy’ call on the stock and an unchanged target price of RM1.06.
In a separate note, CIMB Securities cut its FY2026 core net profit (CNP) forecast by 16% and its FY2027 and FY2028 forecasts by 1% each, with potential upside risks being new large-scale solar power plant projects.
"We expect CNP to fully recover (+97% year-on-year) in FY2027F, and then ease 10% year-on-year in FY2028F on reduced energy income margin and the expiry of AlHidd’s concession in May 2028, partly offset by the start of power purchase agreements for new solar projects," said the house.
After factoring in the earnings cut, CIMB reduced its target price for Malakoff by 8% to 92 sen, maintaining its ‘hold’ rating.