

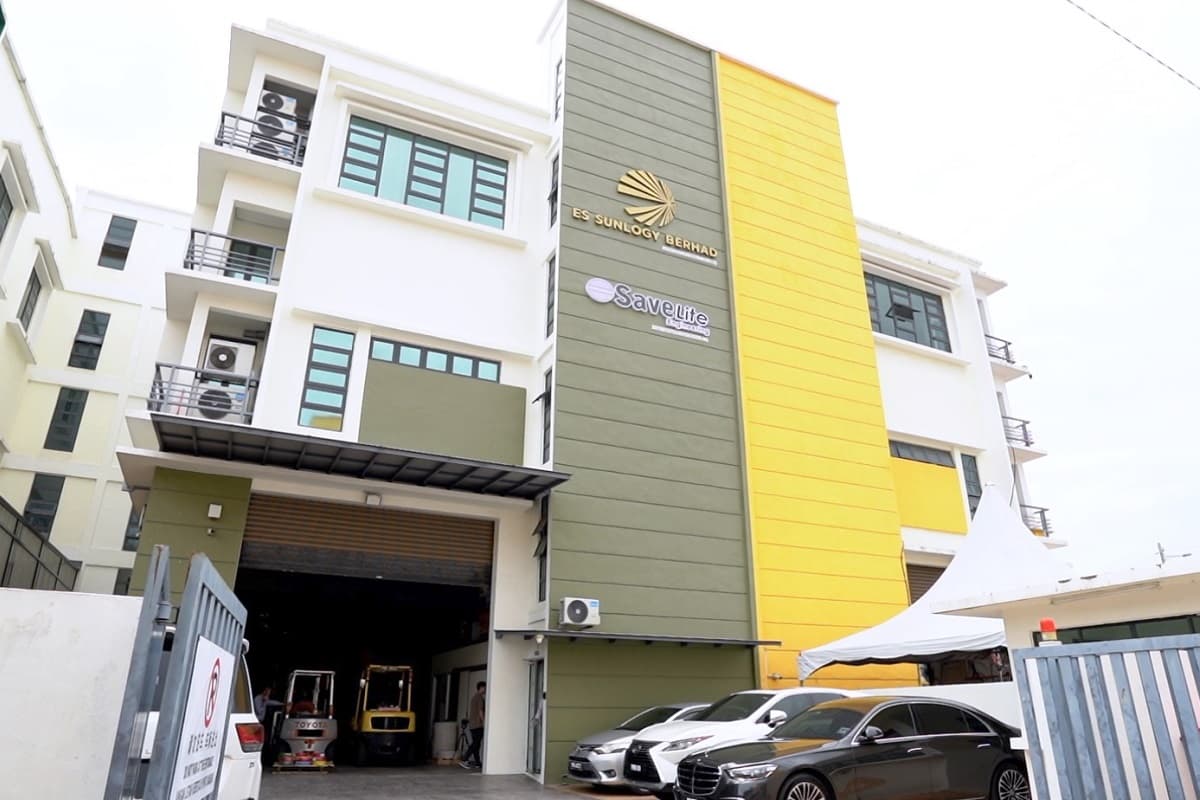
KUALA LUMPUR (Aug 17): ES Sunlogy Bhd's (KL:SUNLOGY) shares hit a year-high on Monday after Kerjaya Prospek Group Bhd (KL:KERJAYA) raised its stake in the company further to 31%.
Sunlogy shares gained as much as three sen, or 7.5%, to an intraday high of 43 sen, before paring gains to close at 42.5 sen, with a market capitalisation of RM327.25 million. Meanwhile, Kerjaya Prospek edged up one sen, or 0.37%, to close at RM2.74, valuing the group at RM3.47 billion.
Kerjaya recently raised its stake in the mechanical and electrical (M&E) engineering and renewable energy firm to 31% from 28.27% following two acquisitions.
After becoming Sunlogy’s largest shareholder last Friday with a 28.27% stake purchased for RM40.18 million, Kerjaya Prospek disclosed on Monday that it had acquired another 2.73% stake (21 million shares) for RM5.36 million, averaging 25.54 sen per share, off market.

TA Securities said in a note the acquisition of an additional stake in Sunlogy by Kerjaya Prospek presents an opportunity for greater exposure to higher-value M&E opportunities.
This comes after the group acquired an initial 9.09% stake in the M&E engineering contractor for RM18.76 million cash in July.
TA Securities views the investment positively as it recognises meaningful long-term synergies between the two businesses, with Kerjaya Prospek’s core construction capabilities complementing Sunlogy’s M&E engineering and renewable energy expertise.
Reflecting this, the house maintained its ‘buy’ call and raised its target price to RM3.63.
In a separate note, PhillipCapital reported that Sunlogy is supported by a RM328 million order book and sizeable RM4.7 billion tender pipeline.
Based on Sunlogy’s audited core net profit of RM15 million for 2025, the stake acquisition is estimated to boost Kerjaya Prospek’s earnings by 1% to 2%.
“Separately, we understand [Kerjaya Prospek] is likely to continue engaging Sunlogy for electrical works, building on their existing collaboration on the RM22 million Batu Kawan subcontract in January.”
Key downside risks identified by PhillipCapital include slower-than-expected order book replenishment, higher-than-expected raw material costs, unforeseen project delays, and a slowdown in the property market.
Phillip Capital kept its 'buy' call on the stock with a target price of RM3.16.