

KUALA LUMPUR (Aug 17): Affin Bank Bhd (KL:AFFIN) slipped to its lowest in eights after reporting a weaker-than-expected quarter and as analysts maintained caution over asset quality.
Provisions at one of the smallest commercial lenders have remained elevated for two consecutive quarters now, and investors would want to see clearer evidence that credit costs have peaked and asset quality is stabilising, CIMB Securities said and downgraded the stock to ‘hold’.
CIMB Securities also flagged weaker near-term return on equity (ROE) and delayed earnings recovery. “Valuation now requires proof of ROE delivery rather than execution potential alone,” the house noted.
Shares of Affin fell as much as three sen or over 1% to RM2.20, their lowest since December 2025. The stock closed at RM2.21 as more than three million shares exchanged hands on Monday.
The stock now has eight ‘hold’ and only two ‘buy’ calls out of 10 recommendations tracked by Bloomberg. The average target price is now RM2.46.
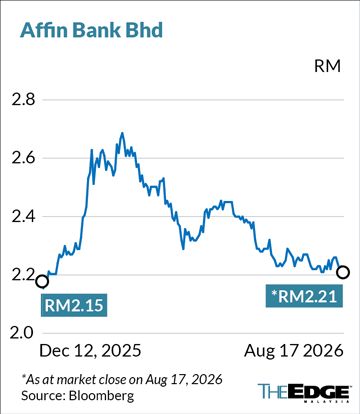
Affin has lost nearly 18% of its value from this year’s peak and is now worth under RM6 billion amid concerns over rising allowance for bad debts. While Malaysian banks have little to no exposure to the Middle East, supply chain disruption and spike in costs may affect borrowers’ ability to repay.
Competition for deposits has also remained fierce in the country where more than two dozen local and foreign commercial banks jostle for business.
Near-term pressure from intense deposit competition remains a key risk to net interest margins, a measure of profitability from interests charged on loans after deducting returns paid to depositors, said Hong Leong Investment Bank in a separate note.
“Without stronger near-term rerating catalysts, we opine that potential provisioning upticks are likely to cloud the earnings outlook over the next two to three quarters,” the house cautioned.