

This article first appeared in The Edge Malaysia Weekly on August 10, 2026 - August 16, 2026
HARTALEGA Holdings Bhd (KL:HARTA) recently reported an almost sixfold jump in net profit for the first quarter ended June 30, 2026 (1QFY2027), as higher glove average selling prices (ASPs) lifted margins.
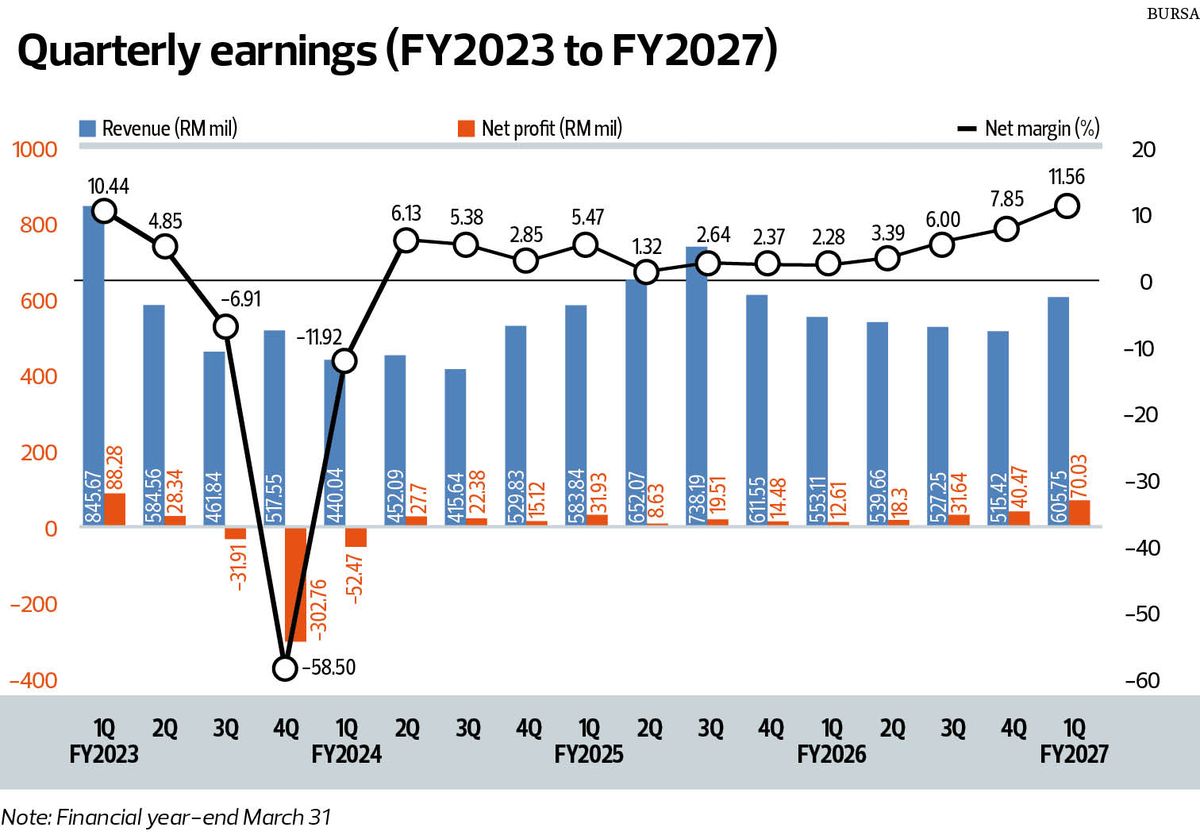
The glove maker’s net profits for the quarter totalled RM70.03 million, versus RM12.61 million in 1QFY2026. Revenue rose 9.5% year on year to RM605.75 million. It was the highest quarterly earnings since 1QFY2023, when it reported net profit of RM88.3 million on revenue of RM845.7 million.
The earnings jump was not entirely unexpected, however, as the market had anticipated the impact of disruptions in the Strait of Hormuz amid the Middle East conflict. The resulting supply concerns pushed raw material prices, particularly butadiene, higher, allowing glove makers to adjust their ASPs upwards.
This recent surge in y-o-y net profit may, however, be as good as it gets for Hartalega in the near term.
On the one hand, according to Kenanga Research, its ASP is expected to correct sharply in the coming months after peaking in May as glove pricing normalises on lower raw material costs.
“Moving into 2QFY2027, it (Hartalega) has guided that nitrile ASP will taper off from US$26 to US$28, to US$19 to US$20 per 1,000 pieces. On-the-ground checks suggest that ASP has retreated from US$28 in May to US$21 to US$22 per 1,000 pieces in July and could go lower to US$18 to US$19 per 1,000 pieces in August,” says the research house in a report dated Aug 5.
Kenanga Research has a target price of RM1.14 on Hartalega and maintained its “market perform” call.
On the other hand, analysts expect margin compression in 2QFY2027, as Hartalega will be using high-priced nitrile raw material shipments booked for the quarter, which is likely to weigh on earnings.
Management had already cautioned, however, that 2QFY2027 earnings was likely to come in below 4QFY2026 net profit, according to Kenanga Research. Hartalega reported a net profit of RM40.47 million on revenue of RM515.42 million in 4QFY2026.
Even as 2QFY2027 net profit is likely to be disappointing after the windfall in the first quarter, there could be a modest rebound in 3QFY2027, as Hartalega intends to raise its ASP later in the year to mitigate higher gas prices.
Public Invest Research says in a report that while the upcoming ASP will be increased by US$1.50 to US$2 per 1,000 pieces, Hartalega’s management acknowledged that pricing power remains constrained by market competition.
“Malaysian producers are currently estimated to command a price premium of US$1.50 to US$2 per 1,000 pieces over Indonesian and Vietnamese peers (where China glove makers have expanded capacity), suggesting limited scope for further price differentiation,” says Public Invest.
While the research house remains positive on Hartalega’s structural cost improvements and capacity expansion, it believes the exceptional profitability achieved in 1QFY2027 is unlikely to be replicated.
Public Invest has a “neutral” call on the stock, with a target price of 98 sen.
Hartalega has also said it is on track to recommission Plant 3 by end-2026. Plant 3 houses six production lines with an annual capacity of four billion gloves.
CIMB Securities highlights that the move is expected to increase Hartalega’s total annual production capacity by 14% to 15% to between 30 billion and 32 billion pieces, from between 26 billion and 28 billion pieces previously.
There are also plans to recommission Plant 4, which is similarly capable of producing four billion gloves annually, by end-2027.
When combined, it will bring the group’s total annual production capacity to about 36 billion pieces by FY2028.
CIMB Securities believes earnings could rebound in the longer term, as Hartalega plans to raise ASPs later this year to pass on higher costs.
“In the long run, this will help ease the impact of the margin squeeze driven by competition-induced ASP deflation and higher input costs,” notes the research house.
It lowered its target price to RM1.12 and kept its “hold” call on the stock, saying that the weaker earnings outlook has already been priced into the stock.
Notably, MBSB Research is among the few research houses that raised their target prices for Hartalega. It lifted its target price to RM1.73 from RM1.24 previously, based on a 25 times PER applied to its revised FY2027 EPS of 6.9 sen.
“We believe Hartalega would retain its premium over sector peers (the industry’s PER stands at 18 to 24 times), owing to improved operational efficiencies and its net cash position,” says MBSB Research.
As at June 30, Hartalega’s net cash stood at RM1.11 billion. The counter closed at 99.5 sen last Thursday, valuing the company at RM3.4 billion.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.