

This article first appeared in Digital Edge, The Edge Malaysia Weekly on August 10, 2026 - August 16, 2026
Payments Network Malaysia Sdn Bhd (PayNet) is preparing to launch the Open Finance Malaysia (OFM) framework, a major structural shift overseen directly by Bank Negara Malaysia. The company has already deployed its Open Finance Developer Portal, setting the stage for a live ecosystem pilot scheduled for the second half of 2026 (2H2026).
OFM marks a transition from a closed data security model to a secure, consent-driven financial data-sharing framework. Historically, legacy banking institutions viewed their consumer transactional data as a competitive moat.
The framework dismantles this paradigm by mandating that, upon customer consent, financial data must be securely shareable via standardised application programming interfaces (APIs) to authorised third-party service providers and fintech applications.
To ensure an ordered rollout, PayNet’s upcoming 2H2026 pilot community will comprise seven commercial banks alongside the Employees Provident Fund (EPF).
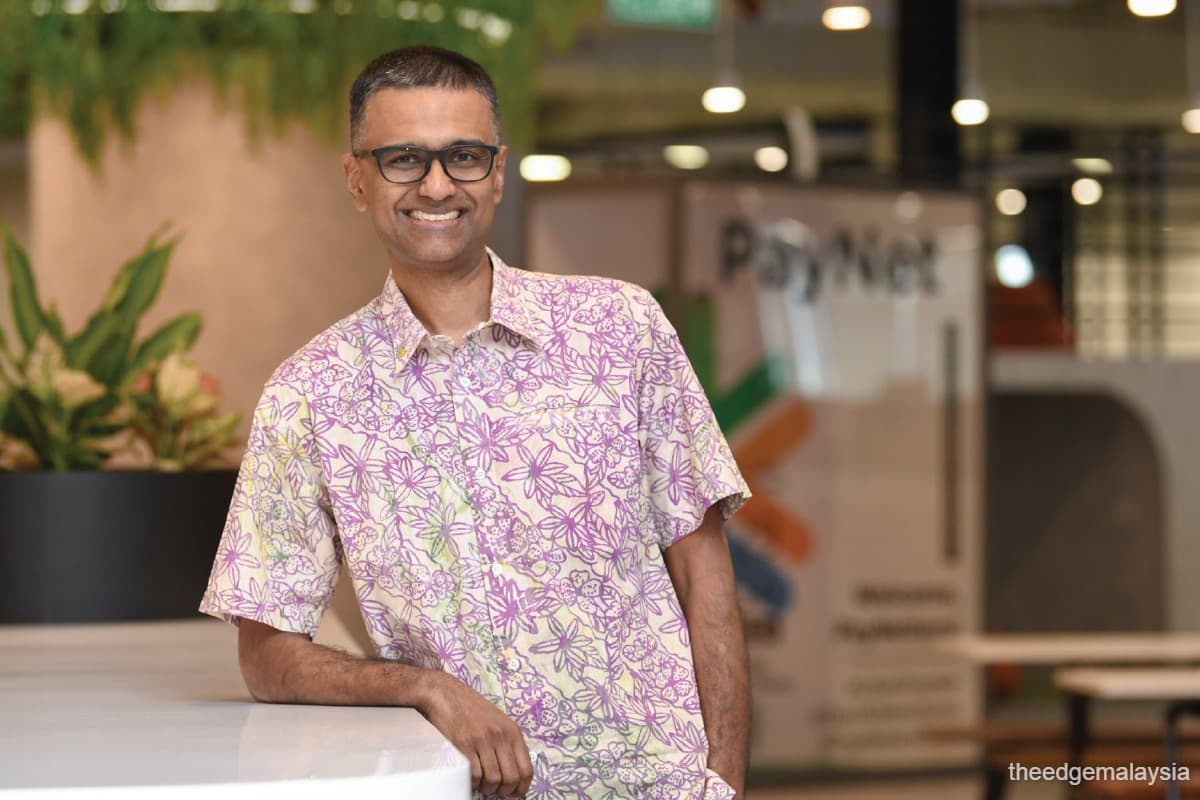
“The fundamental business case for the banks is highly compelling,” says PayNet CEO Praveen Rajan, who took the helm earlier this year.
“Consider a mid-tier commercial bank with a customer base of half a million users. Through Open Finance APIs, they can offer real-time, highly personalised credit financing or mortgage facilities. A consumer will no longer need to manually print, scan and submit months of physical salary slips or tax documents.
“Users can simply click a button within the bank’s secure application, grant explicit digital consent and allow the system to instantly verify their historical contributions directly from their EPF ledger. The consumer gets friction-free execution, and the bank instantly optimises its credit underwriting accuracy.”
Last November, just before Praveen joined PayNet as CEO designate on Dec 1, Bank Negara announced that it would be mandating banks to give consumers control over how their financial data — including deposit accounts, charge cards and credit cards — is shared, accessed and used.
According to the central bank’s proposed rules for open finance, major banks, development finance institutions and eligible e-money providers will begin sharing customer information — the last 12 months of transactions and current account balance — but only for customers who actively opt in.
Larger banks with more than one million customers will kick off the initiative from Jan 1, 2027, followed by those with 100,000 or more customers (Jan 2, 2028) and smaller institutions above certain thresholds (Jan 1, 2029). For all other players, joining is optional.
The key factor for long-term ecosystem success, says Praveen, is the unwavering rule of data reciprocity.
“The core principle we are adopting is strict: if you join our open ecosystem to consume financial data, you must be legally prepared to contribute your own data back into the network,” he explains.
“A fintech wallet, a major telecommunications operator or a government agency like the Road Transport Department cannot simply enter the ecosystem to harvest data without opening their own data nodes to reciprocal consumption. That is the only way to build a fair, sustainable data economy.”
Under this framework, PayNet does not aggregate, store or analyse consumer profiles. Praveen describes PayNet’s role as that of a secure digital directory.
“PayNet does not see or own the data. We simply verify the consent tokens, authenticate the security credentials of the requesting parties and safely route the encrypted payload from the data provider to the authorised consumer,” he says.
“We provide the secure, standardised infrastructure that makes financial innovation possible.”
Transition from telco to national digital payment systems
The launch of the OFM will be one of Praveen’s first undertakings since officially assuming the role of CEO on Feb 1.
After 18 years of climbing the corporate ladder in the telecommunications industry, most recently within the executive leadership of CelcomDigi Bhd (KL:CDB), he decided it was time for a new challenge.
Between 2017 and 2022, Praveen spearheaded telco-backed e-money issuance and served on PayNet’s own advisory committees, as the real-time retail payments platform road map was being designed.
“There are also commonalities between my previous experience and what I’m doing now at PayNet, which is around the impact to people. A lot of work around empowering societies, and that’s what really resonated with me when I made that decision to join PayNet.”
Unlike public-listed enterprises built to hunt for market share on a relentless, quarter-on-quarter cycle, PayNet operates under a different framework.
PayNet is majority-owned by Bank Negara (a 30%-plus stake) alongside a consortium of 11 commercial banks, and exists to deliver systemic stability, cost efficiency and nationwide inclusion.
“A publicly listed company is a different machine altogether. It is chasing quarter-on-quarter growth. But the transition to PayNet was deeply meaningful because I saw it as an infrastructure company that sits behind the scenes — almost entirely invisible to the public,” Praveen tells Digital Edge.
“Our agenda is not top-line revenue; it is about building the rails, ensuring they run sustainably and making sure our participants — the banks, the wallets, the financial institutions — can benefit the most to empower the people.”
Praveen clarifies this does not mean PayNet operates as a non-profit — it is a commercially-oriented organisation that must manage costs efficiently and generate enough internal revenue to fund its capital expenditure and stay self-sustaining.
“PayNet is highly unique. Open our technical documentation and half the time we are addressing highly complex architecture, APIs and clearing configurations.”
Praveen was hand-picked following a succession process announced in September 2025, and spent two months working alongside predecessor Farhan Ahmad.
Inheriting a well-structured multi-year road map, he felt no immediate pressure to reinvent PayNet’s core objectives.
“The focus has gravitated towards execution, relationship management and tuning internal operational culture to handle the immense systemic strains of a modern digital economy,” he says.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.