

This article first appeared in Capital, The Edge Malaysia Weekly on August 3, 2026 - August 9, 2026
Water infrastructure
Thematic play
MAYBANK INVESTMENT BANK RESEARCH (JULY 27): We believe Malaysia is entering a long-awaited water infrastructure capex upward cycle, supported by an expanding project pipeline, tariff reforms and structurally higher demand from data centres. Unlike previous cycles that failed to gain traction due to funding constraints, the current environment appears far more supportive, with stronger financing visibility and improved economics for water operators.
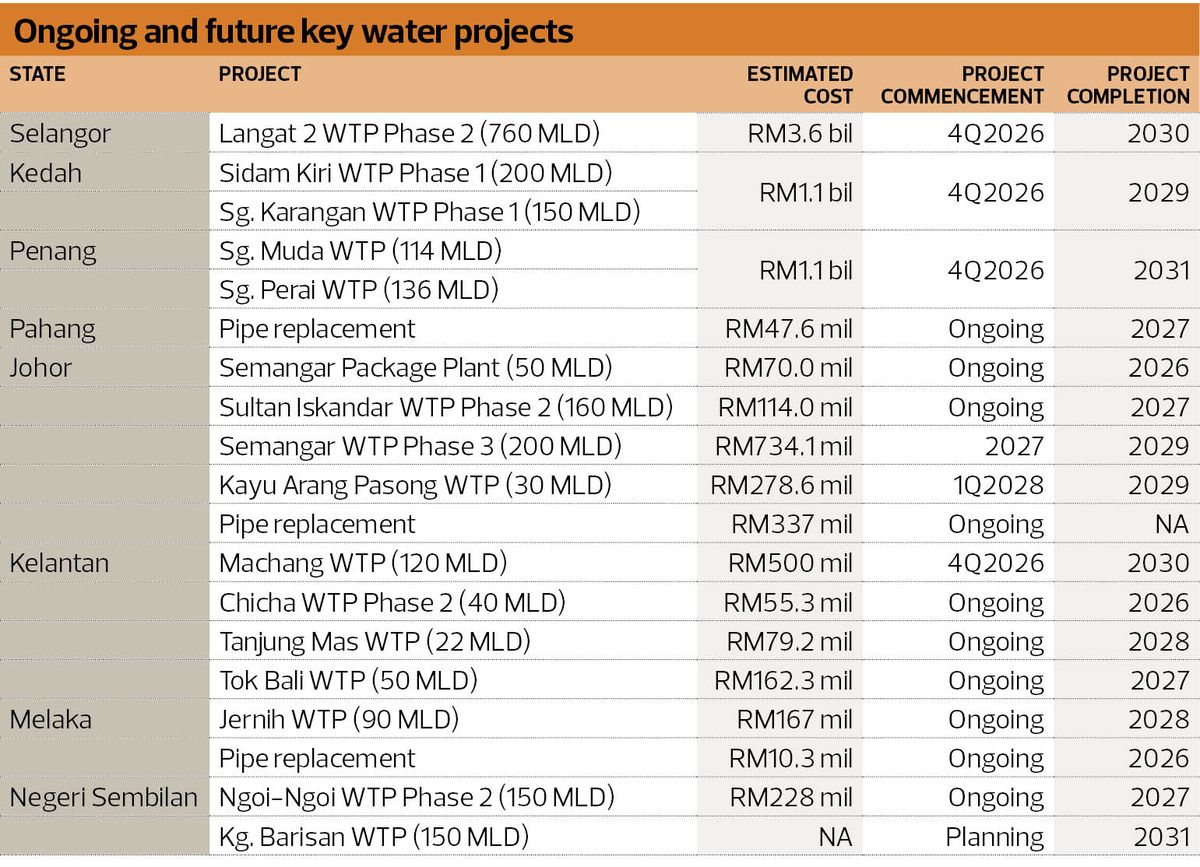
Planned investments exceed RM20 billion, including the RM6 billion Ulu Padas Water Supply Scheme in Sabah, the RM5 billion Northern Perak Water Supply Scheme and Pengurusan Aset Air Bhd’s (PAAB) RM3.7 billion Langat 2 Phase 2 Water Supply Scheme. More significantly, PAAB’s projects under design had expanded more than sixfold to RM12.0 billion in 2025 from RM1.9 billion in 2021, providing a strong leading indicator of future contract awards.
The pipeline is largely focused on constructing new water treatment plants, transmission infrastructure and replacing ageing water pipes, creating sizeable opportunities for listed contractors, pipe manufacturers and engineering companies over the coming years.
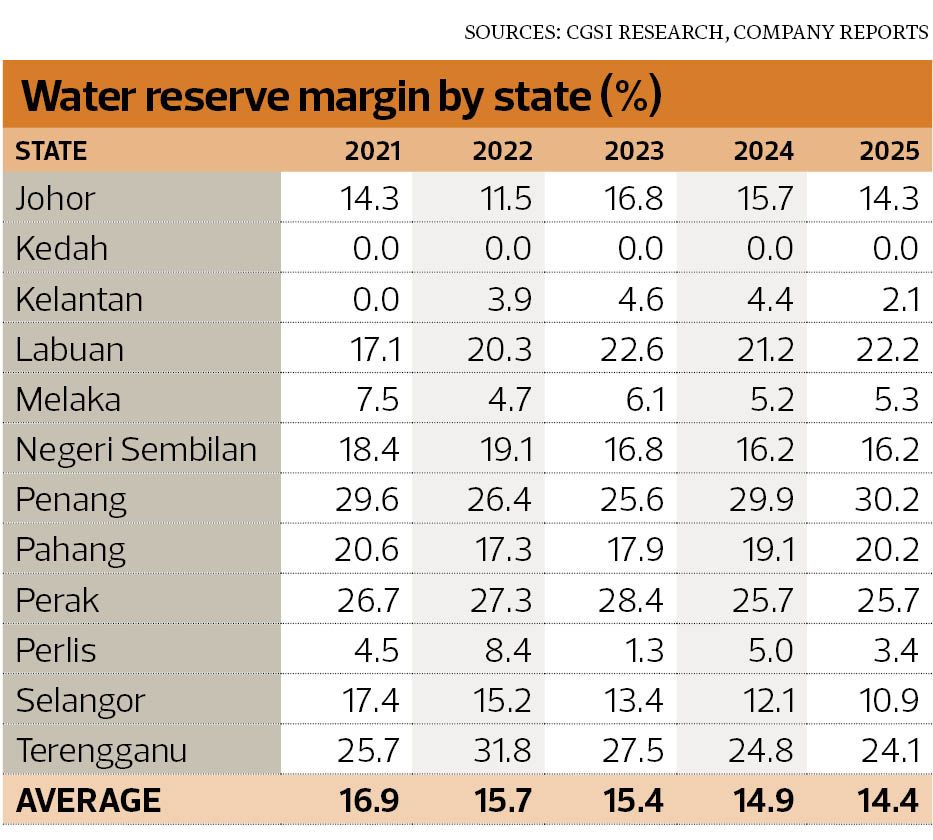
The government’s Water Sector Transformation 2040 (AIR2040) programme is also improving the sector’s long-term fundamentals. Domestic water tariff revisions implemented in February 2024 and August 2025 have narrowed the gap between tariffs and production costs to around 20 sen per cu m, from roughly 30 sen per cu m previously. Higher tariffs should strengthen the financial position of state water operators, allowing them to make more timely lease payments to PAAB while also improving their capacity to undertake infrastructure investments independently.
At the same time, demand growth is becoming increasingly structural. The rapid expansion of data centres, particularly in Johor and the Klang Valley, is driving significant increases in industrial water consumption, reinforcing the need for additional treatment capacity and distribution networks. We believe this differentiates the current investment cycle from previous attempts, which were largely dependent on government spending alone.
Among the listed beneficiaries, Gamuda Bhd (KL:GAMUDA) remains our top pick, given its proven execution track record and existing exposure to two major water projects, positioning it well to secure further contracts. Engtex Group Bhd (KL:ENGTEX) should benefit from nationwide pipe replacement works and its RM2.1 billion tender pipeline. SD Guthrie Bhd (KL:SDG) could unlock value from its industrial land bank through improved water infrastructure, while Ranhill Utilities Bhd (KL:RANHILL) stands to benefit from rising water demand in Johor should a more dynamic tariff framework be adopted. We maintain “buy” recommendations on Gamuda and SD Guthrie, “hold” on Ranhill Utilities, and Engtex remains not rated.
Hartalega Holdings Bhd
Target price: 98 sen NEUTRAL
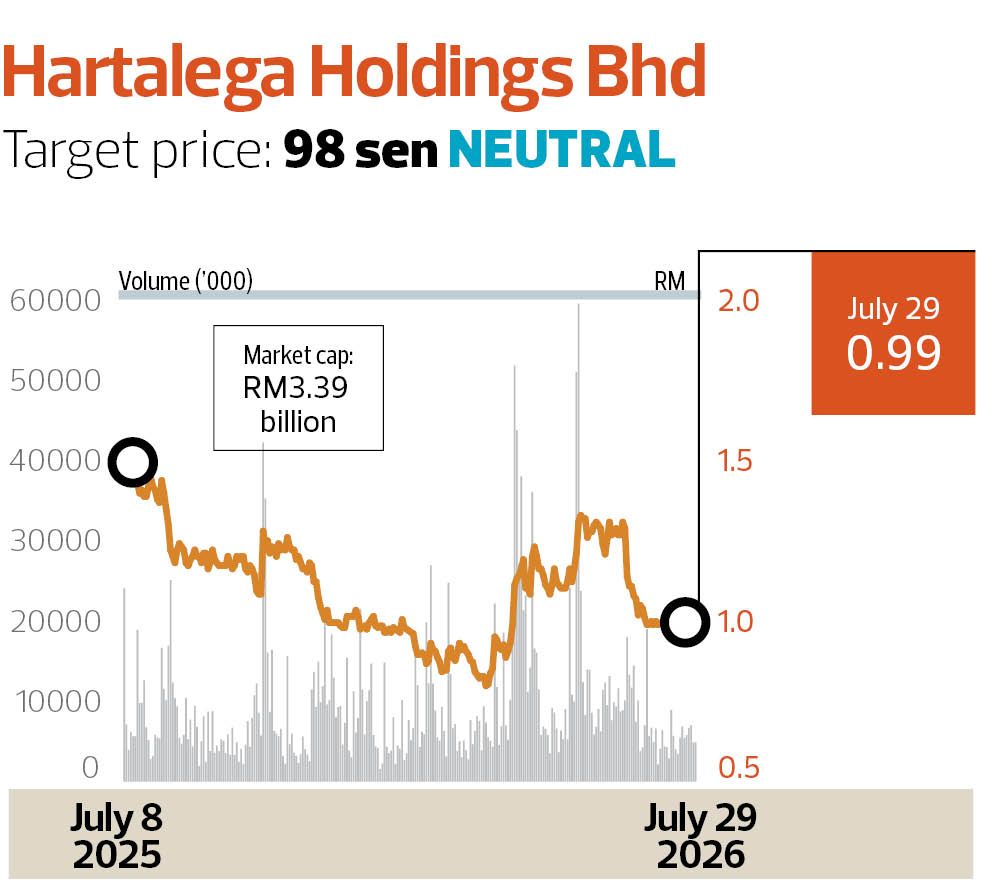
PUBLICINVEST RESEARCH (JULY 28): While renewed Middle East tensions could provide another round of average selling price (ASP) uplift, we believe the earnings upside would be less pronounced than during the March disruption. Coming away from our recent meeting with Hartalega Holdings Bhd (KL:HARTA), we note that customers are entering this episode with a more disciplined procurement strategy, with inventory levels sufficient to support a wait-and-see approach.
Meanwhile, the impending natural gas tariff adjustment from October 2026 is expected to increase cost pressures, with potential cost pass-through still under discussion. On the US front, the current 10% tariff arrangement for Malaysian glove exports remains unchanged, providing some stability for local glove makers.
We expect Hartalega’s 1QFY27 results, slated for release on Aug 4, to benefit from the stronger ASP environment during May-June and maintain our FY27F-FY29F earnings forecasts. Following the recent share price correction, we upgrade Hartalega from “underperform” to “neutral”, while keeping our target price unchanged at 98 sen, based on 0.76 times FY27 forecast P/B, which is near its -1 standard deviation (SD) 1-year historical mean.
Eco World Development Group Bhd
Target price: RM2.63 ADD
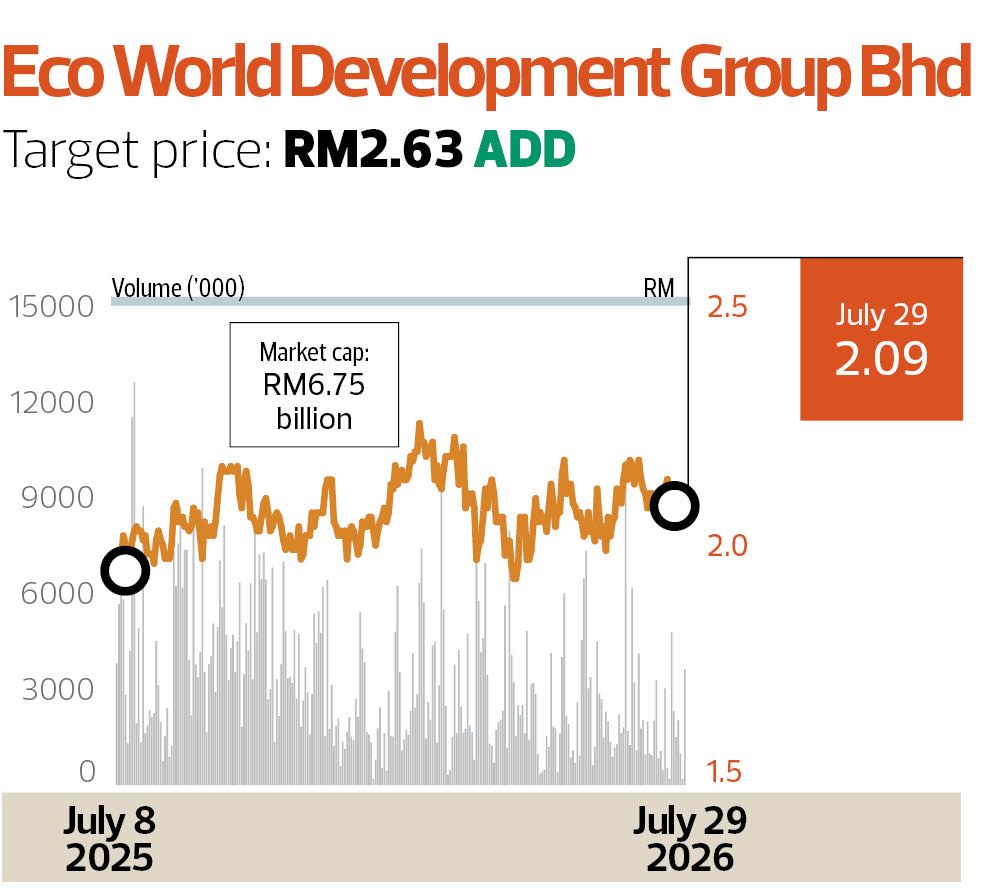
CGS INTERNATIONAL RESEARCH (JULY 28): Following our visit to Eco Business Park 7 (EBP7) within Malaysia Vision Valley 2.0 on July 21, we are more [positive] on Eco World Development Group Bhd’s (KL:ECOWLD) industrial segment. Sales have outperformed expectations for a greenfield project in an emerging corridor, with Phase 1 (SME Core) already 80% taken up, generating RM796 million in sales within seven months of its November 2025 launch.
With RM2.2 billion in remaining gross development value, management plans to launch semi-detached factories by end-2026 while marketing industrial plots to multinational corporations, including data centre operators. We see further pricing upside as EBP7’s land and factory prices remain 15%-20% below those at nearby Enstek Techpark, mirroring the appreciation seen at EBP5.We forecast EBP7 to contribute RM400 million to RM500 million in annual sales in FY27 and FY28, while the industrial segment should remain a key earnings driver, supported by EBP8, EBP9 and potential land bank expansion. We maintain our “add” call and RM2.63 target price, underpinned by strong FY26-FY28 earnings prospects, continued land monetisation and attractive dividend yields.
Malayan Flour Mills Bhd
Target price: 93 sen BUY
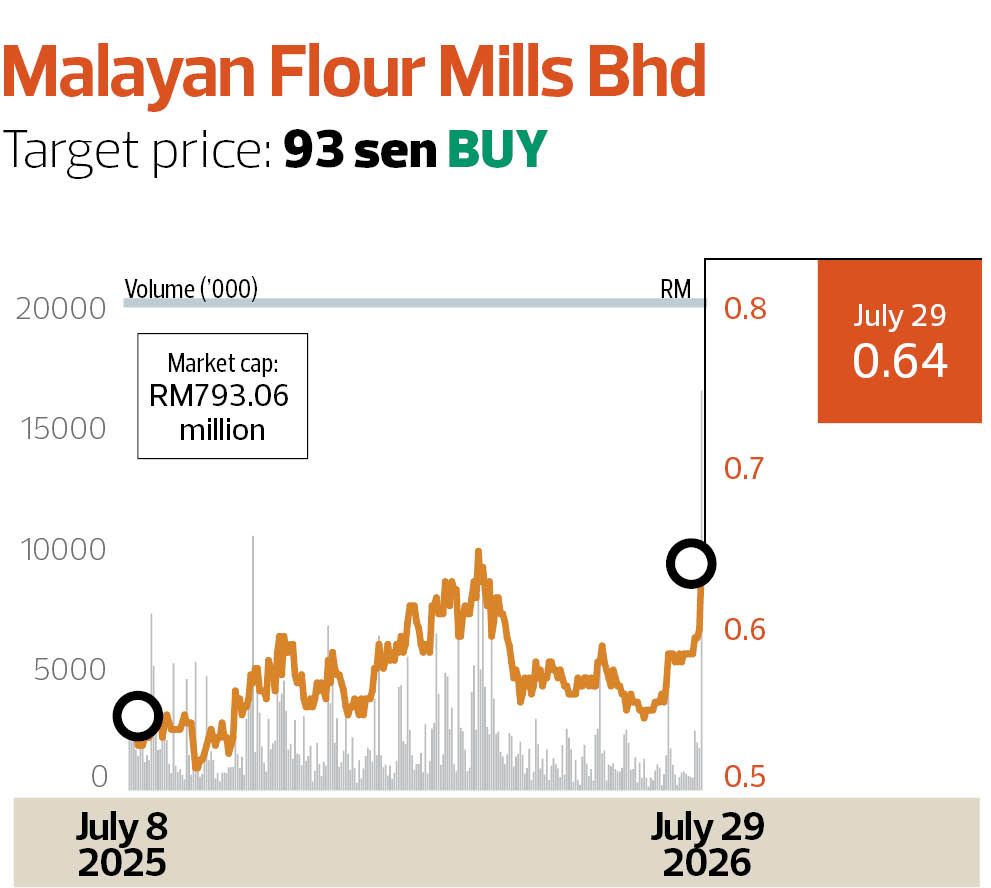
HONG LEONG INVESTMENT BANK (JULY 28): Malayan Flour Mills Bhd (KL:MFLOUR) is a leading Southeast Asian food producer with an integrated platform spanning flour milling, grains trading, poultry and aqua feed, providing resilient earnings and operational synergies. We expect long-term growth to be driven by rising flour demand in Vietnam, ongoing capacity expansion and improving poultry margins. We forecast a FY26-FY28 core earnings CAGR of 7.5%, supported by higher operating efficiency across its flour milling operations in Malaysia and Vietnam, favourable input cost dynamics, and margin expansion in its integrated poultry business as the group shifts towards higher-value products while expanding upstream and downstream capacity.
At the current share price of 59.5 sen, MFM trades at an undemanding FY26-FY28 PER of just 4.1 to 4.6 times, which we believe fails to reflect its improving earnings outlook, strong balance sheet and attractive dividend yield of about 6.7% per annum. We see scope for a valuation rerating as earnings continue to strengthen. We initiate coverage with a “buy” recommendation and a target price of 93 sen, based on a seven times PER to mid-FY27 forecast core EPS of 13.3 sen.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.