

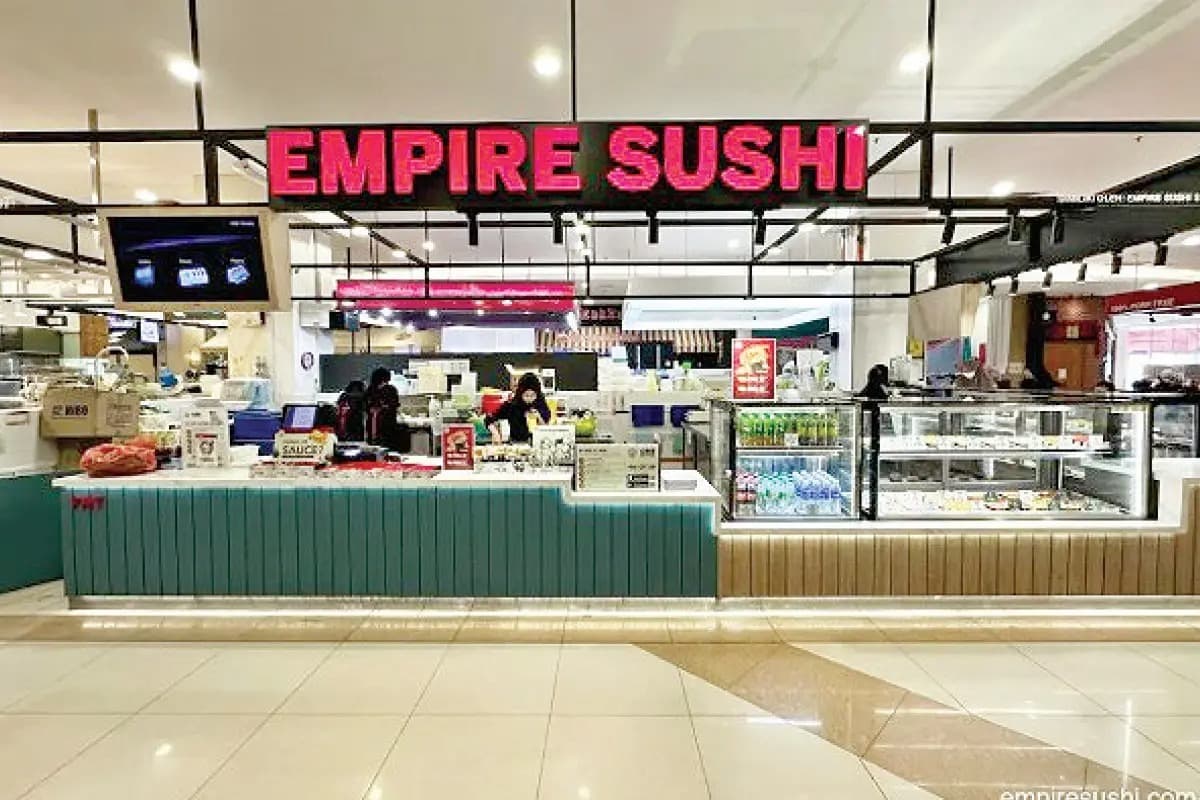
KUALA LUMPUR (Aug 4): Empire Premium Food Bhd (KL:EMPIRE) deserves higher valuation than its peers, as its sushi takeout chain could produce higher returns than other restaurant operators, said an analyst.
The company should be valued at 20 times its 2027 earnings, a 10% premium to the regional peers’ average, due to its superior return-on-equity of 23%-34% over the next three financial years, Maybank Investment Bank said and initiated coverage on Empire Premium with ‘buy’ call.
The target price of RM1.20 is backed by Empire’s “sustainable earnings growth runway, expected resilience in sales momentum given its low-price point products, and benefits of consumer down-trading trends,” the research house said.
Maybank Investment joins CIMB Securities and Affin Hwang Investment Bank, both of which also have a ‘buy’ call on Empire Premium. The average target price of the three research houses now stands at RM1.21, implying potential upside up to 14% in the next 12 months.
Shares of Empire Premium have barely budged since their listing day, though investors who bought into the stock's initial public offering in April and held on would still be sitting on gains of 49%. The company had 143 stores at the end of March.
“Empire has a highly scalable business model that enables rapid expansion through standardised processes and efficient supply chain management,” Maybank Investment said.
Earnings will be driven by the net addition of 15 stores in the financial year ending March 31, 2027 (FY2027) and another 18 outlets in FY2028 with annual revenue per store growth of 5%, the research house said.
All in all, Empire Premium could make an average annual earnings growth of 18% for FY2027-FY2029, according to its forecasts.