

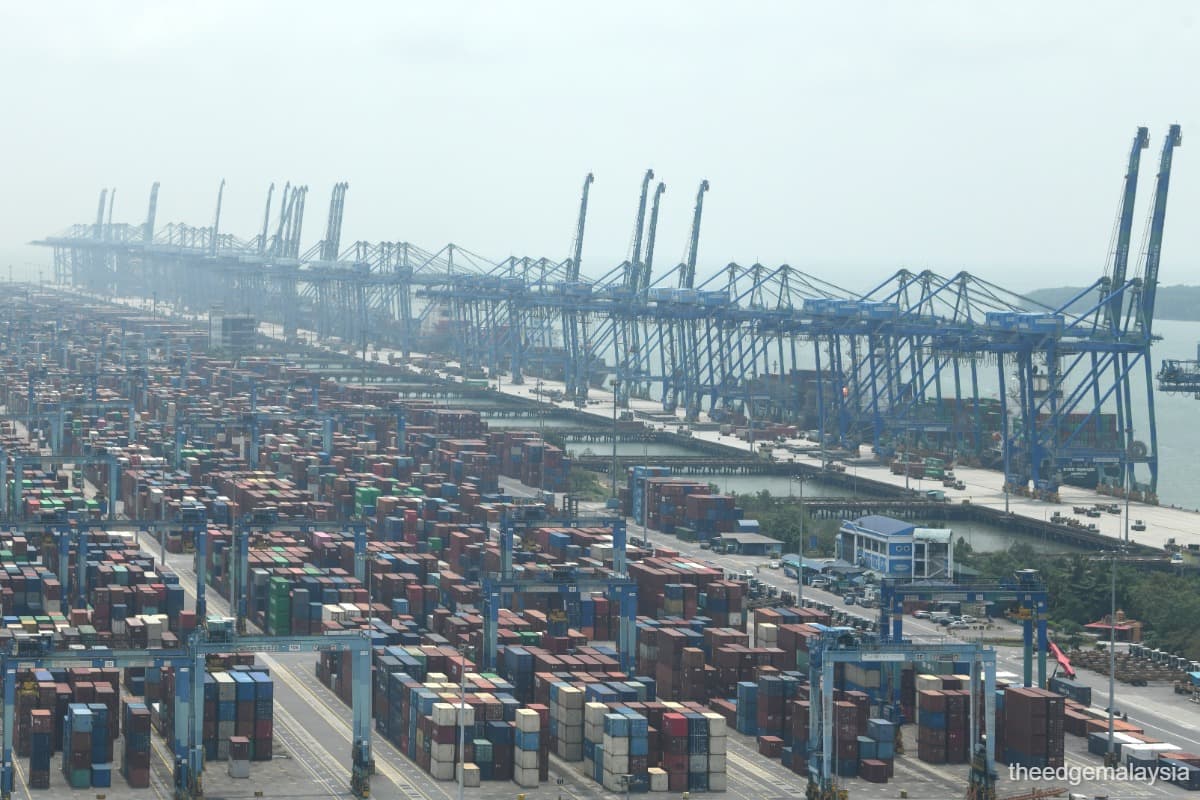
KUALA LUMPUR (July 24): Analysts reaffirmed their bullish stance on Westports Holdings Bhd (KL:WPRTS) after the port operator beat expectations, as tariff revisions continue to shield earnings from elevated fuel costs triggered by the Middle East conflict.
The port operating company reported a core net profit increase of 7.6% quarter-on-quarter (q-o-q) for the second quarter ended June 30, 2026 (2QFY2026), while first-half profits beat consensus forecasts with a 50% year-on-year (y-o-y) increase to RM682 million in revenue.
This reflected a 30% y-o-y growth in income, which allowed it to outpace rising operating cost of 10% y-o-y. "The outperformance was likely driven by the recent tariff hike and higher value-added services (VAS), which more than offset cost inflation," Maybank Investment Bank Research explained in a note.
Fuel costs rose 40% y-o-y in 1HFY2026, largely due to an increase in fuel prices amidst renewed conflicts in the Middle East. While fuel remains Westports' second largest cost component at 21.5% of total costs for 1HFY2026, analysts believe tariff revisions will continue to offset most of its impact in 2HFY2026, cementing their bullish outlook on the port operator.
“Management also maintained its guidance for low single-digit container throughput growth in 2026,” Hong Leong Investment Bank reported, with container throughput declining 1.1% y-o-y for 1HFY2026.

Accordingly, this allowed for post congestion to ease and shipping volumes to recover amidst shipping disruptions in the Middle East.
Reflecting higher VAS and more modest cost assumptions, Maybank maintained its 'buy' rating on Westports stock, and raised its discounted cash-flow (DCF) based target price to RM7.66.
Other notable houses such as CIMB Securities and HLIB also maintained their 'buy' rating on the group, with a DCF-based target price of RM8 and RM7.15 per share.
At the time of writing, Westports enjoyed a largely bullish outlook by most of the 17 research houses tracked by Bloomberg, with 12 'buy' and five 'hold' calls. The average 12 month target price hovers at RM6.85 per share, ranging between RM5.36 and RM8.20 per share.
CIMB has noted that the group has declared a first interim dividend of 14.98 sen per share, including an elective dividend of three sen per share.
This will likely contribute to Westports’ recent dividend reinvestment programme, which would be used to fund its Westports 2 expansion while strengthening shareholder value.