

This article first appeared in Capital, The Edge Malaysia Weekly on July 13, 2026 - July 19, 2026
AN investor, who bought ViTrox Corp Bhd (KL:VITROX) shares more than a year ago and held on to them through the volatility in the technology sector, would now be reaping the reward of that patience and bet that the company will see better days.
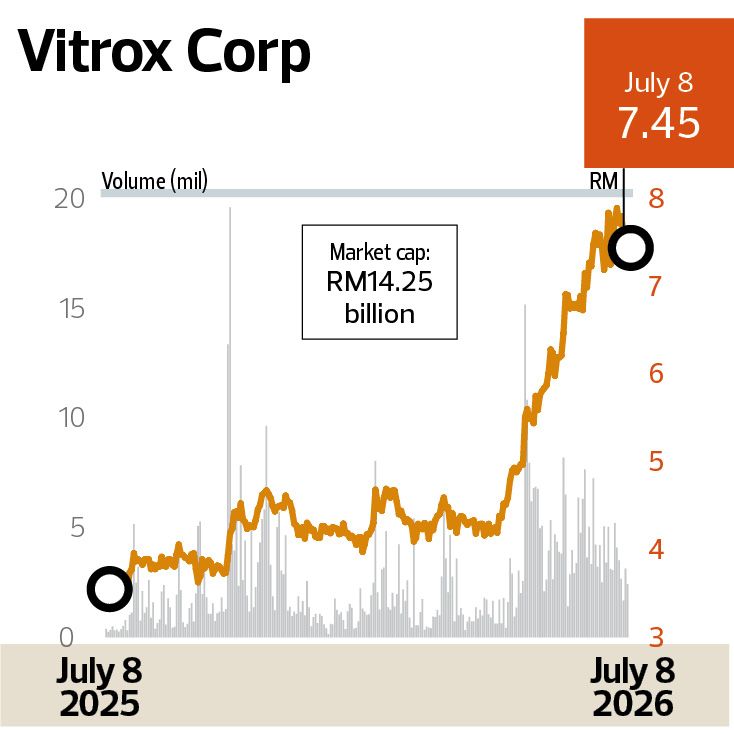
At its lowest in 2025, ViTrox shares were hovering around RM2.30 apiece as concerns over US-led chip sanctions and tariff threats weighed on the local semiconductor sector.
It took about six months before the share price breached the RM4 threshold in October 2025. Since April this year, however, there has been no stopping ViTrox’s ascent, as the stock price doubled from RM4 levels to hit RM8 within three months.
Some investors might have chosen to take profit, with ViTrox shares closing at RM7.45 last Wednesday (July 8) — still slightly more than double their level a year ago.
At RM7.45, ViTrox shares have edged above the 12-month average target price of RM7.44 among analysts covering the stock, according to Bloomberg data at the time of writing.
Should more investors be taking profit, or are the more bullish forecasters right about ViTrox potentially reaching RM10 within the next 12 months?
The wide target price range of RM3.30 to RM10 ascribed by analysts speaks to this dilemma.
According to Bloomberg data, most target prices at the lower end of the range have remained unchanged over the past three months, whereas those at the higher end came from analysts who increased their price targets during the same period.
The calls of the analysts covering the stock — nine “buy”, three “hold” and two “sell” — suggest that the majority believe there is further upside potential for the automated test equipment manufacturer’s share price. But how much upside remains?
According to prevailing earnings estimates, ViTrox is the most expensive stock among its peers. It has a 12-month trailing price-earnings ratio of 90 times and an average forward PER of 61.21 times.
BIMB Securities research analyst Steven Chong believes investors, who are holding on to the stock, can afford to wait before taking profit, but it is currently expensive for investors considering picking up the shares. He has a “hold” call on the stock.
“The stock is pricey right now; so, it is not a good entry point for new buyers. However, there is no need to sell yet. For existing investors, the thesis remains intact as long as there are no fundamental signs of deceleration in corporate earnings momentum.
“Given that broader market demand continues to outpace supply — resulting in healthy, recurring order backlogs — we anticipate that this robust earnings momentum will be fully sustained over the near term,” he says.
The surge in ViTrox’s share price comes amid the better-than-expected earnings performance in the first quarter ended March 31, 2026 (1QFY2026). There is also the broad-based technology sector boom, driven by AI demand that has helped propel the share price.
The global semiconductor upcycle has got investors excited. The demand for AI infrastructure has lifted the whole semiconductor supply chain into an upturn, says Hong Leong Investment Bank Research (HLIB Research).
“What began in GPUs (graphics processing units) and AI (artificial intelligence) accelerators has since worked downstream into memory, semicap (semiconductor capital) equipment, networking, optical, CPUs, power semiconductors, substrates and now even reached passive components like MLCCs (multi-layer ceramic capacitors),” it notes.
“This marks the transition to a broader semiconductor upcycle, where capacity/supply rather than demand is increasingly the limiting factor.”
The research house believes there will be further earnings delivery and positive revisions ahead for the sector.
Interestingly, HLIB Research, which is “overweight” on the technology sector, recently downgraded its call on ViTrox to a “hold” despite raising its target price to RM8.05 from RM6.
In a report dated July 2, the research house says it remains constructive on ViTrox, supported by a strong order book and pricing power in the midst of tight supply in the equipment market.
It also raised its FY2026 to FY2028 earnings forecasts for ViTrox by 12% to 19%, on account of higher unit shipment and average selling price assumption, as equipment demand turns robust from the aggressive capacity expansion by global EMS (electronics manufacturing services) players.
But it justifies its downgrade to a “hold”, as it believes the upside has narrowed, following the share price outperformance, and says it would instead look to accumulate on pullbacks.
Meanwhile, Maybank Investment Bank Research, which has a “buy” call on ViTrox and a target price of RM9, said in a report in June that ViTrox remains its top pick for large-cap stocks.
“We believe ViTrox is on track to surpass RM1 billion in revenue in FY2026, driven by persistent strong demand for machine vision system and automated board inspection products,” it said.
According to the research house, ViTrox continues to operate at near-maximum delivery output, with component availability the primary bottleneck. Notably, the group is embarking on capacity expansion activity, with its new facility slated for the second half of 2026.
“Beyond the key cloud service provider (CSP) contributing to the order surge, ViTrox is also actively engaged with two additional CSPs, underscoring the broadening customer base within the data centre supply chain,” said Maybank IB Research.
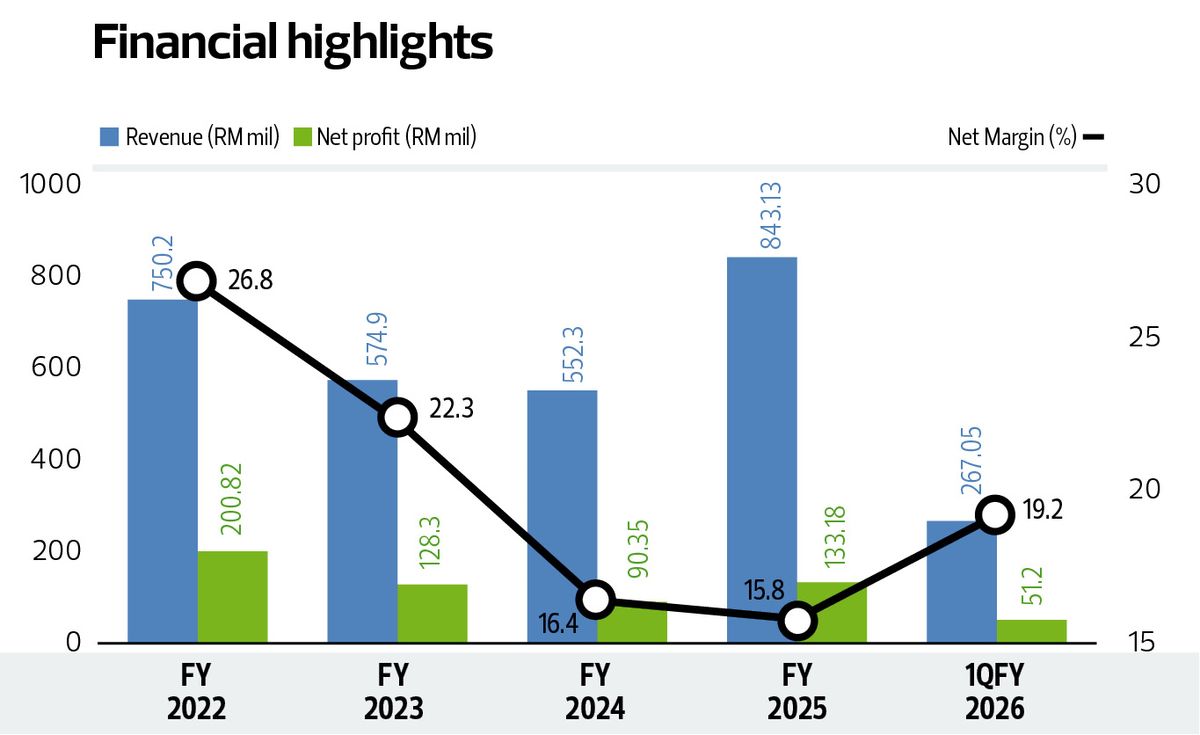
For 1QFY2026, ViTrox’s net profit more than doubled to RM51.2 million from RM24.16 million, on the back of an 89% year-on-year increase in revenue to RM267.05 million in 1QFY2026, from RM141.12 million. Net profit margins for the quarter stood at 19.1%, compared with 17.1% in the previous year.
In its 1QFY2026 results review in April, CIMB Securities said ViTrox’s total purchase orders reached a record RM332.4 million at endMarch, with the booktobill ratio rising to 1.3 times.
Investors will be keenly watching the upcoming 2QFY2026 earnings announcement, scheduled for July 24, following management’s earlier guidance that revenue for the second quarter would range from RM252 million to RM274 million.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.