

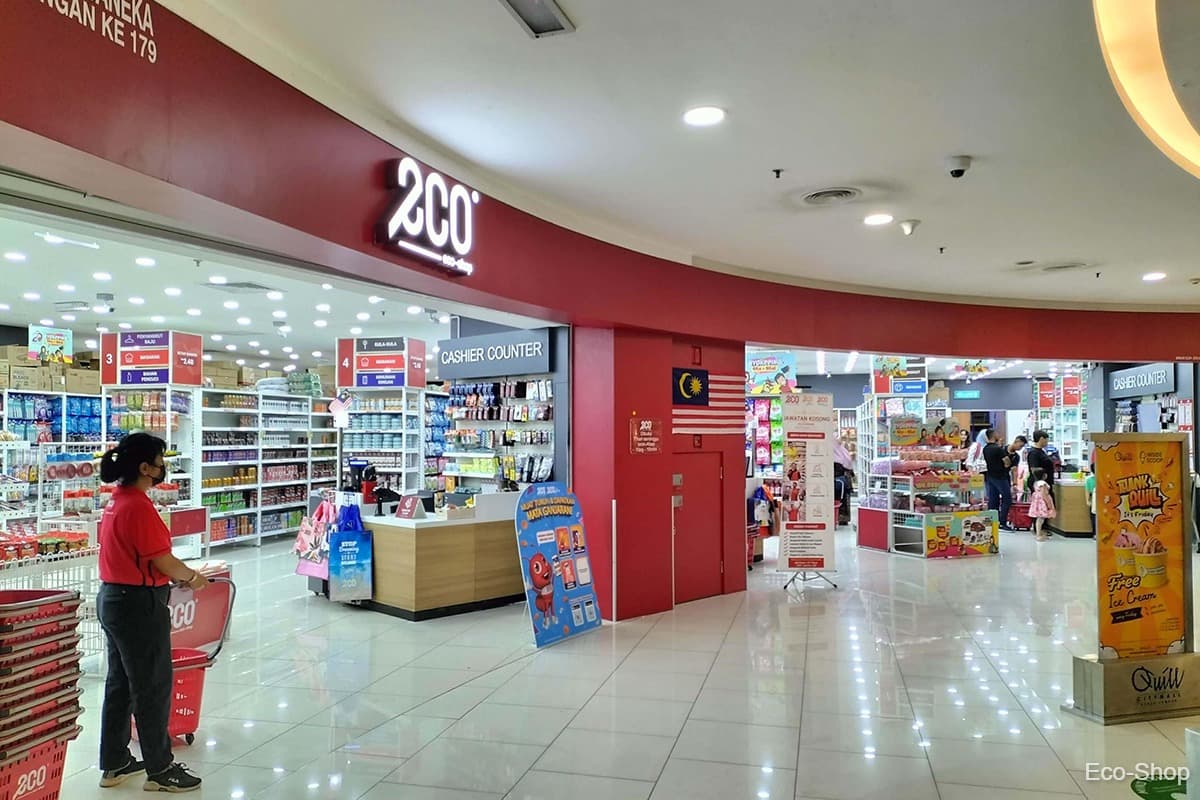
KUALA LUMPUR (July 2): Eco-Shop Marketing Bhd (KL:ECOSHOP) rose to a nearly four-month high on Thursday’s early session, after analysts turned bullish on the group’s same-store-sales-growth (SSSG) turnaround.
The counter climbed eight sen or 6% to RM1.44, with 7.25 million shares changing hands, valuing the group at RM8.29 billion.
Following a recent meeting with Eco-Shop’s management, RHB Investment Bank said the group is poised to reverse its negative SSSG trend, thanks to the normalisation in consumer demand and stock supply.
In a note on Wednesday, RHB maintained its "buy" call on Eco-Shop with a target price (TP) of RM1.80, implying a 36% upside and a roughly 2% yield for FY2027.
"The inflationary environment could bode well for it to entice price-conscious consumers and regain price competitiveness.

"With its opex well under control, we look forward to a robust three-year earnings CAGR of 19% ahead, and believe the stock’s current valuation is attractive," said the house.
On the SSSG recovery front, management has observed an improving trend, underpinned by a healthy pick-up in transaction counts, it added.
"This could be driven by effective sales promotions, normalised supply from disruptions, and favourable base effects (SSSG started turning negative in 4QFY2025 post the mid-April price increase)."
On top of that, RHB believes the softening consumer sentiment on the back of inflation-related worries could have reminded consumers of Eco-Shop’s value-for-money proposition.
Meanwhile, the company should meet its target of opening 100 new outlets in FY2026 (9MFY2026: 65), and the same run rate could continue into FY2027.
The refurbishment exercises are yielding positive results, with refitted stores achieving a sales uplift of over 10%, RHB noted.
In terms of cost pressures, management guided for a total additional cost of RM1.5 million per month arising from the Middle East conflict in the form of input costs (higher costs for about 700 plastic-related product SKUs) and freight expenses.
"This could help Eco-Shop regain price competitiveness, as non-dollar store competitors are likely to pass on the higher costs to consumers, whereas Eco-Shop will maintain its pricing."
That said, the gross profit margin impact should be partially cushioned by the SKU optimisation, growing sales contributions of house brands, and its expanding scale of operations, as well as favourable FX trends.
Meanwhile, operating expenditure should remain stable, considering the initiatives to right-size store headcounts and lift productivity, as well as its bargaining power to secure favourable rental rates.
Eco-Shop is scheduled to announce its FY2026 results on July 22.
The implied 4QFY2026 net profit of RM67 million (+18% year-on-year) by RHB’s and consensus forecasts is likely to be met.
The research house maintained its forecasts for now, pending the results release and further guidance from management.
Its discounted cash flow (DCF)-derived TP of RM1.80 (inclusive of a 4% ESG premium) is unchanged, implying 33x price-to-earnings 2027F or at a discount to the large-cap consumer peers.
Downside risks to the recommendation include reputational issues, slower-than-expected store expansion, and stronger-than-anticipated cost inflation that cannot be passed on to consumers.