


This article first appeared in Capital, The Edge Malaysia Weekly on June 15, 2026 - June 21, 2026
BURSA Malaysia is set to welcome three new ACE Market listings this week, bringing the number of listings on the local bourse to 33 year to date and exceeding half of last year’s total of 60 listings. Of the 33, 22 were ACE Market listings, six were on the LEAP Market and five on the Main Market.
Enterprise ICT solutions provider Pentech Holdings Bhd (KL:PENTECH) is slated to list on June 15, followed by oil and gas (O&G) service and equipment solutions provider Elsa Bhd (KL:ELSA) on June 16, and integrated engineering services and turnkey solutions provider Sum Technology Bhd (KL:SUM) on June 18.
Based on the companies’ respective initial public offering (IPO) prices and enlarged share bases, their market capitalisation is similar at RM123.83 million for Elsa at 23 sen each; RM124 million for Pentech at 20 sen each; and RM126 million for Sum Technology at 28 sen apiece.
Pentech is raising the largest amount at RM34.4 million in gross proceeds (RM29.9 million net RM4.5 million listing expenses), followed by Sum Technology (RM32.76 million gross proceeds, or RM28.86 million net RM3.9 million listing expenses) and Elsa (RM27.23 million gross proceeds, or RM23.43 million net RM3.8 million listing expenses). Elsa’s promoters are also offering for sale 36.4 million shares, or a 6.76% enlarged share base, to raise RM8.37 million for themselves.
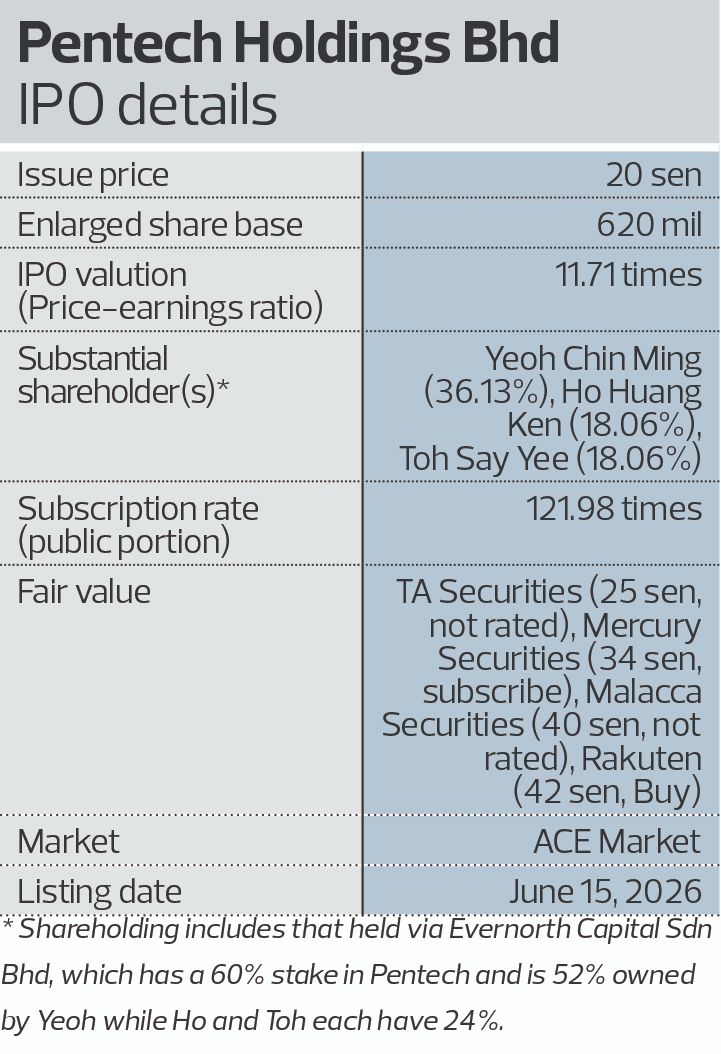
Pentech and Sum Technology’s public portions were more than 100 times subscribed while Elsa’s was 11.51 times subscribed. All three companies do not have a formal dividend policy currently. (See also “Sum Technology rides semiconductor upswing” on Page 30.)
Penang-based Pentech has a two-decade track record in the ICT industry, starting out in 2006 by supplying ICT hardware and software to businesses in Malaysia before carrying out its first integration of ICT infrastructure works in 2011. The latter involved cabling and electrical works, access control systems and network control switches for the data centre of an unnamed electrical and electronics product manufacturer in Bayan Lepas.
Of the RM34.4 million in gross proceeds, 37.33% or RM9.4 million has been earmarked for the establishment of a new security operations centre (SOC) in Kuala Lumpur to facilitate the monitoring of network security incidents as well as to enhance its competitiveness in securing cybersecurity managed services, which is expected to contribute to recurring income. The SOC is expected to commence operations by the fourth quarter of 2026, with the tenancy agreement being finalised.
Pentech is also setting aside RM8.1 million (23.55%) to upgrade the group’s operations command centre (OCC) infrastructure, with the primary OCC in Kuala Lumpur and supported by its Penang office, and a secondary OCC to ensure business continuity and disaster recovery.
Some RM6.74 million or 19.59% of gross proceeds is for expansion into the provision of additional ICT services such as artificial intelligence (AI)-powered cloud services from Penang and Kuala Lumpur, and RM3.5 million (10.17%) is for marketing expenses, leaving RM2.16 million (6.28%) for working capital after listing expenses.
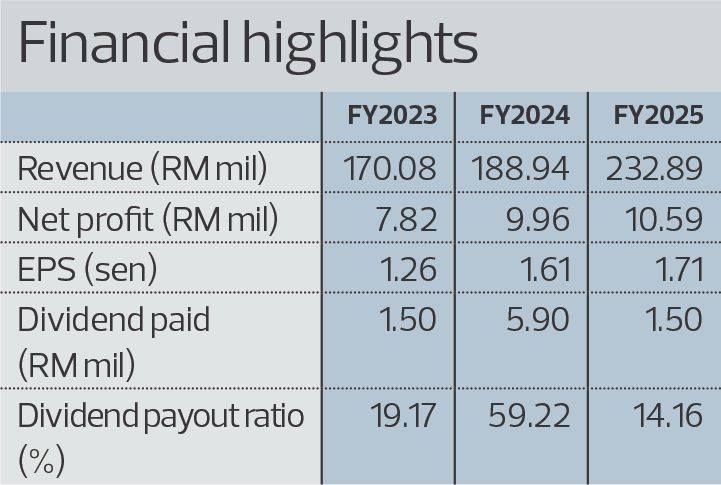
The Pentech promoters are managing director and CEO Yeoh Chin Ming, 52; chief sales officer Ho Huang Ken, 46; and substantial shareholder Toh Say Yee, 58. The trio has a 60% stake in Pentech parked under Evernorth Capital Sdn Bhd, which is 52% owned by Yeoh, and 24% each by Ho and Toh. Their collective 72.26% stake post-IPO is subject to a six-month moratorium of sale. They are obliged to keep at least a 45% stake in the subsequent six months, a 30% stake two years after listing and a 15% stake three years post-IPO.
Pentech’s net profit came in at RM10.59 million on the back of RM232.89 million in revenue for the financial year ended Dec 31, 2025 (FY2025).
According to its IPO prospectus, Pentech had RM82.18 million in remaining purchase orders for the integration of enterprise ICT infrastructure, supply of hardware and software, and the provision of other services as at April 27, 2026. In addition, it had RM5.53 million in remaining contract value for the provision of cloud and managed services, which range from one to five years, with revenue recognised when services are rendered.
Fair value ascribed by research houses to Pentech varies substantially — TA Securities has a fair value of 25 sen, Mercury Securities 34 sen, Malacca Securities 40 sen and Rakuten Trade Research 42 sen. Of the four, Rakuten has a “buy” rating, Mercury recommends “subscribe” while the other two have issued “non-rated” notes.
In a note dated May 28, TA Securities said its 25 sen fair value was arrived at after ascribing a 12 times multiple on Pentech’s 2027 earnings. It expects the group’s earnings to grow 6.9% to RM11.3 million in FY2026, 14% to RM12.9 million in FY2027 and 13% to RM14.6 million in FY2028 — backed by an RM87.7 million unbilled order book, business expansion plan and healthy ICT industry outlook, underpinned by ongoing digital transformation initiatives in both the public and private sectors and supportive government policies.
Pentech’s balance sheet is expected to be in a net cash position of RM54.3 million, or 8.8 sen per share on a pro-forma basis, post-listing with the utilisation of IPO proceeds, TA added.
Noting Pentech’s net cash position post-listing, aggressive expansion pipeline and strong partnership with multinationals, Rakuten ascribed a multiple of 16 times over FY2027 earnings to arrive at its 42 sen fair value and “buy” recommendation. Rakuten is more bullish on earnings growth, expecting the company’s net profit to reach RM13 million in FY2026 and RM16.1 million in FY2027.
“[Pentech] has established strong partnerships with major multinational technology companies including Dell Technologies, Microsoft, HPE, Lenovo, VMware, Fortinet, Sophos, Oracle and Pure Storage to support its enterprise ICT solutions business. Through these partnerships, the company provides enterprise data centre infrastructure, cloud computing, cybersecurity, virtualisation, backup and disaster recovery, networking systems, as well as hardware and software integration services for corporate customers, while also enabling the group to expand into higher-value and potentially higher-margin enterprise solutions,” Rakuten wrote in a May 28 note.
For the first quarter ended March 31, 2026, Pentech’s net profit came in at RM1.7 million on the back of RM66.46 million in revenue, taking into account RM1.07 million in listing expenses charged during the quarter, according to an unaudited interim financial statement released on June 10. In accompanying notes, Pentech said it had so far incurred RM2.25 million of the RM4.5 million in listing expenses estimated in its IPO prospectus. Of this, RM1.55 million had been charged to retained earnings while RM0.7 million will be expensed to its profit and loss account upon completion of its IPO. It did not provide comparative quarterly figures.
Mercury Securities noted that Pentech’s recurring revenue stream grew to 20.7% in FY2025 from 9% in FY2022, improving earnings visibility. It highlighted strong cross-selling among business segments, supported by scalable cloud and managed services. The research house ascribed a 14.75 times multiple to its estimated FY2027 earnings per share of 2.34 sen, benchmarked against the five-year average earnings multiple of selected ICT solution provider peers.
“[Pentech] stands out for its positioning as a one-stop, end-to-end ICT solutions provider with over two decades of experience,” Mercury Securities wrote in a note dated May 29. It is positive on long-standing customer relationships anchored by recurring technology refresh cycles; manufacturing and financial services digitalisation trends; and expansion into higher-margin, recurring ICT services.
Malacca Securities’ 40 sen fair value for Pentech, double its 20 sen IPO price, is 16.5 times multiple of estimated FY2027 earnings per share of 2.4 sen. “The building of a new 24/7 SOC in Kuala Lumpur and upgrading of its underlying OCC infrastructure, coupled with the expansion into specialised cybersecurity business units and automated, AI-powered cloud applications, will catalyse Pentech towards more high-margin recurring revenues moving forward.
“We like Pentech’s ability to design custom systems that meet strict security, data protection and uptime rules, making it a highly trusted partner for large corporations and a reliable deployment partner for companies in heavily regulated sectors, including manufacturing, healthcare and finance,” it added.
Kuala Lumpur-headquartered Elsa provides solutions for oilfield services, talent, digital, as well as robotics and engineering, allowing it to support customers across various stages of O&G project implementation.
“We intend to strengthen our market presence as a provider of O&G service and equipment solutions in Malaysia and increase our portfolio of projects. Hence, we intend to allocate RM17.78 million from our IPO proceeds to fund consultant-related expenses for the oilfield service solutions and digital solutions segments as well as to procure drones for the provision of robotics and engineering solutions,” Elsa said in its IPO prospectus, calling itself an “asset-light company”.
“We do not own proprietary technology or manufacture our own products. We source and establish agency-principal relationships with our technology partners, whereby we serve as agents to our technology partners, who are the principals.”
To support the execution of existing and future projects related to robotics and engineering solutions, Elsa has allocated RM1.4 million of its IPO proceeds to procure drones and RM3 million to hire nine additional personnel to form an in-house technical team for the management and deployment of autonomous underwater vehicle (AUV) subsea pipeline inspection services.
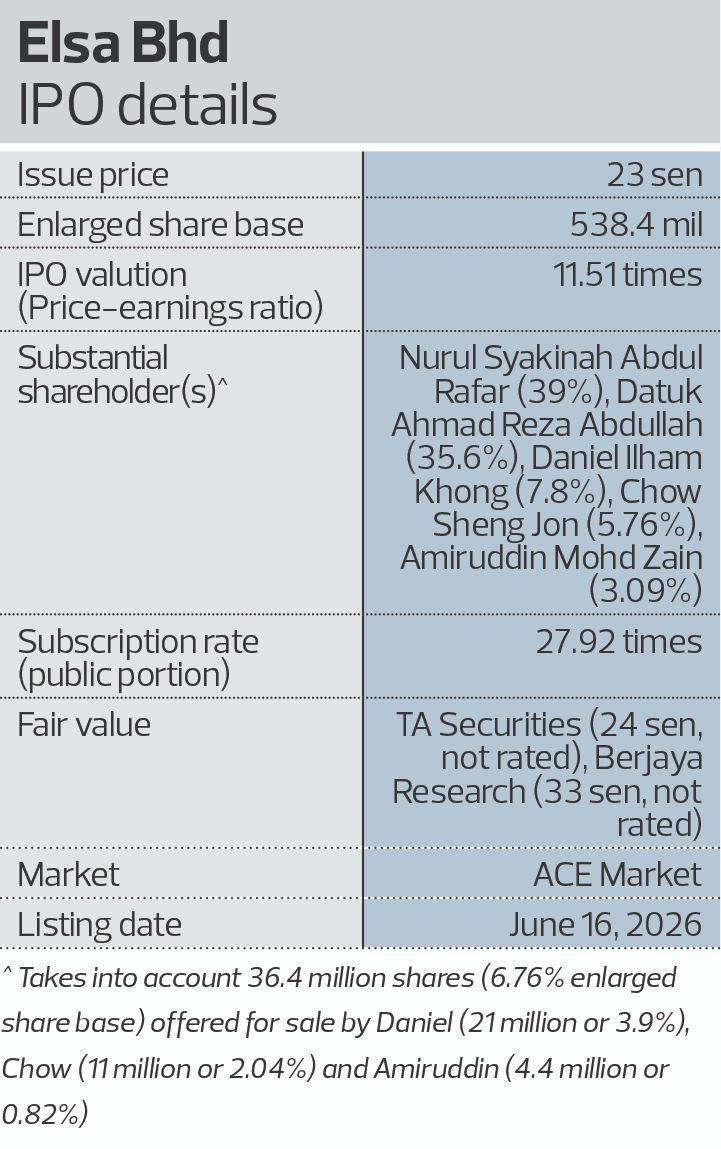
Fair value ascribed by research houses to Elsa also varies substantially. TA Securities ascribed a fair value of 24 sen, valuing Elsa at eight times FY2027 earnings in a “non-rated” report that also noted “extensive PETRONAS licences and multinational technology partners” help the group “support upstream and downstream O&G activities while serving major industry players in Malaysia”.
“[Elsa] has built a strong portfolio of customers within the O&G industry, comprising PETRONAS Group, Hibiscus Oil & Gas Malaysia Ltd, EnQuest Petroleum Production Malaysia Ltd, PTTEP Malaysia Assets and other major industry players. Its long-standing relationships with customers, supported by repeat contracts over periods ranging from two to 10 years, have enabled the group to secure recurring business opportunities and drive revenue growth from RM97.5 million in FY2022 to RM264.7 million in FY2025 despite a challenging industry environment,” TA Securities wrote in a note dated May 29.
“Since 2022, the group has also diversified its customer base beyond O&G through project contracts in talent solutions, digital solutions, and robotics and engineering solutions for customers across education, financial services, food and beverage, government and infrastructure sectors,” TA added. It said on a pro-forma basis, post-listing with utilisation of IPO proceeds, Elsa’s balance sheet is expected to be in a net cash position of RM38.8 million or 7.2 sen per share.
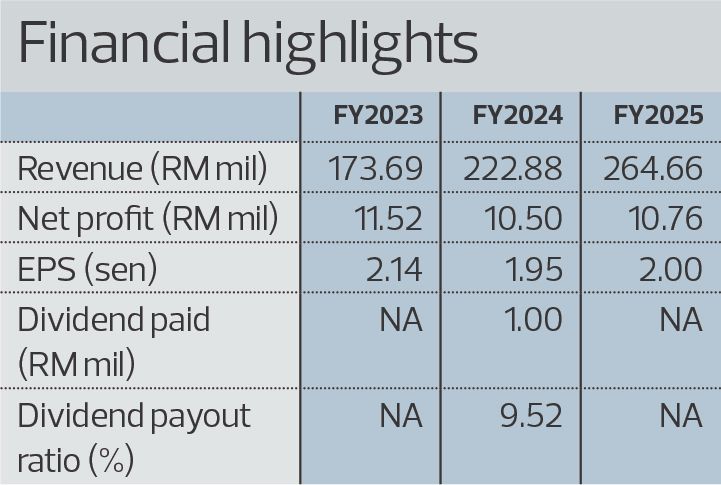
Noting that Elsa has an over 20-year operating track record and a 0.2% market share in the oil and gas services and equipment (OGSE) industry in 2024, Berjaya Research ascribed a 33 sen fair value to Elsa, a premium of 43.5% over its IPO price of 23 sen, based on 11 times its projected FY2027 earnings of three sen per share.
“Long-standing relationships, supported by repeat contracts spanning two to 10 years, demonstrate customer confidence in Elsa’s capabilities. Growth initiatives are reinforced by RM17.8 million in IPO proceeds, 140 ongoing projects and 157 tenders currently in the pipeline. Elsa is investing RM3 million to expand its robotics and engineering capabilities. This segment is the group’s fastest-growing business, with revenue increasing from RM0.8 million in FY2022 to RM26 million in FY2025, representing a three-year compound annual growth rate (CAGR) of 221.2%,” Berjaya Research wrote in a non-rated note dated June 3.
Risk factors for Elsa include “non-renewal of PETRONAS licences and changes in PETRONAS policies; PETRONAS as single-customer risk; and dependence on existing contracts”, it added.
The company has three PETRONAS licences — one with a validity period of three years up to Feb 25, 2028, the second up to Dec 25, 2028 and the third up to Jan 4, 2029 — which are subject to renewal four months before expiry. PETRONAS contributed 25.06% of Elsa’s revenue in FY2023, 34.12% in FY2024 and 40.17% in FY2025. “As a supporting OGSE industry player, we are dependent on PETRONAS. Given our past and ongoing contracts with PETRONAS Group, it may continue to contribute significantly to our group’s revenue in the future,” Elsa’s prospectus read.
Elsa’s promoters are non-executive director Nurul Syakinah Abdul Rafar, 37, spouse of managing director and founder Daniel Ilham Khong, 62; head of digital, robotics, engineering and talent solutions Chow Sheng Jon, 41; and executive chairman Amiruddin Mohd Zain, 64, who joined as CEO in 2018 and was redesignated to his current position in March 2024.
Post-IPO and offer for sale — involving 36.4 million shares (6.76% enlarged share base) by Daniel (21 million or 3.9%), Chow (11 million or 2.04%) and Amiruddin (4.4 million or 0.82%) — Nurul Syakinah will remain Elsa’s largest shareholder with a 39% stake, of which 23.4% is held via Sparkle Success Sdn Bhd. Keretapi Tanah Melayu Bhd chairman Datuk Ahmad Reza Abdullah, 63, is Elsa’s second-largest shareholder with 35.6%, of which 15.6% is via Prestasi Emas Sdn Bhd.
The collective 55.65% stake held by Nurul Syakinah, Daniel, Chow and Amiruddin is subject to a six-month moratorium, after which 45% will continue to be subject to a moratorium for the following six months. The moratorium is 30% two years post-listing and 15% three years post-listing. Ahmad Reza’s Prestasi Emas also voluntarily provided an undertaking for a six-month moratorium on its 15.6% stake.
Public Investment Bank Bhd is the principal adviser, sole underwriter and placement agent for Pentech’s IPO. Malacca Securities is the principal adviser, sponsor, underwriter and placement agent for the IPOs of Elsa and Sum Technology.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.