

KUALA LUMPUR (June 11): Liftech Group Bhd’s growth prospects are already fairly valued at its listing price, leaving no upside for investors of the crane builder post-listing, said TA Securities.
At the initial public offering (IPO) price of 29 sen per share, Liftech would be valued at 14 times its 2025 earnings, above Powertechnic Group Bhd’s (KL:POWER) trailing multiple of about 11 times, according to the research house’s unrated note.
“While we acknowledge Liftech’s favourable growth prospects, niche market positioning and enhanced financial flexibility post-listing, we believe these strengths are largely reflected in the IPO valuation,” TA Securities said.
Applications for Liftech’s IPO will close on June 16, and listing has been scheduled for June 30.
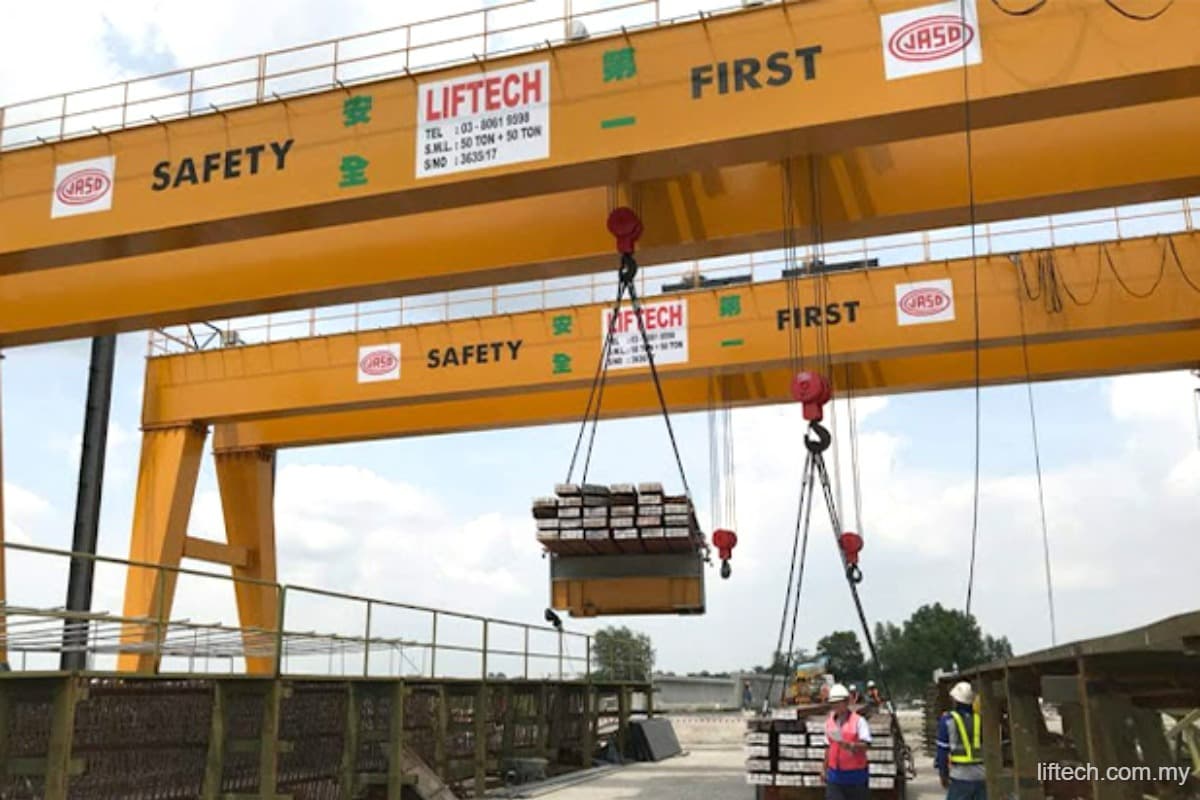
Based in Puchong, Selangor, Liftech manufactures industrial lifting and handling equipment such as overhead cranes, gantry cranes and goods hoists. The group also provides maintenance and repair services, as well as trading of crane components, accessories and related equipment.
As at May 10, the company had an unbilled order book of RM41.6 million that will be recognised over the relatively short cycle of the next six to nine months.
“Liftech will need to continuously secure new purchase orders to sustain earnings momentum beyond the existing order book horizon,” TA Securities cautioned. “Failure to replenish its order book at a pace sufficient to offset project burn-off could result in weaker earnings visibility and slower revenue growth.”
Still, the research house is projecting earnings growth of 15.3% for this year before moderating to 10.6% in 2027. The growth is mainly driven by a 10%-12% annual revenue increase and on the assumption that the company would be able to maintain its net margin near 12%, the house noted.
Liftech also does not have a formal dividend policy, and TA Securities does not expect the company to distribute its profits to shareholders anytime soon.
“While the IPO proceeds are expected to strengthen the group's balance sheet, we still do not expect dividend distributions over our forecast period, as management is likely to prioritise reinvestment in capacity expansion and business growth initiatives,” the house added.
Read also:
Liftech, en route to ACE Market, expects RM25 mil contract win soon
Crane builder Liftech accepting applications for IPO shares at 29 sen apiece
Liftech signs M&A Securities as IPO underwriter, targets June ACE Market listing
Crane builder Liftech seeks funds from ACE Market IPO for expansions in Penang, Sabah