

This article first appeared in The Edge Malaysia Weekly on June 1, 2026 - June 7, 2026
ON Thursday morning, June 4, the world’s most audacious storyteller Elon Musk will see his flagship Space Exploration Technologies Corp, popularly known as SpaceX, begin a global roadshow with a presentation in New York to pitch its initial public offering (IPO) to investors around the world. SpaceX is hoping to raise at least US$75 billion (RM298 billion) at a valuation of US$1.75 trillion. With a 15% over-allotment greenshoe option, at the very minimum SpaceX could raise US$86.2 billion. It will be the biggest IPO ever. Right now, the demand is such that Wall Street insiders are whispering about a total capital raise of over US$100 billion and a valuation that’s north of US$2 trillion. If all goes well, the SpaceX stock will likely begin trading on the tech-heavy Nasdaq bourse on June 12, just 16 days before the 55th birthday of founder Musk who will officially become a trillionaire as soon as SpaceX shares start trading.
Regular readers of this column have probably read some of the stuff I have written about SpaceX and Musk. There is no shortage of rave reviews of the SpaceX IPO on the internet, with sweeping proclamations about the universe as well as excruciating details about SpaceX’s “mission to make life multi-planetary, understand the true nature of the universe, and extend the light of consciousness to the stars”, so I won’t try to regurgitate any of it. Frankly, my brain doesn’t have the bandwidth to comprehend much of that. If you want to get more granular, I recommend reading the 380-plus page prospectus just by googling “SpaceX S-1 SEC.gov”.
For my part, I will try to focus on a jargon-free explanation of what SpaceX actually is, how it makes money, what the humongous IPO means as well as what comes next.
If you break it all down to the basics, SpaceX is essentially a telecommunications company with a side space launch business and huge investments in xAI — a very expensive, bleeding edge start-up that is going nowhere fast. The telecom business or the Starlink part, which is mainly more than 10,000 low earth orbit satellites that provide broadband connections to over 10.3 million subscribers across 164 countries, accounts for most of the firm’s revenues. While 10.3 million broadband customers might not sound like a lot, it is almost as many as the broadband customers that US telecom giant AT&T has.
For now, Starlink’s operating profits are not enough to subsidise the loss-making parts like its space launch segment or to fund tens of billions in infrastructure spending for its xAI start-up that includes chatbot Grok and X, which Musk wants to turn into a financial super app.
Here’s how SpaceX became an enterprise worth nearly US$2 trillion: Until the 2010 launch of its first Falcon 9, a partially reusable, two-stage-to-orbit, medium-lift launch vehicle, rockets were discarded after launch. That’s like throwing away a jumbo jet after a flight from Asia to Europe or the US. National Aeronautics and Space Administration, or NASA, rocket launches used to cost US$18,500 per kilogram. SpaceX cut it down 85% to US$2,700 per kg with its Falcon 9. One Falcon 9 rocket has been reused 34 times. Musk has vowed to eventually cut launch costs up to 99% below pre-2010 NASA costs.
Once you drastically cut down launch costs, space-based businesses that were not economically viable would suddenly look affordable. “Reusable rockets are poised to create a US$160 billion market opportunity,” notes tech fund management firm ARK Invest. Take the rollout of fast internet service on commercial flights over the past few years. I regularly fly from North America to Asia and Europe. Until three years ago, inflight internet was slow, cumbersome and incredibly expensive and often only available to business and first class passengers. These days, on most full service airlines, it is ubiquitous, easy to use, almost as fast as anything on earth and for the most part free for all passengers. Fast satellite broadband also enables Live TV on flights. Satellite bandwidth costs have fallen from US$1 million per Gbps seven years ago to about US$10,000 per Gbps now and are likely to fall to around US$100 per Gbps by 2035. Starlink, or the connectivity or the telecom part of the SpaceX business, had an operating profit of US$4.4 billion on revenues of US$11.4 billion last year with a 39% operating margin. The challenge for SpaceX is convincing wary investors that data centres in orbit or eventually a Mars colony could be viable as well.
Unfortunately, competition is coming for Starlink. Amazon Leo (formerly the Project Kuiper unit of the e-commerce and cloud behemoth) will begin in mid-2026 in the US with over 300 satellites already in orbit. Even before Amazon’s launch, Starlink’s average revenue per user has been declining due to the push into emerging markets and mobile customers. The bet is that volume and network efficiency would outrun price compression. The risk is that competition makes the compression structural and erodes margins. That’s a big problem since Starlink’s high margins underwrite the IPO valuation.
The other part of the SpaceX space business is its launch business. Falcon 9, which has put over 10,000 satellites into low earth orbit, is its main workhorse. There is also Dragon, a partially reusable spacecraft for flights to the International Space Station and private spaceflight missions.
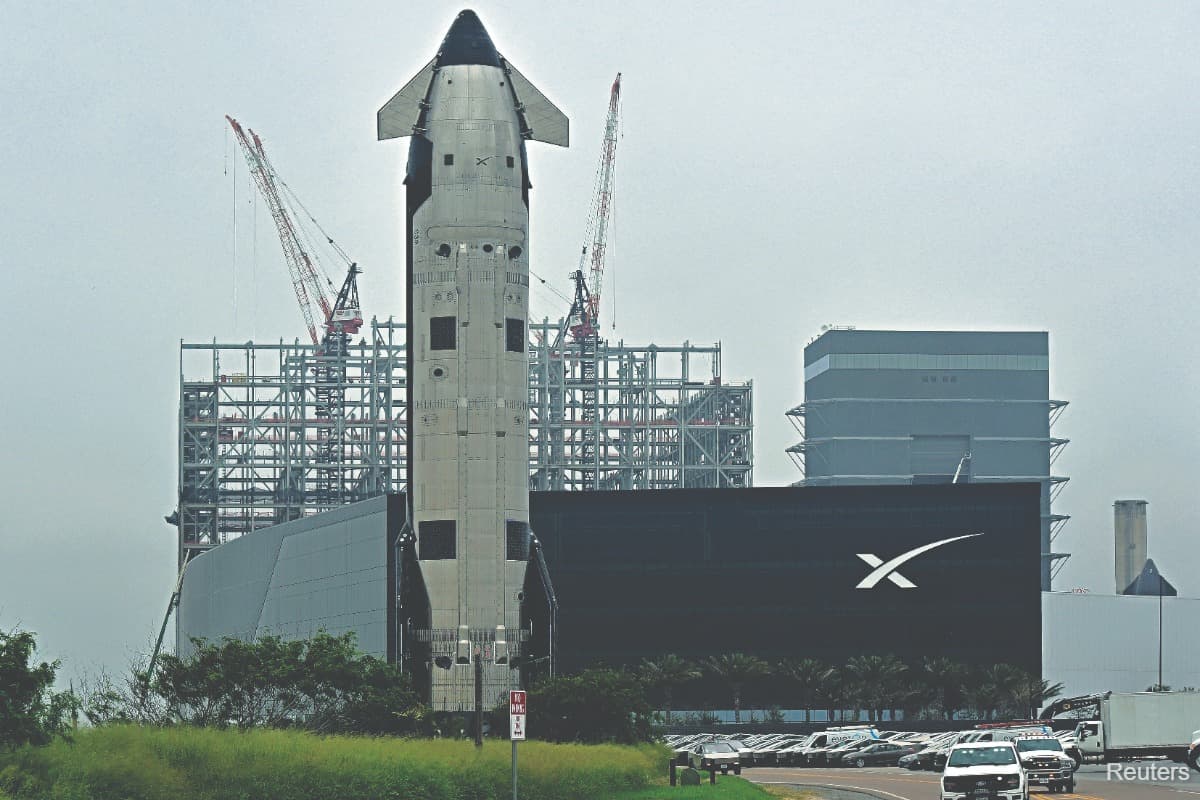
A key growth opportunity is Starship, a next-generation fully reusable super-heavy vehicle designed to carry roughly five times more payload per launch. On May 22, SpaceX successfully test-launched a Starship rocket a day after an initial test was aborted. SpaceX says eventually Starship will be used to reach the Moon and Mars. An estimated US$15 billion has been spent on developing Starship, which has a potential payload capacity of 100 tonnes, or five times larger than Falcon 9. Once it succeeds in launching such high payloads, it would make building data centres in space more practical. The space segment registered an operating loss of US$0.7 billion last year. This segment funded US$3 billion of Starship R&D in 2025 and another US$930 million in the first quarter of 2026, and accounts for just over a fifth of SpaceX’s total revenues.
By far the most controversial part of the SpaceX business and the one most scrutinised by IPO investors is its artificial intelligence (AI) segment, which includes xAI, its AI lab that directly competes with Anthropic and OpenAI; Grok, its frontier chatbot model that competes with Anthropic’s Claude and ChatGPT; and X, formerly Twitter, which is now officially the distribution and data layer of SpaceX. There is huge compute infrastructure underneath it which includes Colossus and Colossus II in Memphis, Tennessee, which have a combined 1.0 gigawatt of training capacity. Revenue for its AI segment comes mainly from advertising (through X), subscriptions to Grok/X, and more recently selling AI compute capacity. Two years ago, X started building data centres for Grok, its consumer-facing AI chatbot. Grok leverages the information stream — about 350 million daily posts — from Twitter/X to provide real-time responses to user queries. SuperGrok has 1.9 million paid subscribers compared to ChatGPT, which has about 50 million paying subscribers.
Anthropic to the rescue
Just when some investors were starting to write off the SpaceX IPO because of huge losses at its AI segment, Musk sprang a surprise. Three weeks ago, he sealed a deal with Anthropic, the leading AI frontier lab beast known for its disruptive Claude chatbot, to provide access to its compute capacity. Anthropic will pay SpaceX US$1.25 billion per month or US$15 billion a year through May 2029. That’s a huge jump for its AI segment, which until now had annual revenues of US$3.2 billion. Cash from the Anthropic deal helps underwrite the buildout of the SpaceX AI segment, with a total of US$45 billion of contracted revenue from a direct Grok competitor renting xAI’s clusters. It also gives IPO investors the illusion that the AI segment is not merely a cash incinerator.
Building data centres is, of course, highly capital intensive. Even though it makes up just 17% of SpaceX’s revenues, SpaceX’s AI segment accounts for 87% of its total capital expenditure. Yet space-based data centres could make a whole lot of sense, particularly if launch costs continue to fall. For one thing, they would have unlimited solar power. Forget about cloud cover or night-time in a sun-synchronised orbit. They would also not require much water. Moreover, they would avoid much of the current societal backlash around data centres.
But what does all this mean? Segments as disparate as broadband connectivity, space launches and AI under a single umbrella makes little sense to investors staring at huge capex commitments and losses in the AI segment. So, the SpaceX prospectus explains how it integrates all of the parts together. Grok trains on X’s 350 million daily posts. X gets AI-native features. SpaceX provides the connectivity backbone. And two years from now, or a little later, AI compute satellites in sun-synchronous orbit would theoretically take energy-intensive inference workloads off earth’s grid entirely.
Here’s how SpaceX compresses its complex model to a single loop. Reusable rockets make Starlink possible. Starlink generates the cash. The cash, in turn, funds Starship, AI infrastructure and eventually, a long way down the road, conquering and colonising Mars. Each layer depends on the one below it working. And, oh, each segment has a dierent job. Space lowers the cost of getting to orbit. Connectivity converts that access into recurring cash flow and AI is what the cash gets spent on to build the next platform.
By its own admission, SpaceX has spent massive amounts of money, which has only resulted in ever higher losses — US$4.9 billion loss on revenues of US$18.7 billion last year and US$4.3 billion loss on revenues of US$4.69 billion in the first quarter of this year. But the number that really stands out is in the cash flow statement. In the first quarter of 2026, SpaceX spent US$10.1 billion on capex, compared to cash flow from operations of just US$1.04 billion. That means SpaceX had a free cash burn of US$9.1 billion in the first quarter. “We have a history of net losses and may not achieve profitability in the future,” the prospectus solemnly states. “We face a number of challenges relating to our business and growth strategy,” the prospectus concedes. To realise its vision, SpaceX will have to continue to pour more money into experimental and unproven technologies. However, these big swings, which are core to its business, may simply not work out: “Many of the innovative products and services may ultimately be unsuccessful and may require great expense.”
Such disclosures accounting for potential future risks and the uncertainty of guaranteed revenue are of course standard in IPO filings. Underwriting bankers as well as law firms and accounting firms, who help take companies public, want to shield themselves from blame just in case everything unravels.
SpaceX-Tesla merger?
What’s next for SpaceX? Peter Diamandis, an early investor in SpaceX, believes “it is not a matter of if, but when” SpaceX will merge with Musk’s pioneering electric vehicle firm Tesla, which is pivoting towards robotaxi services through its Cybercab and Optimus humanoid robots. A SpaceX-Tesla merger has been talked about within Musk’s close circle of friends for more than a year now. Veteran tech strategist Dan Ives of Wedbush Securities has put the odds of a merger at “80% to 90%” by early 2027. While that timeline might be too fast even for someone like Musk, there is little doubt that the world’s richest man would rather run a single giant conglomerate that makes robots, robotaxis, rockets and runs data centres in space than a bunch of interconnected entities.
As trading begins on June 12, index funds will be forced to buy a huge chunk of SpaceX shares because of its early inclusion in the indices. With a small free float, initially SpaceX shares may have nowhere to go but up. In the long run, how the stock does will depend on Musk’s legendary storytelling abilities. Will he be as effective a pied piper shepherding shareholders to the promised land as he was at Tesla? Only time will tell.
Assif Shameen is a technology and business writer based in North America
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.