

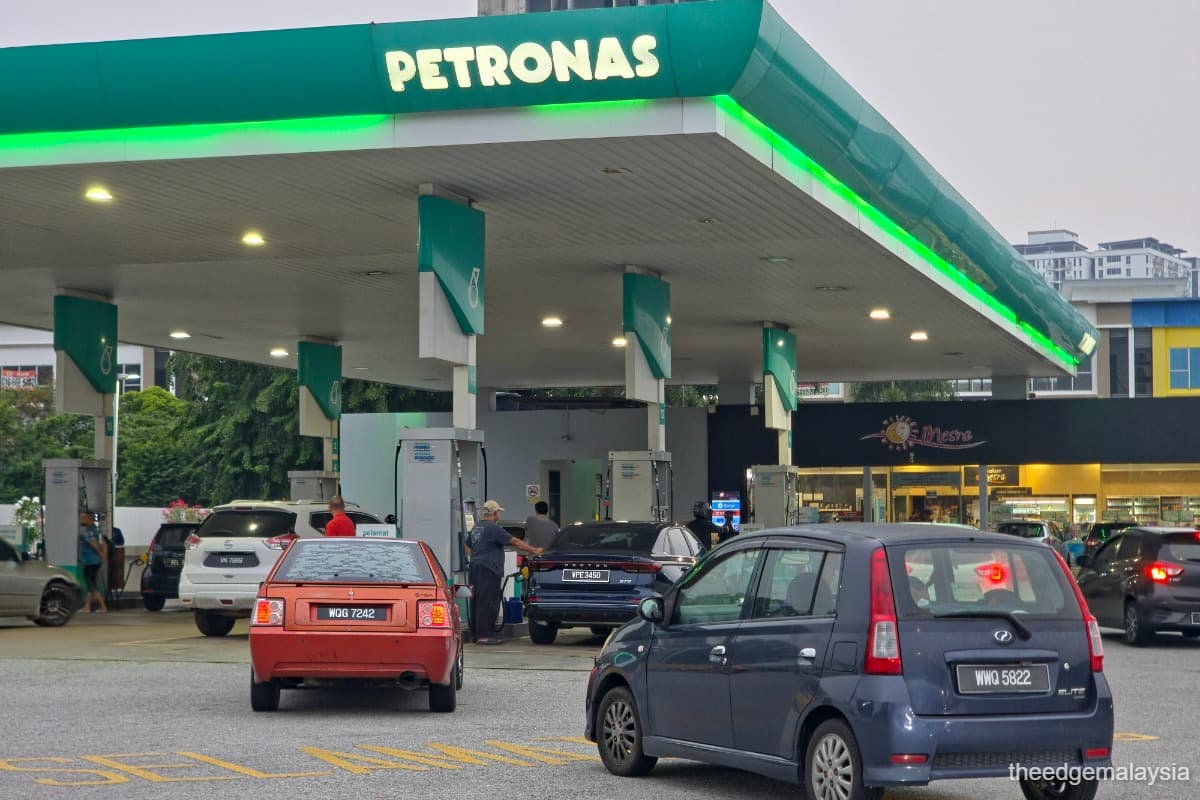
KUALA LUMPUR (June 3): PETRONAS Dagangan Bhd (KL:PETDAG) shares climbed in early trade after at least four research houses upgraded the stock.
Analysts, including RHB Investment Bank, said the recent decline in share price has created a compelling buying opportunity and value for PETRONAS Dagangan.
RHB, which holds the most bullish view so far, upgraded the stock to 'buy' from 'neutral', keeping its discounted cash flow (DCF)-derived target of RM22.37 with 26% upside and 6% yield.
"Despite softer earnings, we upgrade the stock following the recent share price weakness, which has resulted in a more compelling risk-reward profile.
"We continue to favour PETRONAS Dagangan for its resilient retail earnings, attractive dividend yield, and defensive earnings profile amid a volatile operating environment," it said in its note on Wednesday.

PETRONAS Dagangan shares hit an intraday high of RM18.84 before paring some gains to close at RM18.60. At its last price, the group’s shares were up 86 sen or 4.85%, valuing the company at RM18.5 billion.
RHB expects earnings to remain resilient in the financial year ending Dec 31, 2026 (FY2026), supported by stable domestic fuel demand, sustained tourism activities, and continued growth in PETRONAS Dagangan’s retail ecosystem.
At current levels, the stock is trading at 15 times FY2026 price-to-earnings ratio (PE) with a prospective dividend yield of 6%, which RHB views as attractive given PETRONAS Dagangan's net cash position and resilient retail earnings.
The house believes current valuations have largely priced in concerns over commercial margin weakness, oil price volatility, and longer-term electric vehicle adoption risks.
Kenanga Research, in a separate note, upgraded the stock to 'outperform' from 'market perform' while maintaining a DCF-based target of RM21.20.
The research firm believes the 16% drop in share price is overly steep, as it already reflects a potential T20 subsidy removal, given this segment approximates 16% of its overall business volume.
"Moreover, we see this risk as transient, as historically upon any subsidy removal a knee-jerk reaction on volumes will materialise before normalising longer term," it said.
Kenanga likes PETRONAS Dagangan for its highly cash-generative business that translates to high capacity to pay dividends, still growing commercial volumes, and growing convenience division revenue on stronger demand for Café Mesra.
Separately, Hong Leong Investment Bank (HLIB) upgraded the stock to 'buy' from 'hold', raising its target price to RM21.34.
"Following the recent share price correction, partly due to its MSCI Malaysia Index removal and weaker commercial outlook, PETRONAS Dagangan now trades at an attractive 15.8 times FY2027 PE with 6% dividend yield," it said in a note on Wednesday.
HLIB noted that PETRONAS Dagangan's first quarter of 2026 (1Q2026) core net profit was broadly within estimates, with retail earnings before interest and taxes (Ebit) surging 2.7 times, supported by favourable reimbursements under the Automatic Pricing Mechanism (APM) mechanism amid higher oil prices, offsetting the sharp decline in commercial Ebit.
The house remains constructive on PETRONAS Dagangan’s overall outlook despite near-term pressure on the commercial segment from softer sales volumes and the temporary lag in passing through elevated jet fuel inventory costs.
CGS International upgraded the stock to 'add' from 'reduce', maintaining a dividend-discounted model (DDM)-based target of RM19.09 — the lowest target among the four research houses.
The upgrade follows the steep share price fall, with dividend yields now attractive at 7%.
CGS noted that 1Q2026 core net profit was in line at 24%-25% of forecasts, with retail Ebit rising substantially quarter-on-quarter (q-o-q) due to favourable timing differences of inventory purchases versus sales in a rising oil price environment.
For 2Q2026, the house expects PETRONAS Dagangan’s retail Ebit to decline q-o-q but for its commercial EBIT to rise q-o-q, reversing the trends seen in 1Q2026 as Mean of Platts Singapore (MOPS) prices for motor gasoline, diesel and jet fuel decline.
"The overall 2Q2026 core net profit may decline slightly q-o-q, in our view, as sales volume for jet fuel may be negatively affected by the capacity cutbacks by various airlines in view of the high price of jet fuel; data from consultancy OAG forecast flight frequencies in Malaysia to fall 6% q-o-q in 2Q2026F vs the 2.3% q-o-q rise in 2Q2025," it added.
However, CGS said PETRONAS Dagangan's 2Q2026 retail sales volume was not affected even though the government had cut the quota for subsidised RON95 at RM1.99/litre from 300 litres to 200 litres on April 1, 2026, while a work-from-home directive for selected civil servants began on April 15.