

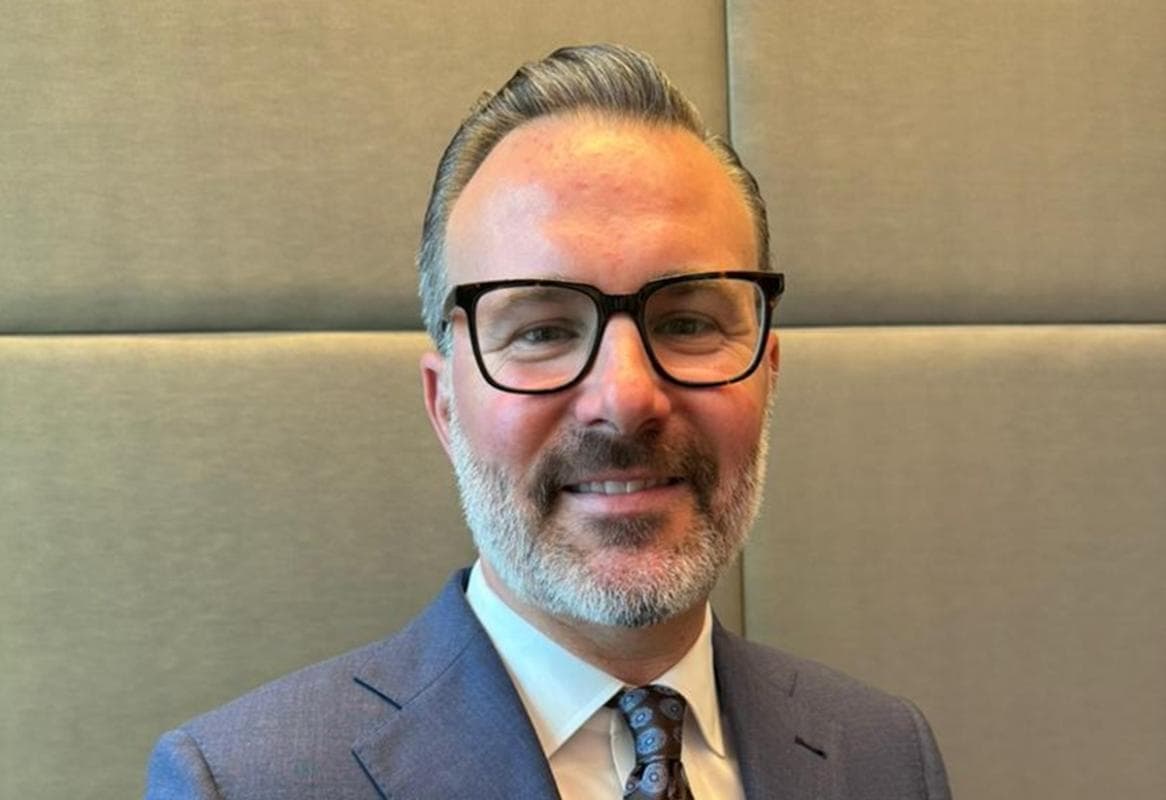
(May 26): Todd Brighton, senior vice president and portfolio manager for Franklin Income Investors, is finding 'paid to wait' opportunities in software companies and near-term tailwinds in US banks as higher yields make parts of fixed income more attractive.
Brighton, who is also a co-manager on a number of Franklin Templeton's income-oriented funds, says the fund has been looking at software companies that were sold down on fears that artificial intelligence (AI) could disrupt their businesses.
"There were some very good companies that we thought were painted with too broad of a brush and their businesses were more resilient than the market was giving them credit for," he says, adding that many of these companies have stronger competitive moats than the market is currently pricing in.
For software providers serving sectors such as financial services and healthcare, where regulatory and reputational risks are high, enterprises are likely to continue paying for software that is proven, embedded in their systems and integrated into their technology stacks, rather than quickly replacing it with AI-generated or "vibe-coded" alternatives. In these areas, data privacy and customer records are extremely sensitive, and the consequences of software failure can be severe.
That being said, it may take several quarters for these companies to prove that AI is not materially disrupting their businesses, making it a "paid to wait" opportunity. In the meantime, the fund can seek to generate income through instruments such as equity-linked notes while waiting for the investment thesis to play out.
"It's hard to disprove that something's not going to be disruptive to your business. That's going to take multiple quarters for them to continue to show earnings, continue to show earnings growth. That may be one that is a multi-year story for that to really play out," says Brighton.
Brighton says the fund has also been focused on large US banks, which entered the year with several earnings tailwinds. These include a stronger pipeline of initial public offerings, increased merger and acquisition activity and a steepening yield curve, all of which are supportive of bank earnings. Market volatility could also help trading revenue, while fundraising linked to the AI data centre build-out could create further opportunities for banks.
"On the fixed income side, we've broadly been using investment grade corporate bonds as a source of funds for the last couple of years. I think it's gone from 15% of the portfolio a year ago to more like 10% today as spreads have continued to come down. Interest rates have been relatively stable in this 4% to 5% range," says Brighton.
"More recently, we've seen spreads widen a little bit. We've seen the 10-year move up into the top half of that 4% to 5% range. So, the yields available within the higher quality areas of fixed income are some of the most attractive they've been in the last couple of years." Franklin Income is a diversified multi-asset income fund that draws on different sources of income across asset classes. The strategy is active and flexible rather than tied to a fixed allocation, meaning the fund has wide latitude to invest across fixed income, equities and sub-asset classes depending on where the team sees opportunities.
In Malaysia, the strategy is accessible through the AHAM World Series — Income Fund, a feeder fund managed by AHAM Asset Management Bhd that invests in the Franklin Income Fund as its target fund. As at April 30, its top five holdings were US Treasury Bond (6.5%), Community Health Systems Inc (2.7%), Government National Mortgage Assn (2.2%), Exxon Mobil Corp (2.1%) and Procter & Gamble Co (1.9%).
Brighton adds that the AI capital expenditure build-out remains the biggest theme in the US market, but the opportunity is starting to broaden beyond the semiconductor companies that have led the rally, such as Nvidia, Broadcom, AMD and Marvell.
Brighton expects such a broadening trend to continue through the rest of the year and beyond. This includes utilities that are needed to power data centres, as well as non-residential construction companies involved in building the infrastructure behind the AI boom.
"I think probably the next wave is going to be the productivity benefits from AI to a broader swath of industries. You're going to see productivity start to filter through into many other
sectors. That's more of our focus today, as opposed to chasing a handful of companies that have had really strong performance already," says Brighton.
AI has become an important part of the fixed income market as well, with hyperscalers raising large amounts of capital to fund AI-related investment. Three of the top 10 issuers in the investment-grade market are now hyperscalers: Amazon, Alphabet and Meta.
The main concern around AI is that much of the optimism may already be reflected in share prices, especially after the strong rebound in semiconductor stocks since April, says Brighton. He points to Nvidia's blockbuster quarterly earnings, which received only a muted response from the market, as a sign that expectations are already high.
For some AI-linked stocks to keep rising, he says investors may need to see growth accelerate even further from current expectations.
Inflation spike largely seen as transitory
A major talking point for investors has been the closure of the Strait of Hormuz, amid the ongoing war in Iran and broader supply chain disruptions in the Middle East. Brighton says the duration of the disruption will determine how much it filters through to corporate earnings and the broader US economy.
For now, the US is a much larger oil producer than it was during previous episodes of oil price spikes and supply disruption, which could help cushion US companies from some of the impact. But if the strait remains closed into the second half of the year, he says the effects could become more material, with companies potentially facing pressure on profit margins if they have trouble sourcing inputs.
That said, Brighton notes that US corporate profit margins are at all-time highs and still rising, giving companies some room to absorb higher costs or pass them on through price increases. The supply disruptions have already begun to spread beyond energy and crude oil into chemicals, which has created risks as well as opportunities, with some chemical companies emerging as beneficiaries.
Inflation has been a major theme for markets, especially given the geopolitical tensions and higher energy prices. But Brighton says the impact so far has been narrow, showing up mainly in energy and in some pockets of materials, rather than in stickier categories such as wage inflation.
"We are more of the belief that the markets are going to look through this as more of a transitory inflationary spike, rather than a really durable inflationary spike like we saw in 2022, where you have wage inflation and things like that that are really driving it," says Brighton.