

KUALA LUMPUR (May 21): Bumi Armada Bhd’s (KL:ARMADA) first-quarter net profit fell 78% to RM40.1 million mainly on lower contributions from two floating production storage offloading (FPSO) vessels, including the Armada Kraken.
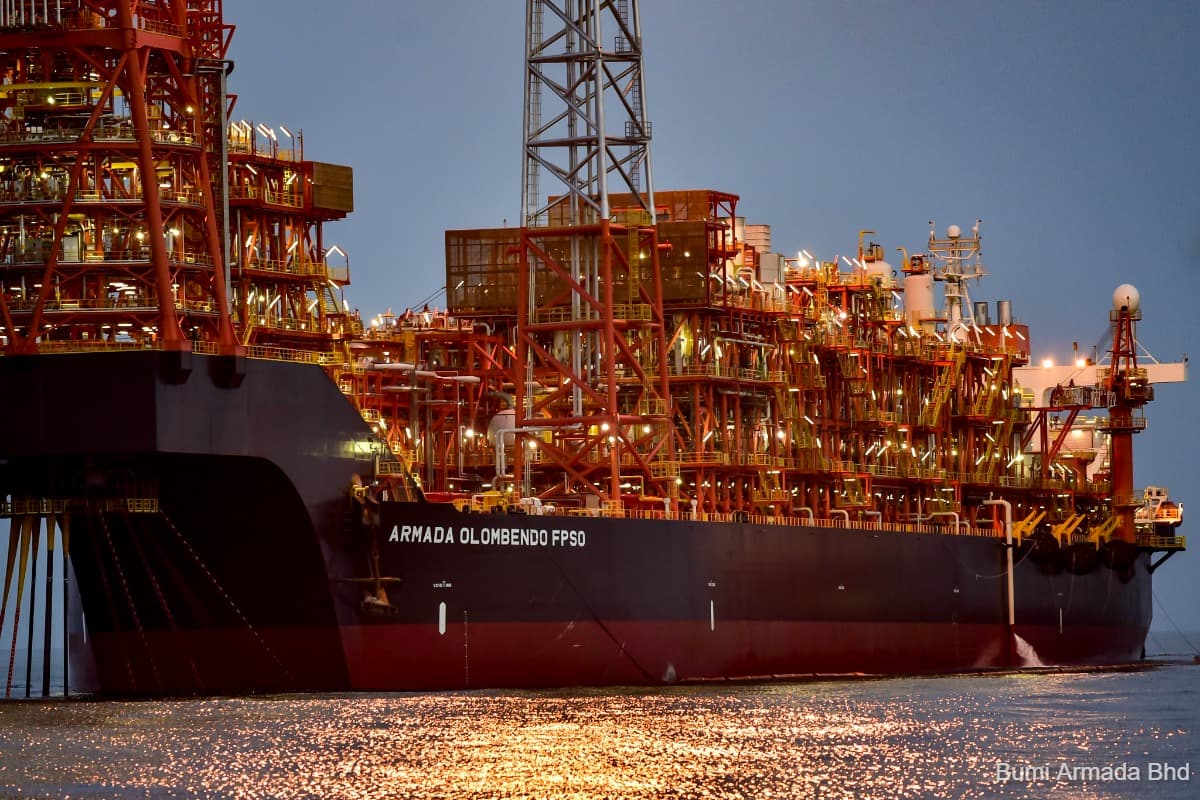
A year ago, the offshore oilfield services provider made a net profit of RM182.77 million. The squeeze on net profit was mainly driven by a 35.32% decline in revenue, resulting from a lower charter rate for the Armada Kraken compared to 1QFY2025, as well as lower finance lease revenue from the Armada Olombendo FPSO vessel, which was partly offset by reduced finance costs.
Revenue for the quarter ended March 31, 2026 (1QFY2026) was down to RM306.56 million from RM473.97 million the year before, according to a bourse filing on Thursday.
No dividend was declared for the quarter. Earnings per share fell to 0.68 sen from 3.08 sen in 1QFY2025.
Despite reporting a lower net profit, Bumi Armada generated a strong net cash flow from operating activities of RM191.53 million. The company’s chief financial officer Luke Targett highlighted in a separate statement that it used these funds to prepay its unsecured corporate debt, ensuring that the next principal repayment is not due until December 2027.

Looking ahead, Bumi Armada remains committed to bidding for new projects and securing charter extensions, while maintaining high standards for asset safety, vessel efficiency, and client relationships in line with its sustainability goals.
‘’Finance lease accounting (applicable to certain of our vessels) generates higher upfront profit than cash flow. This timing difference reverses over time. Accordingly, reported revenue will remain below charter cash inflows and we expect that this will continue,’’ the group said in its commentary on the company’s prospects in the Bursa Malaysia filing.
Bumi Armada also noted that it continues to monitor global geopolitical situations, emphasising that there has been no material adverse impact on its financial position or operational results to date.
“We have continued to operate safely across the fleet with zero LTIs (loss time injuries) in 1QFY2026. Operationally, the start of the year has been challenging with downtime impacting our results. Lessons learned have been shared across the fleet and I am confident we will continue to improve our operational performance. Importantly, our improving financial position enables us to actively bid for new projects, and the buoyant market conditions are providing good quality opportunities,” Bumi Armada chief operating officer Alexander Brigden said in the statement.
According to AskEdge data, Bumi Armada is currently trading at a price-earnings ratio of 5 times, the lowest among its peers. In comparison, Lianson Fleet Group Bhd (KL:LFG) is trading at 19.7 times, and Keyfield International Bhd (KL:KEYFIELD) at 7.3 times.
At the time of writing on Thursday, Bumi Armada shares were down one sen or 1.35% at 36.5 sen, valuing the company at RM2.16 billion.
Prior to the release of the 1Q results, Bloomberg data showed that out of 11 analysts coverage, nine have ‘buy’ calls on the stock and two have ‘hold’ calls. The average 12-month target price is 47 sen per share, with target prices ranging from 32 sen to 66 sen.