

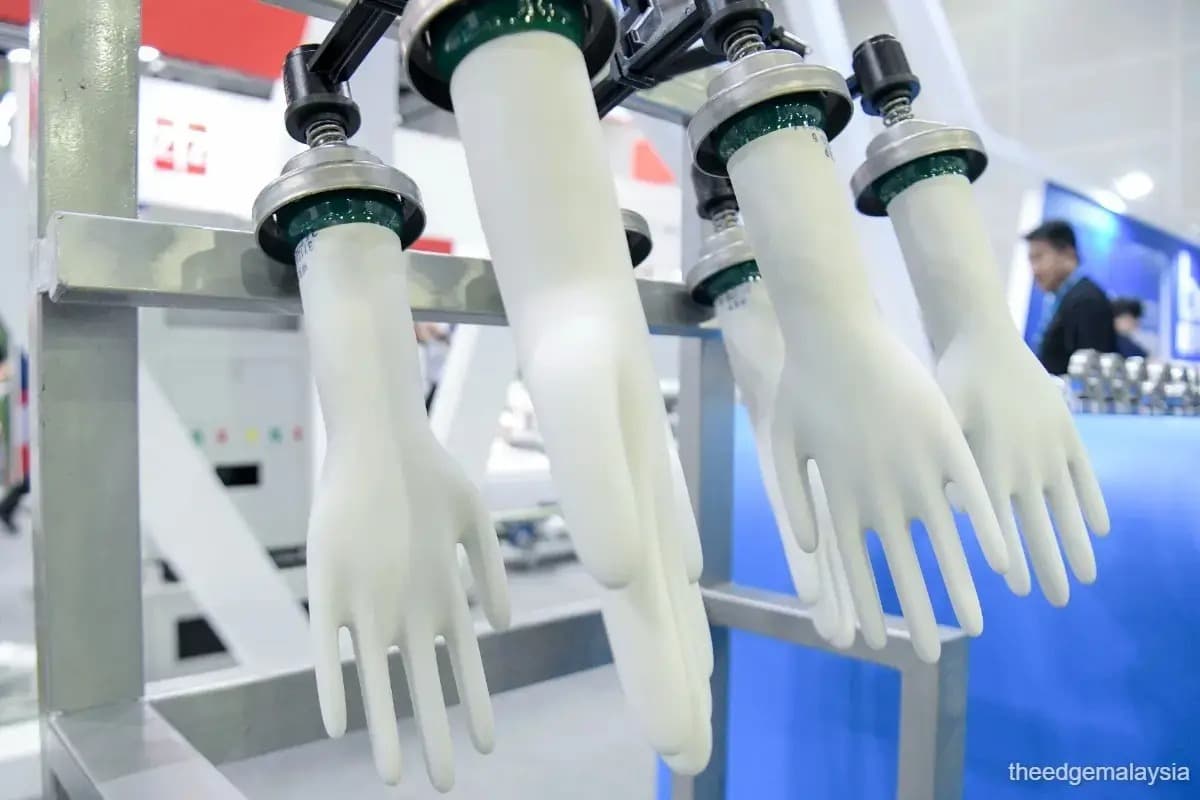
KUALA LUMPUR (May 8): NewParadigm Research in a note on Friday said it expects glove makers’ earnings to double in one to two quarters on glove makers' unique opportunity to raise prices above and beyond direct cost impacts.
This is supported by industry-wide price adjustments, US tariffs limiting Chinese imports, and delayed increases in gas costs for producers.
The research house is more optimistic than the market, forecasting 60%–80% higher earnings for glove makers because it believes they can raise selling prices despite higher nitrile costs. However, it also notes that prices and costs remain volatile and assumes a 5% drop in demand. While the market is cautious due to recent data showing glove prices fell in March. However, nitrile material costs have clearly increased.
NewParadigm believes most market forecasts focus on sales volume instead of price increases and have not fully included profit margin improvements. It expects that as earnings improve over the next two quarters, glove company valuations will likely rise as well.
Since the closure of the Strait of Hormuz, the nitrile prices have surged as the closure disrupted naphtha supply flows into Asia. Nitrile, which makes up roughly 40% of glove production costs, is derived from naphtha.
Malaysian glove makers source around 65% of their nitrile requirements from South Korea, which itself relies heavily on Middle Eastern naphtha imports.
NewParadigm estimates nitrile prices have risen about 60% on average since the conflict began. Still, the research house noted that the entire global glove industry, including Chinese competitors, is facing similar cost pressures, too. This allows Malaysian manufacturers to pass higher costs to customers more effectively, it added.
“Demand for medical disposable gloves is non-discretionary in nature,” NewParadigm said, adding that substitution to latex gloves is not viable because of allergy risks and the natural rubber gloves also tend to be less durable and not suitable for all applications.
The sector’s pricing power is also being strengthened by the US’ Section 301 tariffs on Chinese glove imports, which have effectively priced low-margin Chinese gloves out of the US market. Malaysian manufacturers now account for more than 60% of US glove imports by volume, while China’s market share has fallen to below 10% from over 30% previously, the house added.
“The bias for conservatism and the “wait and see” approach present an opportunity — once the earnings delivery trickles in, the upgrades to expectations could spur a more substantive rerating for valuations as well,” NewParadigm added.
It said that since the Covid-19 boom years, analysts have not significantly raised their earnings forecasts in the middle of the year.
The firm estimates that Top Glove Corp Bhd (KL:TOPGLOV) could see net profit almost double sequentially, while Hartalega Holdings Bhd (KL:HARTA) could record around 60% sequential earnings growth.
Shares of major Malaysian glove manufacturers rebounded on Friday morning, with Top Glove, Hartalega and Kossan rising between 6% and 8%. The gains coincided with the market reaction to reports of a hantavirus outbreak in South America.
CSG International Research analyst William Wo said it maintains a cautious view on the sector after noting that the World Health Organization had described the Andes strain as having a fatality rate of about 35%, although human-to-human transmission remains rare. Symptoms include fever, chills and breathing difficulties that may only appear several weeks after infection.