

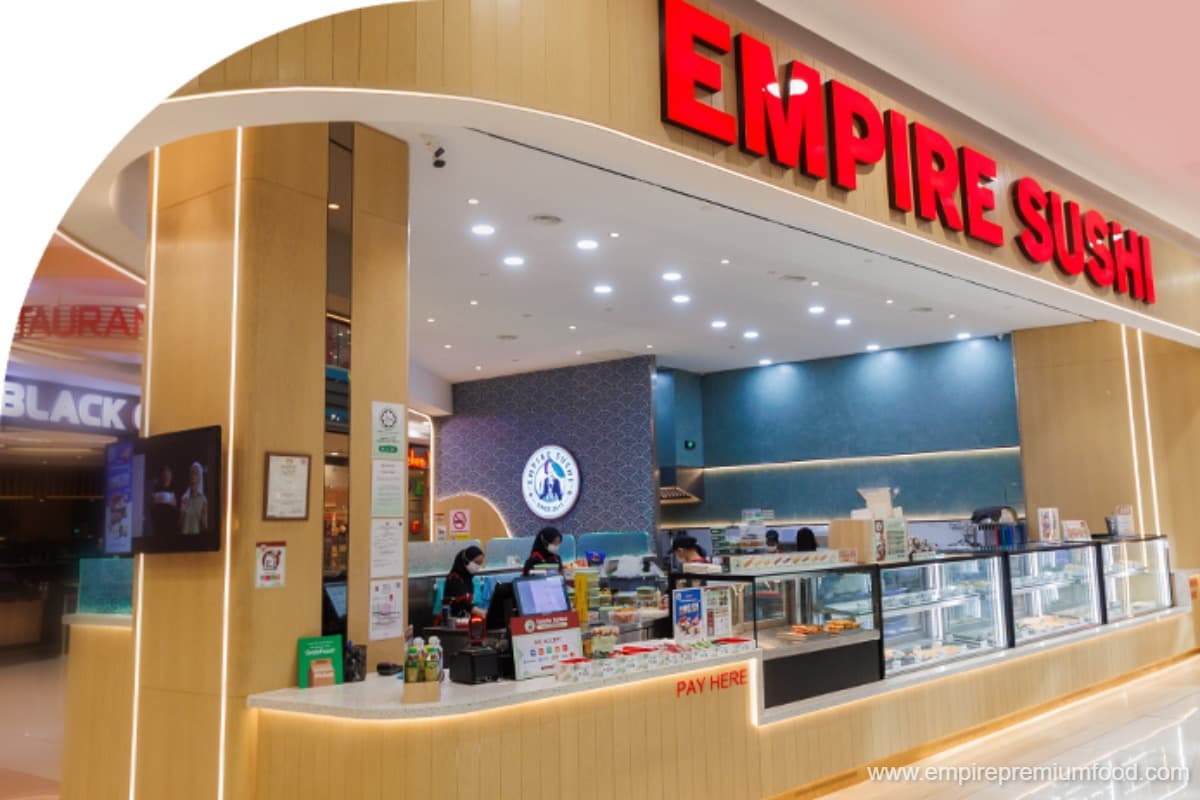
KUALA LUMPUR (May 8): Empire Premium Food Bhd (KL:EMPIRE) is drawing more interest and analyst coverage with CIMB Securities being the latest to initiate with a "buy" and RM1.36 target price, citing undemanding valuation and positive growth prospects.
The company, which operates the Empire Sushi takeaway chain, was among the top gainers on Bursa Malaysia following the initiation, with CIMB Securities' target price translating to nearly 50% upside.
The stock rose as much as 10.38%, or 9.5 sen, to RM1.01 on Friday, compared with Thursday's closing price of 91.5 sen.
At midday market break, however, the stock pared some gains to trade at 99.5 sen, still up 8.74%, or eight sen.
The stock remained above its initial public offering price of 70 sen following its listing on Bursa Malaysia’s Main Market on April 17.
The only other research house covering the stock is Affin Hwang Investment Bank that also has a 'buy' call with lower target price of RM1.07, Bloomberg data show.
In a report released on Friday, the research house said the company’s valuations are undemanding, supported by the company’s superior earnings growth, strong profitability, and scarcity value as a listed shariah-compliant pure-play affordable food service growth story.
The stock trades at 15.4 times CY2027 forecast earnings, while CIMB’s target price is based on a 23 times CY2027 price-earnings ratio, broadly in line with Bursa-listed consumer companies with retail food and beverage exposure.
The research firm expects the group to deliver a three-year compound annual growth rate in core net profit of 21.5% from FY2025 to FY2028. This is underpinned by a robust outlet rollout plan and same-store sales growth (SSSG) of 5.5% for FY2026 and 2.5% growth for FY2027 and FY2028, respectively.
Brand-building activities will support the company’s SSSG, store refurbishments plans to refresh customer experience, and innovation-led menu development to keep offerings fresh, it added.
According to CIMB Securities, the moderation in SSSG from 12.2% in FY2023 to 5.5% in FY2025 should not be viewed negatively, as it mainly reflects outlet densification rather than weaker consumer demand.
Empire Premium is currently Malaysia’s largest grab-and-go sushi chain operator, with 143 outlets nationwide as at Feb 25, 2026, comprising 127 grab-and-go outlets and 16 quick dine-in outlets.
“We view Empire Premium as a compelling proxy to Malaysia’s affordable food service segment, anchored by its position as the country’s largest grab-and-go sushi chain and category leader in affordable Japanese QSR,” said CIMB Securities.
It also highlighted that Empire Premium’s halal-certified operating model is an important strategic advantage that supports its domestic growth runway.
“The group is well-positioned to serve Malaysia’s Muslim-majority market at scale, particularly within the affordable, convenience-led dining segment. In our view, this matters because halal compliance at scale is not easily replicated,” it added.
CIMB Securities noted Empire Premium strong profitability, saying that the group posted a FY2025 profit after tax margin of 16.1%, significantly above its peer average of 6.9%.
In addition, CIMB Securities said Empire Premium's balance sheet remains healthy with a net cash position and no interest-bearing debt apart from lease liabilities amounting to RM20.6 million.
The research house said the company’s strong net cash position is sufficient to support its capex assumptions, primarily to fund new outlet openings.