

This article first appeared in The Edge Malaysia Weekly on April 27, 2026 - May 3, 2026
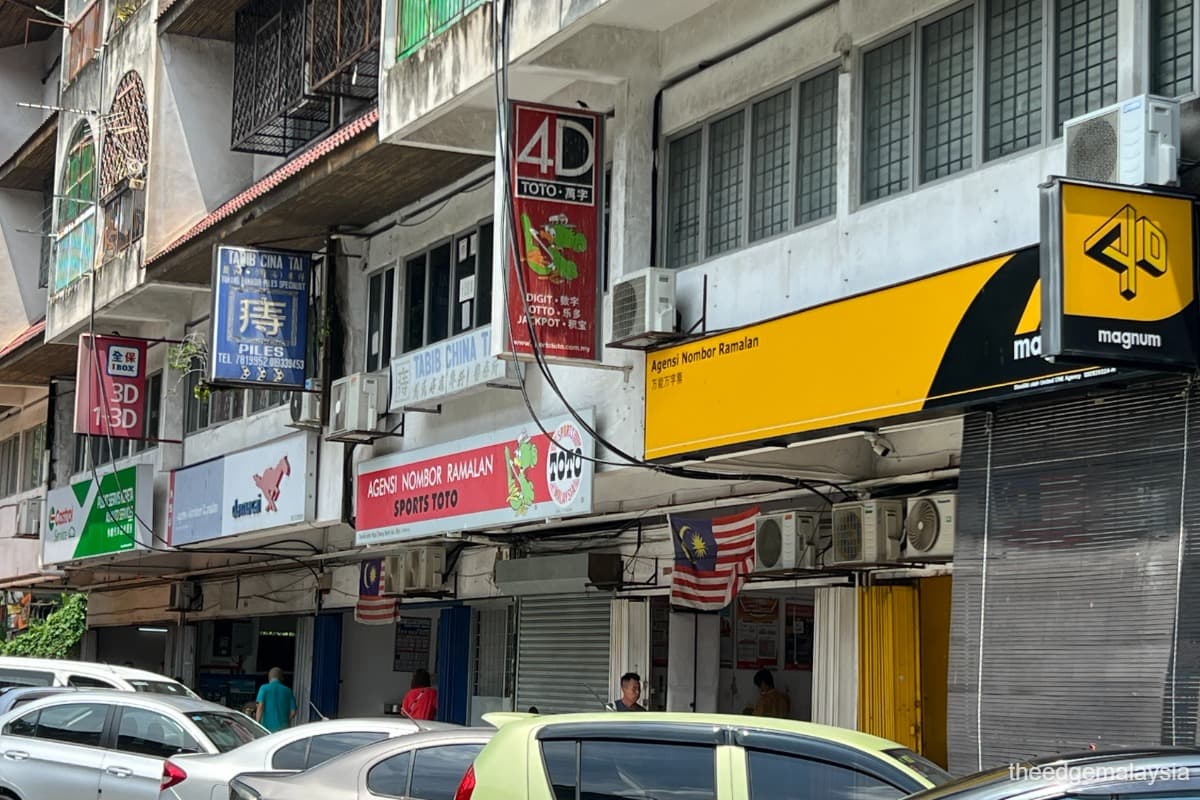
EVEN with attractive dividend yields of 7%, Malaysia’s number forecast operators (NFOs) are struggling to win back investors.
Once considered recession-proof and a staple of investing portfolios given their relatively defensive nature, the NFOs’ market capitalisation has shrunk over the last decade as structural headwinds outweigh their steady payouts.
Magnum Bhd (KL:MAGNUM) has seen its market cap drop from an average of RM2.5 billion in 2016 to about RM1.84 billion presently, based on its April 23 closing share price of RM1.28. As for Sports Toto Bhd (KL:SPTOTO), its market cap has slid from RM3.8 billion in 2016 to about RM1.74 billion, with its share price closing at RM1.29 on April 23.
Both Magnum and Sports Toto have indicative dividend yields of 7.03%, according to data from Bloomberg.
Can the sector regain its lustre? Analysts suggest that expectations of the sector, which is fraught with structural and regulatory challenges, should be realistic, as growth is likely to be average going forward.
“The sector’s classic games, which are proxy to demand, have not fully recovered to pre-pandemic levels,” notes UOB Kay Hian director of strategy Vincent Khoo. He adds that while there is scope for further recovery, annual growth remains “pedestrian”.
The sector faces three primary challenges, chief of which is the shadow market that has increasingly eaten into the market share of legal operators.
Illegal NFOs have also aggressively moved online, offering not just daily draws but higher payouts and 24/7 mobile access — unlike legal NFOs, which are capped at three to four draws a week and restricted to physical outlets, notes Fortress Capital Asset Management Sdn Bhd CEO Datuk Thomas Yong. Estimates suggest that the illegal market is now at least 1.5 to two times the size of the legal industry.
The second challenge is a demographic and cultural shift. “The legal addressable market for 4D is structurally the non-Muslim population, and within that population, younger consumers are increasingly spending their discretionary time and money on online alternatives,” he says.
The operating landscape has also become increasingly restrictive due to regulatory scrutiny. Since 2023, “special draws” have been slashed from 22 to just eight per year. Further, the revocation of NFO licences in Kedah that same year fuelled fears that other states could eventually follow suit. While that development did not result in a significant dent to NFOs’ earnings, it nevertheless shook investor sentiment.
Such structural headwinds have been capping Magnum’s upside valuation, RHB Research comments in a Feb 26 report. “Any further erosion of state-level support in Selangor, Penang or Negeri Sembilan would meaningfully impair the outlet footprint. Sell-side analysis at the time of the state elections had suggested around half of combined NFO earnings could be at risk in a worst-case state-level scenario. That tail risk never fully dissipated and is being re-priced into the multiple,” says Yong.

Stagnant financials
Revenue of both major players has remained largely flat over the past decade. Excluding FY2020 and FY2021, Magnum’s revenue has hovered between RM2.03 billion and RM2.7 billion. While net profit is recovering — climbing from RM100.61 million in its financial year ended Dec 31, 2022 (FY2022) to RM166.47 million in FY2025 — it has yet to recover to pre-pandemic levesl, and remains well below its FY2019 peak of RM239.23 million.
Sports Toto, which has a financial year ending June 30, is seeing a similar trend. Its betting segment profit, which averaged RM421 million from FY2016 to FY2019, dropped by almost half during the Covid-19 years of FY2020 to FY2022. While it saw recovery in FY2023 with a segment profit of RM293.64 million, it still remained below pre-pandemic levels.
The group also operates the luxury motor dealership H.R. Owen in the UK, but the bigger portion of its earnings comes from its NFO business. Betting revenue has ranged between RM2.8 billion and RM3.3 billion, except for FY2020 to FY2022.
Amid the relatively flat revenue, cost has been rising — in the form of an expanded 8% pool betting duty, higher minimum wages and bigger prize payout ratios. Together with the regulatory risks and steep competition from illegal operators, the picture isn’t looking all that good for NFOs.
Silver lining
While industry-wide growth appears capped, analysts are pointing to a possible catalyst for Magnum, albeit a non-gaming-related one: the potential monetisation of its 7.8% stake in U Mobile Sdn Bhd.
It has been reported that the telecommunications company is planning an initial public offering (IPO). If U Mobile proceeds with its IPO plan, Magnum’s stake could see a huge valuation jump.
“That stake is currently carried in its books at around RM385 million or roughly 20 sen per share,” Yong says. That amount makes up over 20% of Magnum’s current market cap.
“If U Mobile lists at a valuation of around the RM10 billion to RM12 billion range that has been mooted in the market, the value accretion to Magnum could be meaningful, and there is a reasonable case for the stake to be distributed as a dividend-in-specie to shareholders. Magnum has done this before with MPHB Capital in 2013.”
Magnum, formerly known as Multi-Purpose Holdings Bhd, previously undertook a demerger exercise to separate its non-gaming assets into MPHB Capital Bhd (KL:MPHBCAP) and gaming assets under Magnum. As part of the exercise, it distributed MPHB shares as dividend-in-specie to shareholders.
The U Mobile IPO has been one of Corporate Malaysia’s longest-running “any day now” stories, with founder Tan Sri Vincent Tan stating in January 2025 that the company would be listed by end-2025 — a deadline that has since passed. It remains to be seen if and when it will actually materialise.
As for Sports Toto, Yong thinks the key is H.R. Owen. He believes either a divestment or a visible stabilisation in UK luxury auto demand is needed to stop the business from continuing to drag down the group’s earnings.
For now, NFOs remain a defensive yield sector for investors who are able to tolerate a lower-growth and structurally pressured business profile.
“The catalysts exist, but they are not the kind that would support a broad sector rerating. They are company-specific and somewhat binary. Note that none of the catalysts, company-specific or otherwise, addresses the demographic changes these businesses are experiencing, which structurally impairs the long-term growth story,” Yong highlights.
In other words, they may provide short-term bumps, but they do not solve the long-term demographic and digital challenges threatening the traditional 4D business model.
Magnum — with two “buy” calls and one “hold”, and a target price of RM1.52 — is trading at a forward price-earnings ratio (PER) of 10.67 times. Sports Toto, which has one “buy”, four “hold” and one “sell” — with a target price of RM1.38 — is trading at a forward PER of 11.13 times.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.