

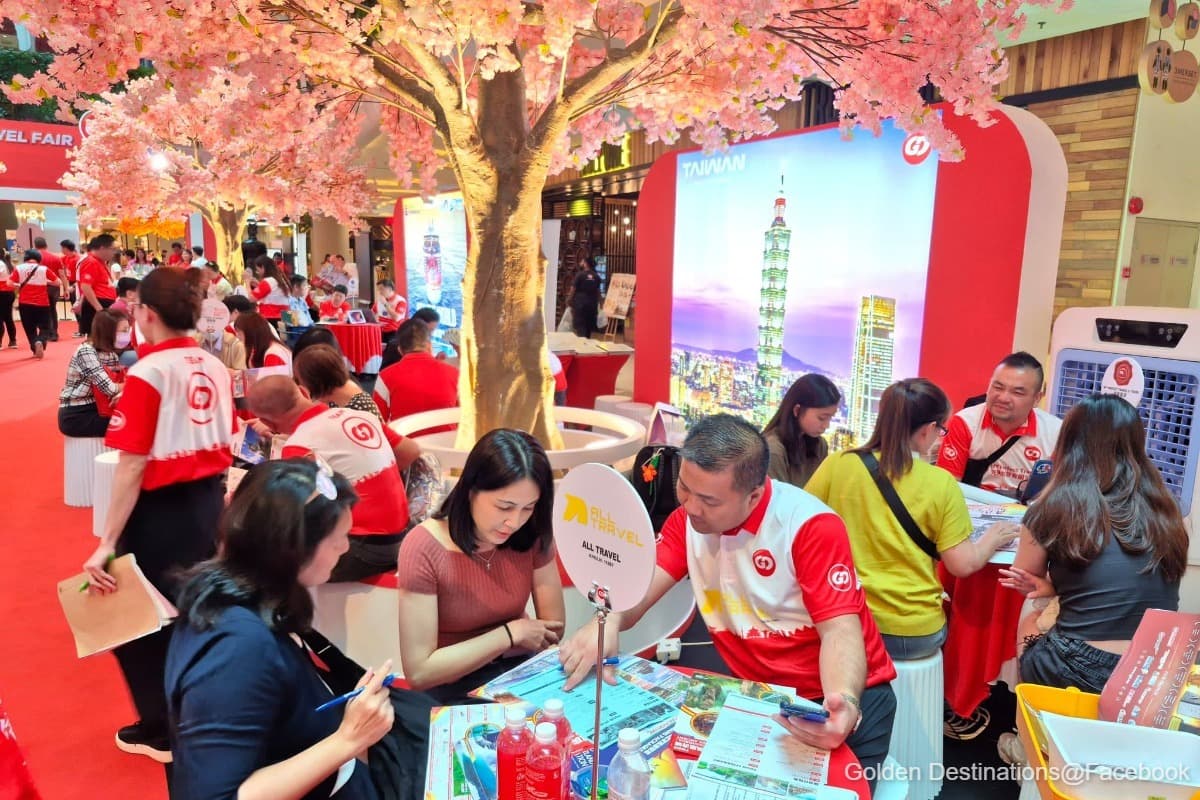
This article first appeared in Capital, The Edge Malaysia Weekly on April 13, 2026 - April 19, 2026
TOURISM firm Golden Destinations Group Bhd (KL:GDGROUP) is set to take off with its ACE Market debut on April 16, aiming to raise RM135 million through an IPO priced at 45 sen.
The timing had seemed ideal. Outbound travel from Malaysia has been gaining momentum as the stronger ringgit boosts overseas spending power. In fact, the currency’s rise to a five-year high against the US dollar has prompted Malaysians — especially travellers — to exchange early. This was expected to provide a strong tailwind for outbound travel firms like Golden Destinations.
But what looked like a perfect moment has grown more complicated. Escalating tensions in the Middle East have driven up fuel prices, pushing airlines to raise fares while adding a layer of uncertainty for global travellers.
Nevertheless, Golden Destinations, which works mainly with more than 800 travel agents across Malaysia, believes it can weather the storm. Its confidence is rooted in its heavy focus on East Asia, which generated more than 60% of its revenue last year. Its group tour model, which relies on fixed airline agreements, is also helping to insulate the company from sudden fluctuations in ticketing costs.
Unlike traditional travel agencies that sell directly to consumers, the company functions as a wholesaler, designing and integrating travel and cruise packages for a network of licensed agents. According to its prospectus, Golden Destinations is a “full-service outbound travel experience curator”.
So, while it provides standalone support services such as flight ticketing, its main role of curating, designing and integrating travel experience products, including cruise packages, positions it distinctly on the tourism value chain.

And while fuel surcharges may affect free independent traveller ticket sales, the impact on the company is limited, as it focuses primarily on group tour packages, for which airline seats are secured under contractual agreements with airline partners, Golden Destination stresses.
According to Independent Market Research, the company holds a 15.5% share of Malaysia’s outbound travel market booked through tour operators. Golden Destinations is spearheaded by its promoter, major shareholder and managing director Mita Lim Swee Kok, who has almost four decades of experience in the travel industry.
Speaking to reporters after the company’s IPO prospectus launch on March 26, Lim maintains an optimistic outlook despite the instability triggered by the war in Iran. “Today, we are seeing travel preferences shift towards Asian countries and Golden Destinations is well positioned to respond to the demand, given the breadth of our offerings across Asia and our flexibility in adapting our travel portfolio,” he says.
European and Middle Eastern destinations contributed only 13% to the company’s revenue in FY2025, he notes.
Financial snapshot
Golden Destinations has seen revenue rise from RM433.1 million in the financial year ended Dec 31, 2023 (FY2023) to RM597.5 million in FY2024, before easing slightly to RM592.4 million in FY2025. Sales of travel packages accounted for 73% of its FY2025 revenue, followed by ticketing services and other services, which contributed 27%.
Net profit jumped from RM13.3 million in FY2023 to RM31.6 million in FY2024 before moderating to RM28.4 million last year, with earnings per share (EPS) following a similar trend, reaching 2.84 sen in FY2025.
Dividend payments surged from RM3 million in FY2023 to RM30.5 million in FY2024. No dividend was declared for FY2025.
Golden Destinations’s planned listing values the company at RM450 million. Of the RM135 million to be raised, RM90 million will go to the company as fresh capital, while Lim will receive RM45 million from the offer for sale. After the listing, Lim will retain a controlling 70.15% stake.
The company has earmarked more than 88% of its public issue proceeds for expansion, including a centralised headquarters and increased marketing spend. As it grows its presence in East Malaysia and Singapore, it also plans to upgrade its IT systems and hire 90 new employees to bolster its current workforce of 280. The remaining funds will be used for working capital and listing expenses.
UOB Kay Hian is acting as principal adviser, sponsor, underwriter and placement agent for the IPO.
Analysts’ views
Research houses have offered mixed valuations for Golden Destinations, reflecting the tricky timing of its IPO.
While TA Securities has pegged its fair value at 42 sen, suggesting the IPO price is slightly overvalued, given the current geopolitical climate, Tradeview Research has issued a “neutral” rating with a fair value of 48 sen, implying a 7% upside, saying the company’s business-to-business model is lean and scalable.
“We like Golden Destinations for its B2B model, which enables a lean cost structure, and remain optimistic about its potential to replicate its Malaysia success in Singapore,” writes Tradeview Research analyst Tan Jia Hui in an IPO note dated April 6. She cites a stronger ringgit and gradual easing of geopolitical tensions as key drivers for outbound travel demand and margin expansion.
“Given the ongoing macro noise and elevated marketing expenses required to sustain brand awareness, however, we believe Golden Destinations is fairly valued at current levels,” Tan says. “We would adopt a wait-and-see approach until geopolitical tensions ease, which should then support a recovery in consumer spending on discretionary travel and improve earnings visibility.”
Malaca Securities is more bullish, giving Golden Destinations a fair value of 51 sen. The firm projects a three-year earnings compound annual growth rate of 6.9%, driven by demand for travel to China and Asia, the company’s strategic entry into Singapore and pent-up demand in international travel once the conflicts in the Middle East subside.
Meanwhile, TA Securities expects Golden Destinations’ earnings growth for 2026 to be flat as clients defer trips or shift towards Southeast Asian destinations, which typically carry lower average selling prices. The research house expects growth to rebound in 2027 as bookings and demand recover.
With the conflicts in the Middle East remaining a wild card, the market’s initial response has been relatively muted compared to the broader historical trends of the ACE Market.
On April 8, Golden Destinations announced that the public portion of its IPO was oversubscribed by 2.1 times. The group received 3,444 applications for 154.89 million shares, worth about RM69.7 million. Shares reserved for eligible directors and employees, as well as those set aside for private placement, were fully taken up.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.