

This article first appeared in The Edge Malaysia Weekly on April 6, 2026 - April 12, 2026
AT a time when investors are more yield-conscious amid a cautious market, CapitaLand Malaysia Trust (KL:CLMT) is leaning on its twin-engine model to sustain income and drive growth, balancing between retail malls and a rapidly expanding logistics and industrial property portfolio.
While its malls are being rejuvenated through targeted upgrades, curated tenant mixes and event-driven programming to boost footfall and spending, its logistics and industrial assets provide a stable and recurring income base.
According to CapitaLand Malaysia REIT Management Sdn Bhd CEO Yong Su-Lin, this combination allowed the trust to deliver a competitive distribution yield of 7.7% in the financial year ended Dec 31, 2025 (FY2025), compared with the 3.5% offered by 10-year Malaysian Government Securities (MGS).
She acknowledges that yield is critical for investors deciding on which Bursa Malaysia-listed real estate investment trusts (REITs) to pour their money into.
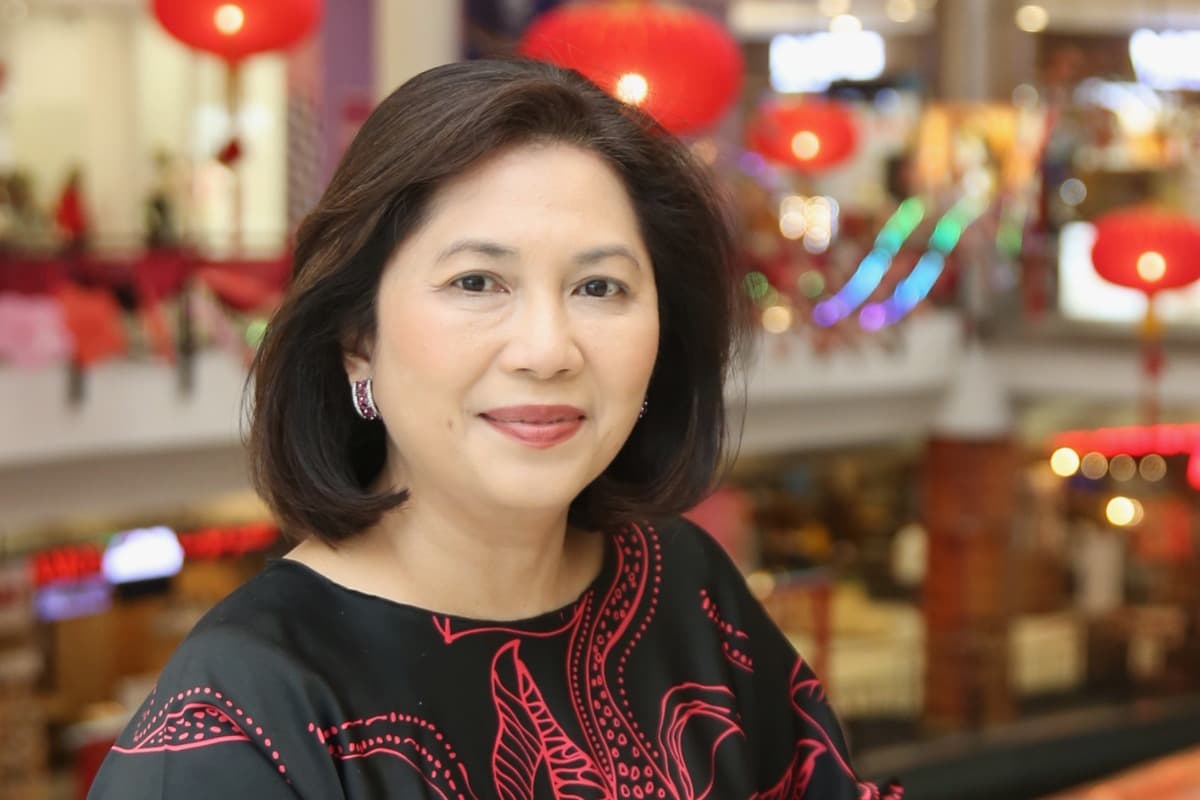
“Any [REIT] investor looks at yield first. Malaysian REITs generally performed quite well last year. Sentiment-wise, investors have turned defensive. And gold prices spiked briefly, although they’ve come down,” the 51-year-old tells The Edge in an exclusive interview at The Mines in Seri Kembangan, Selangor.
“Since CLMT’s expansion of its investment mandate, our track record over the past five years shows sustained, steady and diligent growth,” she points out.

CLMT’s distribution per unit (DPU) had grown 163% from 2021 to 2025 — an average of 33% per annum — supported by its yield-accretive acquisitions and improvement in retail performance.
Yong, who represents CapitaLand Investment Ltd (CLI) — a global real estate manager that is majority-owned by Singapore state investor Temasek Holdings — was appointed a director of CLMT in February last year. She previously had stints at Lendlease Group, Malaysian International Merchant Bankers Bhd, BDO Capital Consultants Sdn Bhd, as well as the management companies of Quill Capita Trust and Sentral REIT (KL:SENTRAL).
CLI, which controls CapitaLand Malaysia REIT Management, is a major indirect unitholder of CLMT with a 32.77% stake. The top 30 unitholders of the trust include the Employees Provident Fund (EPF), Retirement Fund Inc (KWAP), Amanah Saham Nasional Bhd’s funds and Neoh Choo Ee & Co Sdn Bhd.
CLMT’s net property income (NPI) rose 9.7% to RM289.44 million in FY2025 from RM263.93 million a year earlier, while its gross revenue grew 4.8% to RM476.76 million from RM454.76 million.
CLMT, which used to be a retail-focused REIT, last year completed the acquisition of seven logistics and industrial properties in the Klang Valley and Johor valued at RM279 million. This was its largest portfolio expansion since its investment mandate was broadened in 2021. The assets are expected to further bolster its earnings in FY2026.
Yong highlights that with the high occupancy rates across segments and proactive management of tenant performance and asset enhancements, CLMT is positioning itself to capture growth from Malaysia’s retail recovery while locking in steady income from its industrial property holdings.
“CLMT’s focus on industrial and logistics assets provides income stability while we rejuvenate our retail malls. Our leases are three years on average in retail, and turning around a mall takes time,” she says.
Yong explains that tenants that are opening outlets want sustained footfall at the mall. Once they see that, the leasing negotiations and outlet renovations follow.
“Committed occupancy on a given date doesn’t mean rental income has kicked in yet. Revenue takes time to flow in,” she adds.
CLMT, which employs 264 staff, currently operates Gurney Plaza and Queensbay Mall in Penang, East Coast Mall in Kuantan, Pahang, as well as The Mines, Sungei Wang Plaza and 3 Damansara in the Klang Valley.
Yong admits that most of CLMT’s malls are over 20 years old, but there is always room to upgrade or refresh.
“Unlike some other listed retail REITs, we are not the developer that built our malls. Although we acquired our malls from previous owners, we’re very active mall managers. We constantly look for areas to improve and spaces to reconfigure in order to optimise the tenant mix,” she says.
For instance, CLMT has introduced the concept of Penang as a food haven at its malls, she points out. “At Gurney Plaza, the fourth floor used to house furniture shops, which were passive spaces. We conducted an asset enhancement initiative (AEI) to reconfigure the space into an upscale contemporary food hall that features local heritage street food and international delights — something that Penang is known for. Now, these areas are vibrant, and it shows how targeted improvements can drive traffic,” she elaborates.
For its Klang Valley malls, CLMT adopts different approaches to bring in footfall. Some of its latest offerings include event-focused operators, says Yong.
“We rent space to these event organisers who bring in mini-concerts, live shows and stand-up comedy. These activities drive footfall and longer dwell times, and in turn leads to increased spending at retail and F&B (food and beverage) outlets,” she adds.
“There’s a real spillover effect. When we bring people in for one event, they shop, dine and experience the mall more fully. Our malls also work with tourism boards, especially in Penang, a medical tourism hotspot. Events like Visit Malaysia 2026 will add further momentum.”
Yong notes that local tourists, foreign visitors and event programming all play a role.
“Even with strong malls, there’s always room to activate dormant areas. Retail requires agility. That’s why we focus on marketing events, tenant mix and the customer experience,” she says.
At 3 Damansara, CLMT introduced new brands across its F&B outlets such as Brew House, Zai San Bei (Chinese-Japanese Izakaya fusion), Ah Yip Herbal Soup and HWC coffee. Meanwhile, the REIT manager brought in Cold Storage and Thai Odyssey to Sungei Wang Plaza to improve its offerings of daily essentials and services.
As for The Mines, a new active lifestyle concept was brought in, featuring its anchor lifestyle tenant Game On Theme Park, which is one of the largest indoor theme parks in Selangor with more than 30 attractions offering an interactive mix of sports, games and adventure activities.
Yong says CLMT’s three malls in the Klang Valley are well located and have strong residential catchment. Notably, the introduction of indoor entertainment and event venues such as Mega Star Arena at Sungei Wang Plaza and Idea Live Arena at 3 Damansara play an important role in its asset management strategy.
“These venues draw consistent crowds for concerts, fan meetings and events. Since the opening of Idea Live Arena in April 2025, traffic at 3 Damansara has seen month-on-month growth. For the full year 2025, traffic at 3 Damansara was up 17.6%,” she reveals.
Meanwhile, CLMT will see full-year contributions in FY2026 from the industrial and logistics assets that were acquired last year, says Yong.
“We’ve had proposals for office and healthcare assets, but the yields aren’t attractive compared to those of industrial assets. Our focus in the short to medium term will be on industrial and logistics assets, unless we come across a specific proposal that offers compelling returns. Many proposals have come through, but we remain disciplined in our strategy,” she adds.
CLMT’s logistics and industrial property portfolio consists of Valdor Logistics Hub in Penang and Glenmarie Distribution Centre in Shah Alam; the newly acquired Senai Airport City Facilities and Iskandar Puteri Facilities in Johor; and Synergy Logistics Hub, an automated logistics property in Elmina Business Park.
CLMT’s total portfolio had risen 7% year on year to RM5.5 billion as at Dec 31, 2025. This was largely attributable to the acquisitions of the three industrial and logistics assets, namely Senai Airport City Facilities, Iskandar Puteri Facilities and Synergy Logistics Hub.
Moreover, CLMT has announced the forward purchase acquisition of five industrial properties in the Johor-Singapore Special Economic Zone (JS-SEZ). “Looking ahead, we will continue to explore yield-accretive acquisitions in our target markets such as Penang, Johor and the Klang Valley to build meaningful scale,” says Yong.
She believes that the outlook for the industrial property sector remains robust, bolstered by enhanced government incentives aimed at accelerating investments in high-growth industries.
Upon completion of the five industrial facilities, the industrial and logistics share of CLMT’s assets under management (AUM) is expected to rise to 11.5% from 2.4% in 2024. “We are making progress and on track to meet our 2028 target of 20% AUM composition for the industrial and logistics portfolio,” says Yong.
Withholding tax issue
Over the past month, the unit price of Main Market-listed CLMT had declined by 5.5 sen or 8.3% to close at 60.5 sen last Wednesday, giving the trust a market capitalisation of slightly more than RM2 billion.
The REIT sector has been largely dragged down by the announcement in mid-March that the government had removed the preferential withholding tax rate of 10% on dividends from REITs or property trust funds. The concessionary rate of 10% for most non-corporate investors ceased to apply effective from year of assessment 2026, according to the Inland Revenue Board’s notice.
For perspective, Malaysians will now be taxed based on prevailing individual rates with no withholding tax deduction. In other words, resident individuals will now be taxed based on progressive income tax rates of between 0% and 30%.
Foreign individuals and institutional investors will be taxed at 30% of chargeable income, while non-resident corporations will pay a final withholding tax rate of 24%.
When asked about the potential impact of the withholding tax issue, CLMT says it will “refrain from making comments at this point in time as we need time to assess”.
Following the announcement, Maybank Investment Bank Research insisted that the REIT sector’s underlying yield profile remains relatively resilient. In a report last month, the research house estimated that “net yields could still average at 4.7% to 6.0%, and remain attractive relative to most sectors”, even after factoring in the new tax regime.
Its top REIT picks are CLMT, Paradigm Real Estate Investment Trust (KL:PARADIGM) and Al-Salam REIT (KL:ALSREIT).
AskEdge shows that CLMT is currently trading at a historical price-earnings ratio (PER) of 13.4 times, which is lower than most of its peers. In comparison, IGB REIT (KL:IGBREIT) is trading at a PER of 25.4 times, Pavilion REIT (KL:PAVREIT) at 18 times and Sunway REIT (KL:SUNREIT) at 16.5 times.
Yong says the competition among retail REITs and shopping mall operators is unavoidable. “It’s about adapting and planning, not necessarily beating rivals. We position ourselves carefully and work closely with tenants.
“During renewals, we work with our tenants to refresh their outlets. Simple things like upgrading signage or minor refurbishments do make a difference in creating appealing environments.”
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.