

This article first appeared in The Edge Malaysia Weekly on March 30, 2026 - April 5, 2026
TAKING the market by storm, Sunway Healthcare Holdings Bhd (KL:SUNMED) stands out as the only big-cap stock on Bursa Malaysia whose price-earnings ratio (PER) has soared above 100 times. This is despite the broadly cautious sentiment triggered by the Iran war that erupted in late February.
Since its listing on March 18, the hospital operator has added almost RM10.6 billion to its market capitalisation, which stood at RM27.26 billion based on its closing price of RM2.37 last Friday, up 63.45% against its listing price of RM1.45 or RM16.7 billion in market value.
The PER of more than 100 times is based on Sunway Healthcare’s net profit of RM252.21 million for the financial year ended Dec 31, 2025, which means investors are paying over RM100 for every RM1 of profit the company makes.
Interestingly, in a press conference last week, Sunway Bhd (KL:SUNWAY) founder and chairman Tan Sri Jeffrey Cheah assured that the healthcare group will continue to deliver on its targets, despite the stock trading at above 100 times PER. The growth will be supported by its “build-from-scratch” organic expansion model, he added.
He attributed the premium valuation to the group’s unique internal capabilities and execution strategy. “The big difference is that we build every hospital ourselves, right from the start. We do everything ourselves,” he said.

The mega listing led to Sunway Healthcare being included as an FBM KLCI component stock last Wednesday, replacing QL Resources Bhd (KL:QL). Around the same time, the Employees Provident Fund (EPF) also emerged as its substantial shareholder, holding a 5.13% stake.
Shares in Sunway — which has a 69.5% stake in Sunway Healthcare — had gained 4.6% during the same period, closing at RM5.47 last Friday for a market value of RM36.98 billion.
What’s noteworthy is that at its peak, the PER of 99 Speed Mart Retail Holdings Bhd (KL:99SMART) — another prominent listing in recent years — only came in below 60 times.
FOMO effect
Many are wondering if Sunway Healthcare’s strong share price rally has been primarily fuelled by strong expectations for its growth prospects.
Besides the institutional support with accumulation by the current cornerstone investors and funds, Malacca Securities head of research Loui Low tells The Edge that this dynamic could have been further amplified by a degree of FOMO (fear of missing out) among fund managers seeking to justify relative performance of their funds against the EPF.
In addition, he points out that the issuance of call warrants may have provided technical support to the stock, as banks and brokerage houses accumulate shares in the underlying stock to hedge their exposure.
Having said that, at current levels, Low reckons that the upside for Sunway Healthcare appears limited, with valuations suggesting that much of its long-term growth is already priced in.
“As early as its listing day, the market seemed to already be pricing in earnings well into 2032,” he says.
Prior to its listing less than two weeks ago, Sunway Healthcare’s initial public offering (IPO) — which garnered 20 cornerstone investors that subscribed for 52.6% of the institutional offering — was already labelled as “overvalued” or “expensive”, as its price was pegged at a PER of 64.8 times based on the company’s FY2024 net profit, significantly higher than its larger peers such as IHH Healthcare Bhd (KL:IHH) and KPJ Healthcare Bhd (KL:KPJ).
At the time Sunway Healthcare was undertaking its book-building exercise, IHH and KPJ were trading at a PER of 38.03 times and 37.87 times respectively.
In FY2024 and FY2025, Sunway Healthcare recorded a net profit of RM257.5 million and RM252.21 million respectively.
In terms of EV/Ebitda (enterprise value to earnings before interest, taxes, depreciation and amortisation) — the preferred method used by bankers to value companies with substantial assets — Sunway Healthcare was listed at 36.1 times based on RM469.7 million Ebitda in FY2024. This was double that of IHH’s 17.7 times and KPJ’s 15.4 times.
Following the share price surge, Sunway Healthcare’s forward PE multiple has expanded to 91.15 times, with EV/Ebitda rising to 56.32 times.
This is in stark contrast to IHH and KPJ. Even though shares in the two hospital operators have rallied since last year, they are trading at much lower forward PE multiples of 38.03 times and 41.46 times respectively.
At its latest market cap of RM79.96 billion, IHH’s EV/Ebitda is valued at 16.51 times while KPJ’s EV/Ebitda stands at 15.4 times based on its latest market value of RM15.36 billion.
Earnings visibility for next three years priced in
While BIMB Securities director of research Mohd Redza Abdul Rahman says Sunway Healthcare’s premium valuations relative to its peers are justified — given its stronger and more compelling value proposition as well as the absence of the forex exposure, such as those seen in IHH — he cautions that earnings visibility for FY2027 to FY2028 has already been priced in.
He adds that Sunway Healthcare’s long-term growth will be supported by its diverse offerings — from maternity care to retirement homes.
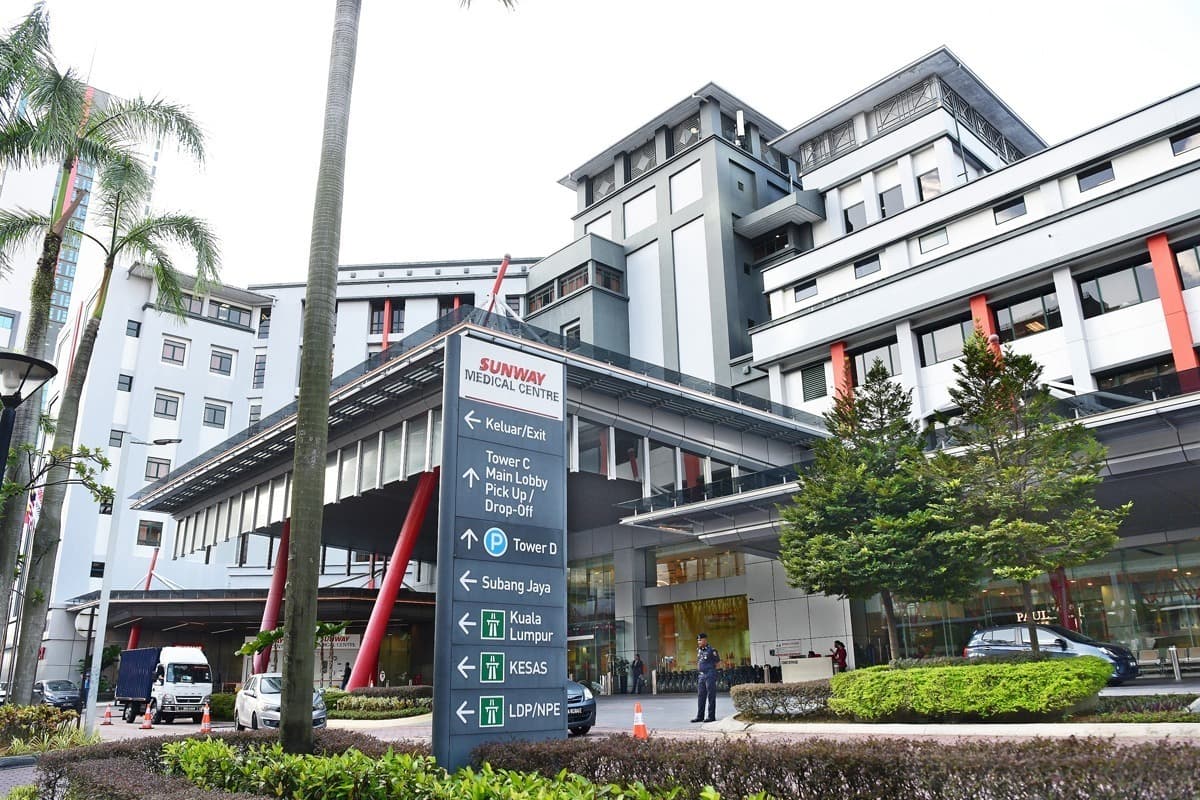
As Malaysia’s top private healthcare provider, Sunway Healthcare was operating 1,805 licensed beds as at January 2026, led by its flagship Sunway Medical Centre in Subang Jaya, which is said to be the country’s largest private hospital.
This would translate into a market cap per bed of about RM15.1 million. The group plans to expand its operations to 3,400 licensed beds by 2031, which will bring its market cap per bed to about RM8.02 million based on the current market cap.
Currently, Sunway Healthcare operates five hospitals in the country, with plans to open new hospitals in Seremban (Negeri Sembilan), Iskandar Puteri (Johor) and Putrajaya, as well as a fertility centre in Kota Bharu, Kelantan.
In comparison, IHH has a presence across 10 countries and manages about 15,640 licensed beds, translating into a lower market cap per bed of about RM5.11 million. Meanwhile, KPJ, which has about 4,100 licensed beds, generates about RM3.76 million in market cap per bed.
KPJ made a record net profit of RM365.93 million in FY2025 on revenue of RM4.26 billion, against RM353.82 million in net profit on revenue of RM3.9 billion in FY2024.
Over the past year, shares in IHH and KPJ have risen 32.7% and 31% respectively.
Will hospital operator stocks be able to maintain their momentum? After all, investor tolerance for sustained high valuations — particularly in Sunway Healthcare — will be put to the test.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.