

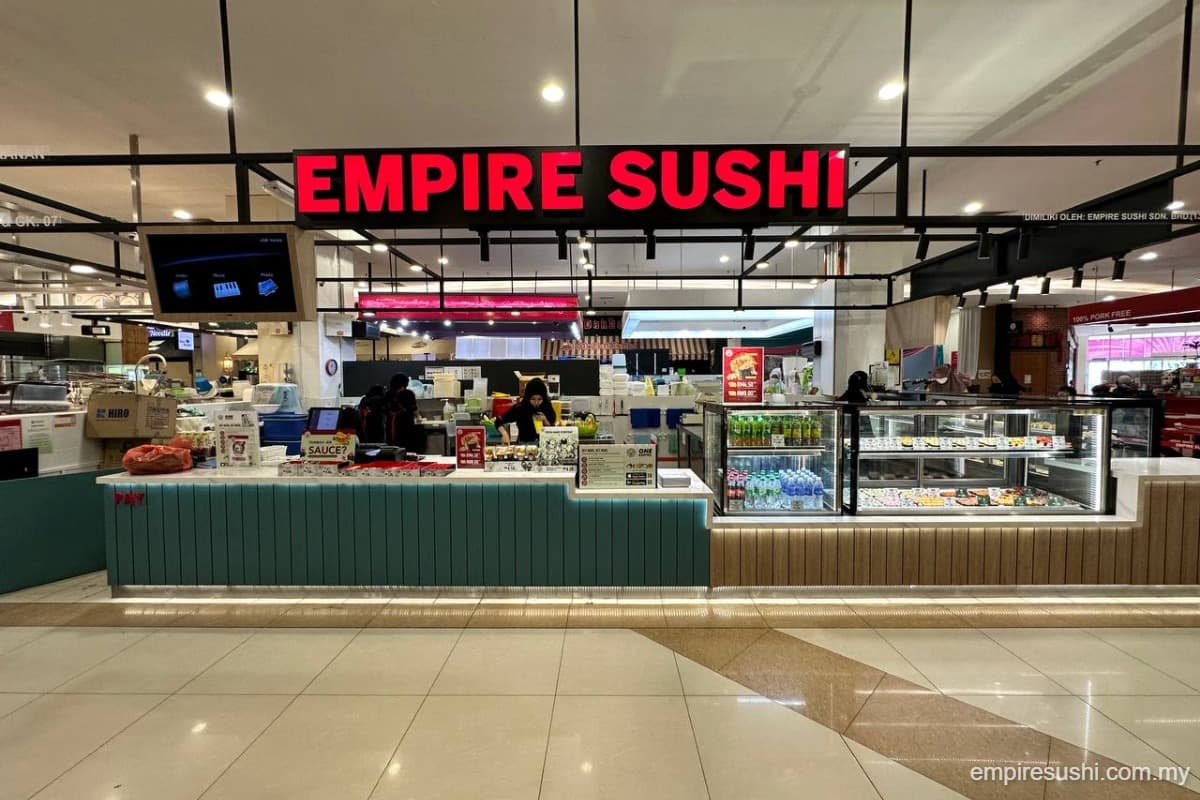
KUALA LUMPUR (March 30): Empire Premium Food Bhd, the operator of Empire Sushi takeaway chain, is now reliant on store count for revenue growth as same-store sales declined, analysts said.
New outlets opening within the same regions have been absorbing a portion of sales that would otherwise accrue to existing stores, Public Investment Bank said in a pre-listing note, noting that the dynamic is most pronounced in the central region even as revenue continued to grow.
“The top-line growth story is increasingly dependent on store count rather than same-store productivity,” the research house flagged.
Same-store sales growth — a common retail industry metric that measures performance of outlets that have been open for at least one year — has fallen for three straight financial years at Empire Premium from 12.2% to just 1.6% for the latest six-month period.
Empire Premium currently owns 143 outlets, out of which 127 are takeaway stores and 16 quick dine-in eateries. Over the next three years, the company is targeting the opening of 56 new outlets with funds raised from its listing on the Main Market.
The initial public offering, indicatively priced at 70 sen a piece, will raise RM152.6 million for the company and another RM101.5 million for Jordan Tan and Nicole Lim, the husband-and-wife co-founders of Empire Premium, according to its official prospectus.
Still, Public Investment and other analysts are projecting upsides to the listing from further earnings growth from its aggressive outlets expansion.
Malacca Securities also highlighted the falling same-store sales growth as a weakness while Empire Premium’s “easy to scale” business model and stores in high-traffic areas like shopping centres, hypermarkets, airport and transit hubs nationwide would be its strengths.
The research house is forecasting an average annual earnings growth of about 14% over the next three years, mainly supported by the expansion of both new grab-and-go and quick dine-in outlets nationwide.
At the IPO price of 70 sen, Empire would be valued at about 20 times the trailing earnings, while three analysts’ fair values are based on forward multiples of 16-to-21 times.
Public Investment values Empire Premium at 98 sen, while Malacca Securities has the company at 93 sen. An earlier unrated note by TA Securities pegs the company’s fair value at 83 sen.
The dividend yields would come in around 2% for the next two years based on the target prices of the three research houses. Empire, which will remain in net cash position post-IPO, intends to pay at least 30% of annual profit-after-tax as dividends.