

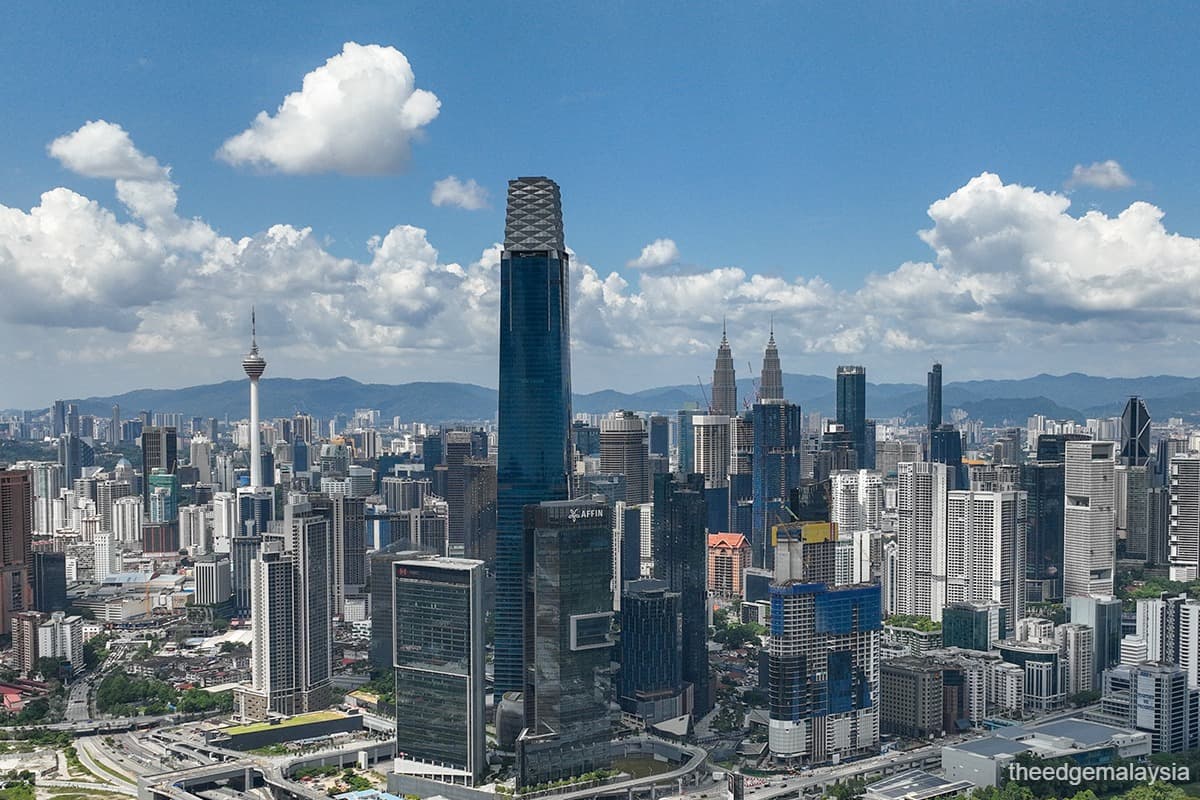
This article first appeared in City & Country, The Edge Malaysia Weekly on March 23, 2026 - March 29, 2026
The Klang Valley office sector saw moderate growth in 4Q2025, with occupancy levels and rental rates experiencing a slight improvement, according to Knight Frank Malaysia senior executive director of office strategy and solutions Teh Young Khean when presenting The Edge Malaysia | Knight Frank Kuala Lumpur and Selangor Office Monitor 4Q2025.
“Leasing momentum softened towards the year end with overall market performance moderating in 4Q2025. Net absorption slowed during the quarter, recording fewer large-scale relocations or expansion activities, particularly into newer office buildings that had recorded stronger take-up earlier in the year. In the absence of new completions, both occupancy levels and rental growth continued to edge up, indicating the resilience of the market,” says Teh.
Average office occupancy in Kuala Lumpur showed mixed results in 4Q2025. The new central business district (CBD) recorded an average occupancy of 77.4%, an increase from 76.8% in 3Q2025. The old CBD registered an average occupancy of 54.1% in 4Q2025 — a slight decline from 54.4% in 3Q2025.

The KL city centre peripheral area posted an average occupancy of 51.6% in 4Q2025, an increase from 51.3% in the previous quarter. Overall, average occupancy in the market rose slightly to 70.6% in 4Q2025 from 70.1% in 3Q2025.
Meanwhile, the KL Fringe market recorded an average occupancy of 88.2% in 4Q2025, slightly lower than 88.3% in 3Q2025.
In 4Q2025, Damansara Heights recorded an average occupancy of 84.4%, from 83.0% in 3Q2025. KL Sentral registered an average occupancy of 95.5%, a decline from 96.0% in 3Q2025.
The Taman Tun Dr Ismail/Mont’Kiara/Dutamas locality posted an average occupancy of 80.2%, an increase from 78.2% in the previous quarter. Mid Valley City/KL Eco City maintained a stable performance with an average occupancy of 88.0% — the same as in 3Q2025.

Bangsar South/Kerinchi recorded an average occupancy of 96.8% in 4Q2025, which is a decrease from 98.1% in 3Q2025. In Pantai/Bangsar, average occupancy stood at 71.8%, marking a decrease from 72.5% in the previous quarter.
As for Selangor, it achieved an average occupancy of 73% in 4Q2025, up from 72.5% in 3Q2025.
Petaling Jaya recorded an average occupancy of 76.2% in 4Q2025, representing an increase from 75.9% in 3Q2025. Subang Jaya posted an average occupancy of 62.6%, reflecting an increase from 61.2% in 3Q2025.
Meanwhile, Shah Alam registered an average occupancy of 87.4%, marking an increase from 86.9% in 3Q2025. Cyberjaya recorded an average occupancy of 69.9% in 4Q2025, showing an increase from 69.5% in the previous quarter.


Knight Frank Malaysia executive director of research and consultancy Amy Wong says growth in the Klang Valley’s office market was mainly driven by newer office buildings with higher specifications, as flight-to-quality trends continued to influence occupier preferences, with tenants favouring well-located, flexible and efficiently designed offices.
Concurring with Wong, Teh says occupier demand continues to be shaped by Malaysia’s gradual shift towards higher-value and technology-enabled activities, with multinational firms selectively expanding their regional headquarters and support functions.
He adds, “Policy measures announced under Budget 2026 are expected to lend incremental support to demand for higher-specification office space.”
Concurrently, the recent reduction of the sales and service tax (SST) to 6% from 2026 onwards may provide modest cost relief to occupiers, although its impact on leasing activity is expected to remain limited in the near term, says Teh.

The Klang Valley market recorded several tenant movements across KL City, KL Fringe and Selangor in 4Q2025. Recent notable tenant movements in Kuala Lumpur and Selangor comprise a mix of relocations, expansions, downsizing and new setups from various sectors.
In KL City, a tenant from the professional and business services sector relocated to CIMB Hub, occupying about 31,000 sq ft, while another from the property and construction sector relocated to Ilham Tower, taking up 7,000 sq ft. Plaza Conlay saw a new tenant from the industrial and automotive sector move in, occupying around 11,000 sq ft.
In the KL Fringe area, The Gardens South Tower welcomed a tenant from the fast-moving consumer goods (FMCG) sector that now occupies about 16,000 sq ft. A construction sector tenant moved into The MET Corporate Towers, taking up roughly 13,000 sq ft.


Menara BT (Tower 3, Avenue 7) experienced both expansion and downsizing activities during the quarter under review, with an 8,000-sq-ft move-in of a pharmaceutical and life sciences company, alongside a 10,000-sq-ft move-out by a tech/IT tenant.
Meanwhile, an FMCG tenant in Vertical Corporate Tower B in Bangsar South downsized its operations by 18,000 sq ft.
In Selangor, Sunway Square Corporate Tower 2 provided a 38,000-sq-ft space for a co-working and flexi-space provider as well as an industrial/chemical sector tenant, both relocating or setting up anew. Wisma LYL recorded a 31,000-sq-ft move-in of an IT sector company and Wisma AmFirst welcomed an industrial and automotive tenant that has taken up 24,000 sq ft of space.


Limited supply and net absorption
The Klang Valley office market recorded no new completions in 4Q2025. For the full year of 2025, total new office supply amounted to 2.4 million sq ft. The current estimated office supply across the Klang Valley totals 120.62 million sq ft. Of this, KL City accounts for the largest share with 60.63 million sq ft, followed by the KL Fringe with 32.18 million sq ft, while Selangor contributes 27.81 million sq ft to the existing office stock.
In terms of future supply, about 4.13 million sq ft of office space is currently under construction across the region, with an expected completion timeline of between 2026 and 2027. The KL Fringe has the largest portion of upcoming supply with 2.54 million sq ft, followed by Selangor with 1.20 million sq ft, while KL City has a smaller pipeline of 0.39 million sq ft.
KL City is projected to add 0.12 million sq ft in 2026 and 0.27 million sq ft in 2027. In the KL Fringe, about 1.53 million sq ft is expected to be completed in 2026, followed by 1.01 million sq ft in 2027. Meanwhile, Selangor is expected to deliver 1.20 million sq ft of new office space in 2026, with no additional completions currently scheduled for 2027.
In terms of net absorption, the monitor shows that Kuala Lumpur witnessed a modest growth during the review period at about 153,000 sq ft. However, full-year absorption rose by 11.5% year on year (y-o-y) to about 1.9 million sq ft, which the monitor explains reflects a gradual improvement in occupier activity over the course of the year.
In Selangor, the monitor indicates that quarterly net absorption improved to around 101,000 sq ft, partly supported by the take-up of space at the newly completed Sunway Square Corporate Towers. On a full-year basis, net absorption in 2025 totalled about 413,000 sq ft, rising 48.6% y-o-y.
Rental remains steady
Rental rates in Kuala Lumpur showed a modest growth in 4Q2025. Kuala Lumpur City recorded marginal movements in 4Q2025. In the new CBD, average rents rose slightly to RM7.37 psf per month, reflecting a 0.3% increase from the previous quarter’s RM7.35 psf. Meanwhile, rental rates in the old CBD remained unchanged at RM4.45 psf per month.
Similarly, rents in the KL City Centre peripheral area held steady at RM5.70 psf per month, unchanged from the previous quarter. Overall, the average rental rate for KL City edged up slightly to RM6.74 psf per month, representing a 0.3% increase from RM6.72 in 3Q2025.
Across the KL Fringe, rental performance was largely stable in 4Q2025. Damansara Heights recorded a slight increase to RM4.63 psf per month, up 0.2% from RM4.62 psf per month in the previous quarter. In contrast, rental rates in KL Sentral remained unchanged at RM6.41 psf per month, while Taman Tun Dr Ismail, Mont’Kiara and Dutamas continued to record average rents of RM5.28 psf per month.
Meanwhile, Mid Valley City and KL Eco City saw a marginal increase to RM6.49 psf per month, reflecting a 0.3% q-o-q rise. Rental rates in Bangsar South/Kerinchi and Pantai/Bangsar were unchanged at RM5.70 psf per month and RM5.33 psf per month respectively. The overall KL Fringe market remained stable, with the average rental rate holding steady at RM5.83 psf per month.
Office rental rates across Selangor were stable in 4Q2025, with only marginal changes recorded in certain locations.
In Petaling Jaya, average rental rates were maintained at RM4.57 psf per month, unchanged from the previous quarter. Meanwhile, Subang Jaya recorded a marginal increase to RM4.63 psf per month, reflecting a 0.2% rise from RM4.62 psf per month in 3Q2025.
Rental rates in Shah Alam and Cyberjaya remained the same during the quarter, standing at RM3.46 psf per month and RM3.72 psf per month respectively. The overall Selangor office market remained stable, with the average rental rate holding at RM4.29 psf per month.
Wong says, “Following 2.4 million sq ft of completions in 2025 and a further 2.85 million sq ft expected in the coming year, rental growth is expected to remain selective, favouring prime, well-specified offices, as older or less well-located assets face continued pressure.”
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.