

This article first appeared in Capital, The Edge Malaysia Weekly on March 16, 2026 - March 22, 2026
THE listing of Sunway Healthcare Holdings Bhd (KL:SUNMED), scheduled for this Wednesday, March 18, will be a litmus test of the strength of the local stock market amid uncertainties arising from joint US-Israeli strikes on Iran that triggered volatility in commodity prices, especially oil and gold.
The initial public offering (IPO) is set to be Malaysia’s largest in nine years, raising up to RM2.86 billion and valuing the hospital operator at around RM16.68 billion, beating 99 Speed Mart Retail Holdings Bhd’s (KL:99SMART) and Khazanah Nasional-backed Farm Fresh Bhd’s (KL:FFB) valuation of RM11.2 billion and RM2 billion when they were listed in 2024 and 2022 respectively.
Of the RM2.86 billion raised, RM833.76 million from the issuance of new shares will go to Sunway Healthcare while the remaining RM2.02 billion from the sale of existing shares will go to its selling shareholders Sunway Bhd (KL:SUNWAY) via subsidiary Sunway City Sdn Bhd (SunCity), and Singapore’s sovereign wealth fund GIC via subsidiary Greenwood Capital Pte Ltd.
SunCity will remain the controlling shareholder post-listing with a 69.5% stake — falling from 84% — while GIC will pare down its shareholding to 7.5% from 16%.
The IPO price was set at RM1.45 per share, representing a price-earnings ratio (PER) of 64.8 times based on its net profit for the financial year ended Dec 31, 2024 (FY2024).

A number of market observers deem Sunway Healthcare’s valuations to be lofty, especially as other Bursa Malaysia-listed major healthcare providers are trading at far lower valuations. IHH Healthcare Bhd (KL:IHH), for instance, was trading at 30 times FY2024 PER, and KPJ Healthcare Bhd (KL:KPJ) at 37.4 times.
Be that as it may, Sunway Healthcare’s IPO garnered 20 cornerstone investors that subscribed for 52.6% of the institutional offering. The cornerstone investors include the Employees Provident Fund (EPF), Lembaga Tabung Haji, JPMorgan Asset Management (Singapore) Ltd and Urusharta Jamaah Sdn Bhd. Cornerstone investors typically agree to buy a chunk of the IPO shares ahead of the listing to help boost the company’s appeal to other potential investors.
Sunway Healthcare’s IPO comprises an offer for sale of up to 1.39 billion existing shares and a public issue of 575 million new shares.
Of the total shares offered, about 1.62 billion are allocated to institutional investors, while 345 million shares are reserved for retail investors.
Its public issue of new shares received applications for 1.51 billion shares worth RM8.42 billion and was oversubscribed by 5.57 times. The bumiputera public tranche was oversubscribed by 0.76 times, while the non-bumiputera portion saw an oversubscription rate of 10.37 times.
Of the RM833.67 million raised from the sale of new shares, the bulk — RM554.1 million — will be used for the expansion of Sunway Healthcare’s existing hospitals. About RM250 million of the IPO proceeds have been earmarked for the early settlement of its Islamic medium-term notes under a RM5 billion sukuk wakalah issued in several tranches and series. To date, it has sold RM1.3 billion worth of Islamic bonds under the programme.

The balance of RM30 million of the proceeds will be used for defraying listing expenses. For the IPO, Maybank Investment Bank and AmInvestment Bank are acting as joint principal advisers, joint global coordinators, joint bookrunners and joint underwriters.
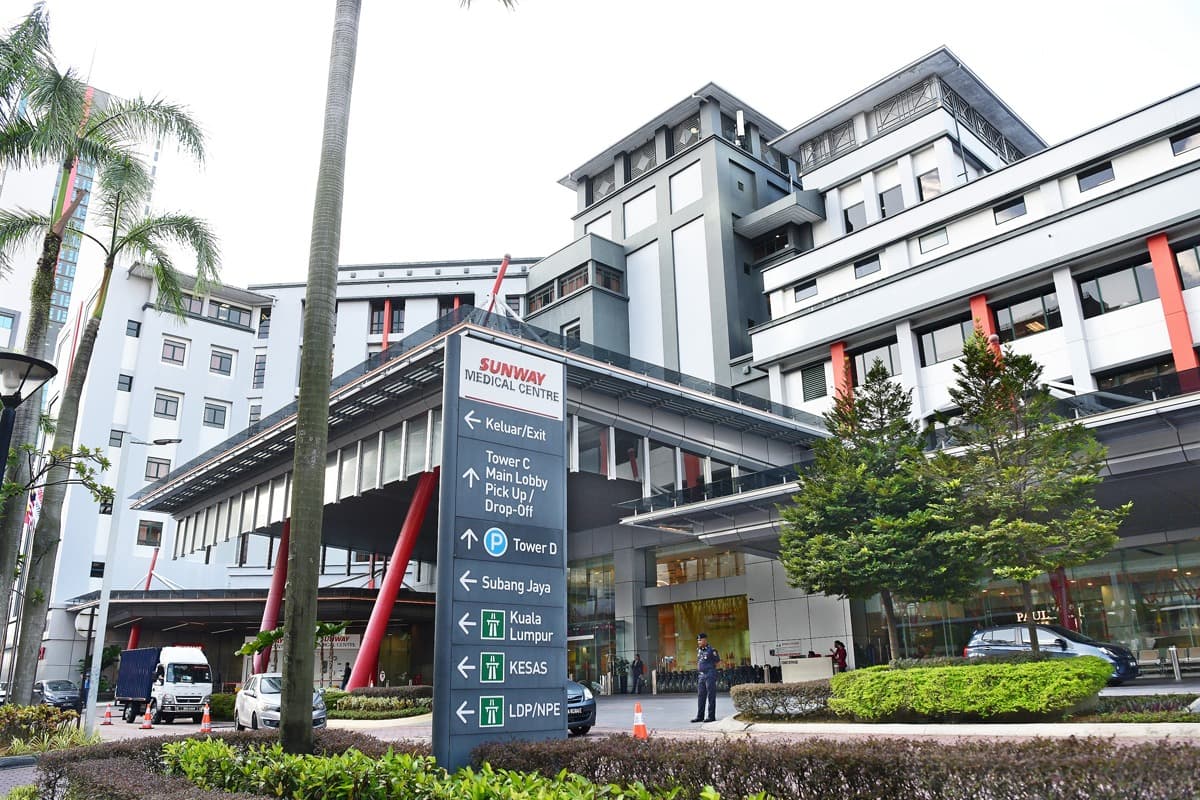
Sunway Healthcare is among the country’s top private healthcare providers, with 1,805 licensed beds as at January 2026, led by its flagship Sunway Medical Centre in Subang Jaya, Selangor, which the group says is the country’s largest hospital.
Its network also includes facilities in Cheras, Penang, Damansara and Ipoh, alongside ancillary businesses such as ambulatory care centres, fertility services, traditional and complementary medicine, home care and senior living.
Sunway Healthcare has plans for new hospitals in Seremban, Negeri Sembilan, Iskandar Puteri, Johor, and Putrajaya, as well as a fertility centre in Kota Bharu, Kelantan, which will raise its total bed capacity to more than 3,444 or 74% by 2032, carried by brownfield expansions and greenfield projects in Seremban, Iskandar Puteri and Putrajaya.
The group targets a dividend payout ratio of up to 30% of its net profit annually, taking into account its working capital, maintenance capital and committed capital requirements.
It should be noted that Sunway Healthcare dished out a pre-IPO dividend to its shareholders amounting to RM622.6 million to SunCity and Greenwood Capital in FY2025, as well as another RM100 million in February 2026. In addition, the group will dish out its final dividend to Greenwood Capital of RM5.2 million, which is required to be paid no later than seven days from the date of its listing.
Public Invest Research ascribed a fair value of between RM1.35 and RM1.55 on Sunway Healthcare shares based on the enterprise value to earnings before interest, taxes, depreciation and amortisation (EV/Ebitda) methodology, applying multiples of 20 times to 23 times to its FY2027 estimates.
“This is at a premium to Malaysia’s peer valuation of 14 to 19 times EV/Ebitda, but we believe this is justifiable given its market leadership with a solid expansion plan, extensive healthcare service offerings as well as being one of the fastest-growing private hospital groups in Southeast Asia,” it says in the March 4 report.
The research house points out that Sunway Healthcare is poised to leverage the international medical tourism market.
“The proximity to Sunway’s hospitality assets and transport connectivity is expected to support medical tourist inflows, contributing to patient mix diversification and incremental revenue growth.”
The downside risks highlighted by the research house include competition, shortage of doctors and nurses, and the implementation of a diagnosis-related group (DRG) payment system that may lead to price predictability and limitation to hospital bill size, though this has been delayed to 2027.
Meanwhile, TA Securities Research ascribes a higher fair value on Sunway Healthcare at RM1.62 per share, based on an EV/Ebitda (FY2027 forecast) multiple of 21 times and a 5% environmental, social and governance premium.
“Our assigned EV/Ebitda multiple represents a 24% premium to peers within the private healthcare services space. This premium reflects Sunway’s strong brand reputation, robust growth prospects and its proven track record of rapid ramp-up periods for new hospitals,” it says.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.