

This article first appeared in The Edge Malaysia Weekly on March 16, 2026 - March 22, 2026
UBB Amanah Bhd insists that all trust income and maturity proceeds have been disbursed to its clients without delay, pushing back against questions surrounding its cash trust schemes that are said to be operating in a grey area of Malaysia’s financial system.
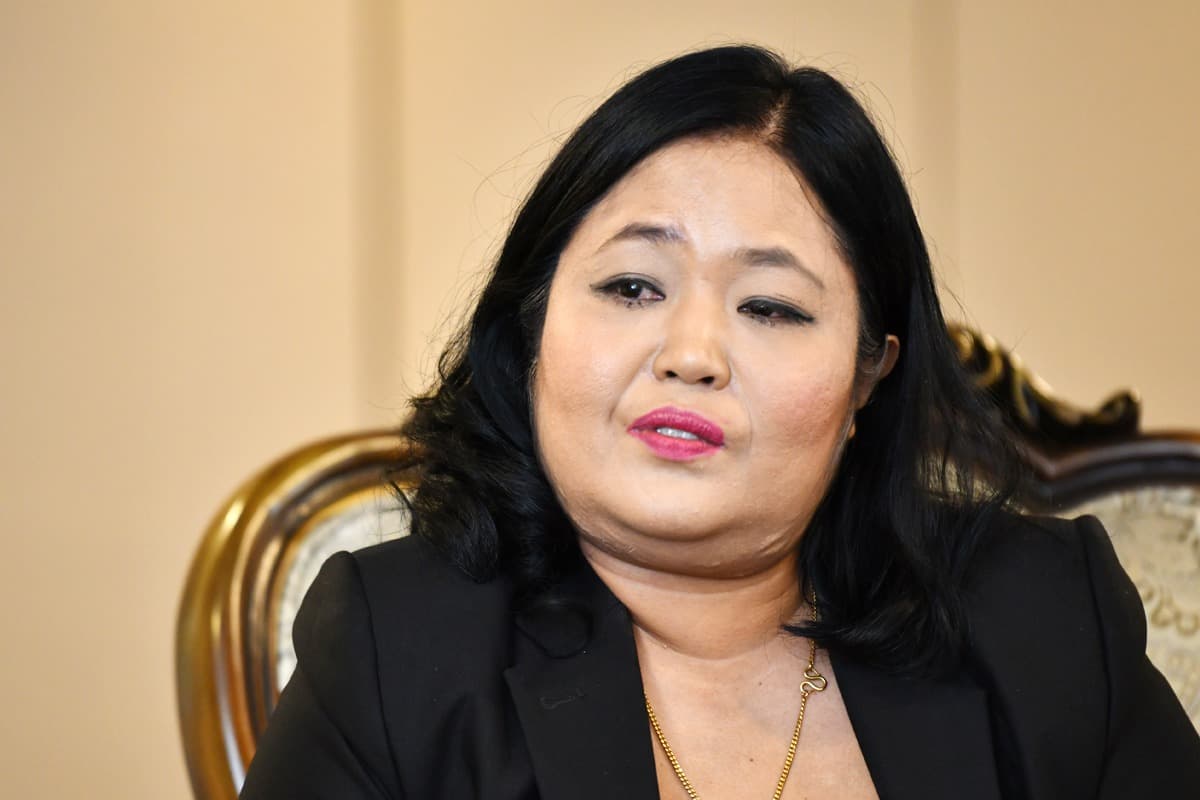
Managing director Aida Othman says all obligations to clients have been met as scheduled, maintaining that the memoranda sighted by The Edge were “routine internal administrative notices” rather than evidence of financial strain.
“There has been no issue or irregularity regarding the payment of trust income or maturity proceeds to our clients. All obligations to clients have been met in full and on time,” she says in a written reply to queries from The Edge, stressing that there are no “outstanding” or “due” amounts owed to UBB Amanah’s clients.
Her response follows a series of internal memoranda circulated to the company’s agents earlier this year that could raise concerns about payment delays and liquidity management within UBB Amanah’s cash trust products.
One memorandum informs agents that a technical glitch in the banking system could delay the disbursement of trust income from Feb 28 to March 2. Another memorandum outlines a “special transfer arrangement” for clients whose trusts are approaching maturity, with agents advised to proactively inform eligible clients of the option to transfer their funds into other trust products offered by the company.
Separately, an earlier memorandum issued in January states that projected trust income rates for new trusts will be revised downwards after April 15, although existing trusts and those established before that date will continue to receive the prevailing rates. No specific rates were mentioned.
Taken together, such communications may raise questions among investors about the financial dynamics behind cash trust schemes that promise steady and relatively high returns, particularly whether operators have sufficient liquidity to meet scheduled payouts.
Aida says, however, that this interpretation is misplaced, insisting that the circulars are routine communications intended for agents managing client relationships.
“The ‘special transfer arrangement’ mentioned is a standard business practice. It is simply an administrative facility to allow satisfied clients to seamlessly transition their mature instruments into other selected services offered by the company,” she says, acknowledging the authenticity of the memoranda.
“It is an optional rollover for client convenience, not a measure driven by any liquidity concern. It is normal for trust companies to offer continued services to their clients.”
Aida adds that details relating to individual trust structures and client payments cannot be disclosed publicly, citing statutory confidentiality obligations.
“As a trust entity operating under the purview of the Trust Companies Act 1949, we are bound by strict duties of confidentiality regarding our communications with settlors, donors and beneficiaries. We take this statutory obligation seriously,” she says.
Operating in a regulatory grey zone
Cash trust products operate largely outside the traditional regulatory perimeter of Malaysia’s financial investment system.
Trust companies are typically registered with the Companies Commission of Malaysia (SSM) under the Trust Companies Act 1949 and the Trustee Act 1949. Their services often include estate planning instruments such as wills, insurance trusts, education trusts and corporate trust structures.
Thus, UBB Amanah says, its operations are also governed by legislation including the Companies Act 2016, Wills Act 1959, Probate and Administration Act 1959, Personal Data Protection Act 2010 and the Anti-Money Laundering, Anti-Terrorism Financing and Proceeds of Unlawful Activities Act 2001.
Yet, cash trust products, where clients place funds with a trustee that manages the money on behalf of beneficiaries, occupy an unusual position in the financial ecosystem.
Unlike bank deposits, they are not covered by deposit insurance protection. At the same time, they fall outside the regulatory purview of Bank Negara Malaysia and the Securities Commission Malaysia (SC), effectively leaving the sector operating in a regulatory “no man’s land”.
In many cases, cash trust schemes are marketed as relatively low-risk instruments capable of generating consistent returns — sometimes exceeding 10% annually — through investment activities or money-lending arrangements.
The structure can resemble deposit-taking or pooled investment schemes, albeit without the licensing requirements imposed on banks, fund managers or unit trust operators.
And unlike traditional trusts that typically hold assets such as property or shares, some cash trust schemes also come with lock-in periods of three to five years, depending on the terms and conditions, with steep penalties imposed for early withdrawal.
Regulators move to close the gaps
Earlier in February, the Ministry of Finance said SC was finalising a framework to clarify the licensing requirements for cash trust schemes that invest in capital market products.
The move comes amid growing public concern over trust-based investment products and the need for stronger investor protection.
Under amendments to the Capital Markets and Services Act 2007 that took effect on Jan 1 this year, SC has gained expanded authority to determine which trust-related activities fall within the scope of regulated capital market services.
The regulator says the forthcoming framework will focus on trusts that invest in capital market instruments such as securities, bonds and unit trusts, while discussions continue with other authorities on broader regulatory coordination.
SC has also begun investigating several trust companies suspected of conducting regulated capital market activities without a licence, although details remain undisclosed while investigations are ongoing.
For now, cash trust products such as those offered by UBB Amanah continue to operate under the legal framework governing trustee services while regulators work to clarify oversight of the sector.
Aida maintains that UBB Amanah’s internal communications have been misinterpreted. “There is nothing irregular or improper about a trust company communicating with its agents regarding options for clients with maturing products. To suggest otherwise demonstrates a fundamental misunderstanding of the trust industry,” she says.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.