

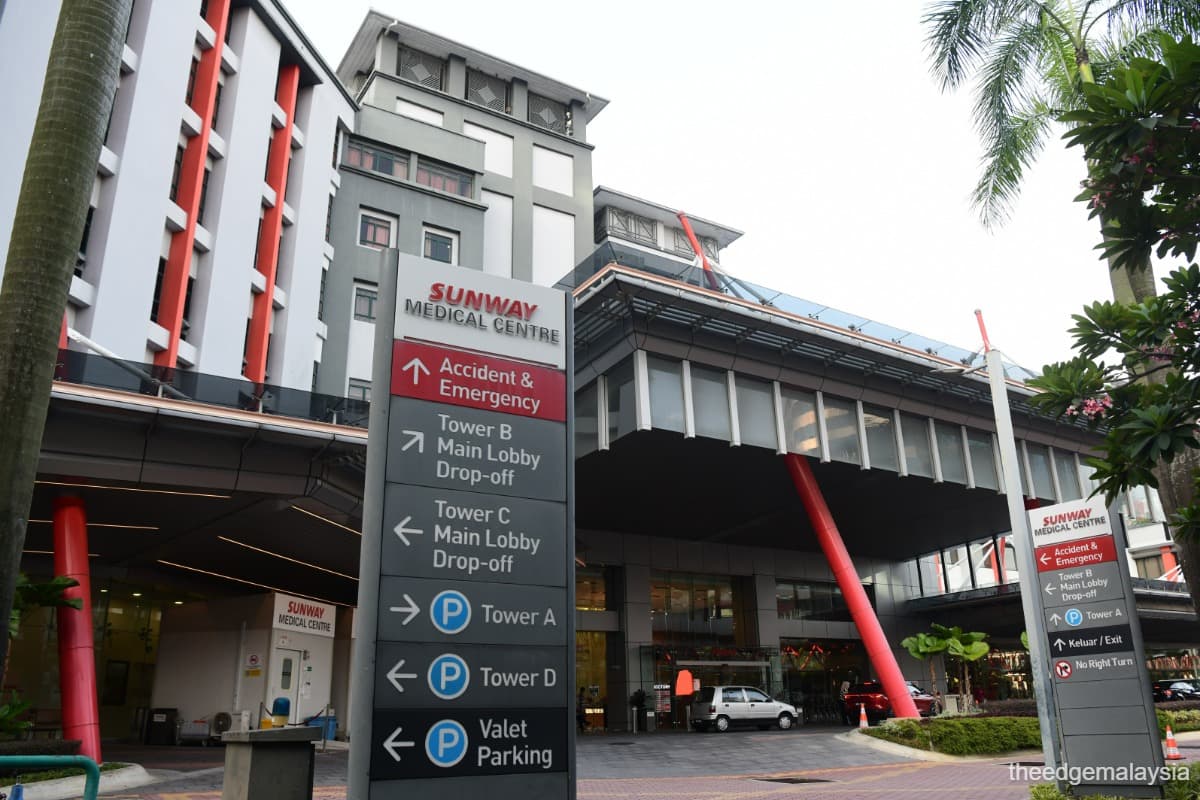
KUALA LUMPUR (March 16): Sunway Healthcare Holdings Bhd, set to debut on Bursa Malaysia’s Main Market on March 18, 2026 at an initial public offering (IPO) price of RM1.45 per share, could immediately qualify for inclusion in the FBM KLCI, replacing QL Resources Bhd (KL:QL), according to CIMB Securities.
The research house noted that QL Resources is currently the smallest KLCI constituent with a market capitalisation of approximately RM13.4 billion, while Sunway Healthcare’s IPO implies a market cap of RM16.7 billion.
Under FTSE Bursa Malaysia’s ground rules, the lowest-ranked constituent will be removed if a new listing’s market cap exceeds it on the first day of closing.
“If Sunway Healthcare’s closing market capitalisation on March 18 exceeds that of QL Resources, it is likely to qualify for inclusion in the KLCI on a T+2 basis, replacing QL Resources.
"Assuming a free float of 18% and a market capitalisation of RM16.7 billion, we estimate Sunway Healthcare’s potential KLCI weight at around 0.5%. The changes in constituents could lead to rebalancing by funds tracking the KLCI index,” said the research house in a note on Monday.
Meanwhile, Hong Leong Investment Bank highlighted that Sunway Medical Centre Sunway City KL is Malaysia’s largest private hospital with 848 licensed beds, anchoring the group’s quaternary care focus. The group operates five hospitals nationwide and plans further expansion into underserved regions.
“Furthermore, Sunway Healthcare is entering the asset-milking stage — characterised by rising profit margin, positive cash flow generation, and progressively higher contributions to group profitability.
“Looking ahead, Sunway Healthcare is expected to deliver bed capacity growth of 13.2% between 2024 and 2030, significantly outpacing peers such as IHH Healthcare Bhd (KL:IHH) (5.1% between 2025 and 2030 at group level) and KPJ Healthcare Bhd (KL:KPJ) (9.3% between 2025 and 2030),” said the research house.
It expects the company to deliver a FY2024-2027 (ending Dec 31, 2027) revenue compound annual growth rate (CAGR) of 19.6%, and forecasts core earnings before interest, taxes, depreciation and amortisation (Ebitda) to grow at CAGR of 21.2%, while projecting profit after tax and minority interests (Patmi) CAGR at 15.1%.
The research house further noted that favourable structural trends — Malaysia’s hospital bed ratio of 2.2 per 1,000 population remains well below the Organisation for Economic Co-operation and Development (OECD) average of 4.6, while demand is driven by increasing preference for private healthcare, ageing demographics, rising prevalence of Congo-related diseases, and medical tourism.
Hong Leong Investment Bank initiated coverage on the company with a ‘buy’ call and a target price of RM1.63, citing the company’s transition into the asset-milking stage, unique advantage from the Sunway ecosystem, stronger bed capacity growth prospects, strong investor demand and potential KLCI inclusion.