

This article first appeared in Digital Edge, The Edge Malaysia Weekly on March 9, 2026 - March 15, 2026
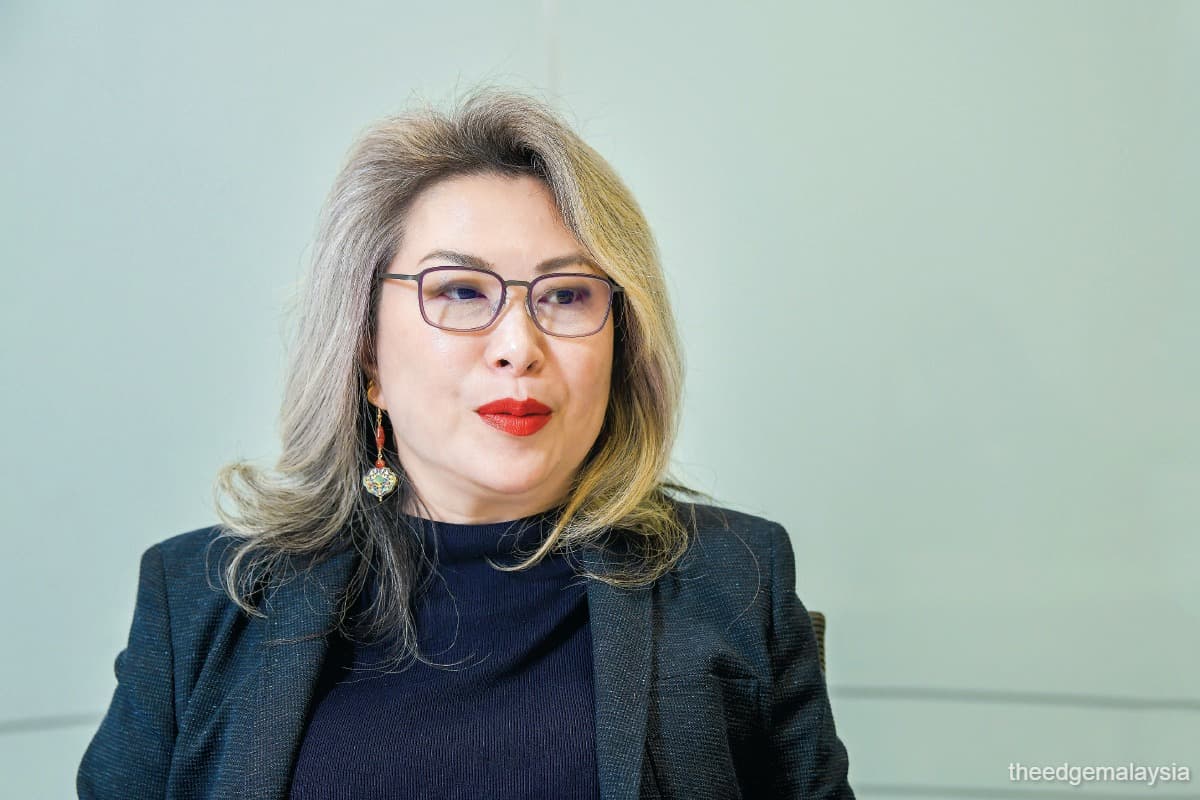
Alliance Bank Malaysia Bhd’s (KL:ABMB) strategy is to go beyond refining financial tools. The bank is building an ecosystem that integrates into customers’ lifestyles, a philosophy its group chief consumer banking officer, Gan Pai Li, describes as being “the bank for life”. This includes forming non-traditional, technology-driven partnerships that deliver value even before a transaction occurs.
Entering her seventh year of her current role, Gan is chasing the final milestones of the bank’s digital ambitions, moving from conceptual blueprints to market realities, focusing on embedding the Virtual Credit Card (VCC) into more lifestyle and living spaces, and working with partners to create a win-win for both the bank and small and medium enterprises (SMEs).
One of Alliance Bank’s more innovative collaborations is with SofaX, a VR technology platform for home furnishing. For mortgage customers, this is not just about the loan; it is about the home. SofaX provides interior design services that are driven by artificial intelligence (AI) for free to Alliance Bank customers, allowing them to visualise furniture and decor in their specific space via the app.
“Partners always bring better ideas,” Gan says, explaining that Alliance Bank then facilitates these lifestyle purchases — such as furniture items on SofaX, which include mattresses — through zero-interest instalment plans as well as encourages customers to visit warehouses and test products before they buy.
The lifestyle pivot is also evident in the bank’s sponsorship of the KL Open Pickleball Championship and its partnership with the Courtside app, which gives VCC cardholders exclusive eight-day advance booking privileges for pickleball courts.
These collaborations allow Alliance Bank to maintain engagement with customers in spaces they already enjoy, moving the bank from a back-end utility to a front-end lifestyle enabler, says Gan.
The bank is not interested in playing a game of catch-up, stresses Gan. Instead, it is orchestrating a digital pivot that seeks to redefine the nature of a credit card, and by extension, the ecosystem.
Gan is betting on a “virtual-first” strategy to leapfrog the competition, driven by a philosophy of giving power and control back to the consumer. This is being done against a backdrop where the traditional boundaries of the fiscal year seem to blur into a continuous stream of digital evolution.
As Alliance Bank is a mid-sized player traditionally known for its strong focus on SMEs, entering the consumer “plastic” market through conventional means would have been an uphill battle against the sheer scale of the giants.
So, the bank needed a different game entirely, starting with moving the goalposts from the physical wallet to the virtual one, specifically the VCC, Gan points out.
AI implementation inevitable
As AI begins to dominate the banking narrative, Gan is taking a pragmatic approach. While many banks are rushing to implement front-facing chatbots, Alliance Bank is focusing its AI efforts on the back end, specifically on credit and risk functions where voluminous data can be processed more efficiently to simplify decisions.
“This year, we’ve seen a much more focused view on trying to get AI in. But it’s not just about bringing in AI; it’s also about getting our people familiar with it,” she says, adding that the groundwork being laid this year is people-focused, ensuring that the bank’s staff know how to use these tools rather than just having the machines in place.
This leads to the bank’s biggest hurdle — talent. Gan speaks of the need for “purple talent”: Individuals who are as comfortable with technology as they are with business and human agency. Hiring these individuals is a challenge, as tech-savvy workers often find fintech start-ups more appealing than traditional banks.
Alliance Bank’s solution is to create opportunities for its bankers to have exposure to new capabilities through interaction with its fintech partners such as Touch ’n Go (TNG). The partnership with TNG is specifically focused on individual consumer lending for the VCC, plastic credit cards and personal loans, providing a platform for the bank to learn from the “open base” and agile methodologies of a dominant digital player.
Despite the aggressive digital push, the bank is not in a hurry to close down its physical branches. The network has been slightly consolidated — from 81 branches to 76 — primarily through relocations to new, burgeoning townships.
“The branch network is still the main engagement point for deposits and for wealth, especially for financial advisory,” Gan explains.
For wealth management, the bank is in the final stages of testing a new system from Polish vendor Comarch. This system is designed to provide relationship managers and customers with a simulated bird’s-eye view of their portfolios, allowing for a collaborative, tech-assisted advisory experience that includes assets held outside the bank if the customer chooses to share.
“Ultimately, technology is not the end goal, but the means of being ‘the bank for life’, one where the customer finally feels like they are in the driver’s seat of their own financial future,” says Gan.
Solving real, tedious digital banking problems
The journey towards Alliance Bank’s VCC started with a very human, very relatable frustration. “One of us had just lost our credit card and we had to replace all the auto-debits,” says Gan.
Anyone who has spent an afternoon painstakingly updating Netflix, Spotify and insurance premium payment details after losing a card knows the friction involved. It was this specific pain point that sparked the question: What if users didn’t have to do that? What if users could isolate every single merchant, creating a single card for every single vendor?
The team began looking at global trends, specifically the success of fintech players like Revolut, and wondered if that level of granular control could be brought to the Malaysian market. Their first stop was Visa to see if the global network could support such unique capabilities.
From there, having obtained internal approvals, the bank spent a year and a half — including delays caused by the global pandemic — building the functions internally to mature the customer journey.
This process requires significant investment, but one that Gan views as essential for survival in a digital-first world. The core design philosophy is centred on giving the control back to users.
Given the constant threat of cyber scams and data breaches, the traditional card number — static and vulnerable — is a liability. The VCC addresses this by allowing users to create unique card numbers for specific merchants.
If a user is anxious about booking a hotel online on a less-familiar international site, they could generate a unique number for that transaction. If that specific number is compromised, the user could simply freeze the number through the app without affecting any other subscriptions or payments.
“It just means that you have the power in your hands to protect your own transaction. A cardholder can freeze the card, and then contact the bank,” Gan explains.
While the bank maintains a robust backroom for fraud monitoring and a centralised fraud unit, the first line of defence is the consumer themselves. This sense of control extends beyond security to financial discipline.
In a feature that Gan personally uses for her children’s e-commerce needs, the VCC allows users to set limits as low as RM1. “I used to pay for subscriptions for my kids ... all on my physical card,” she shares.
“With the VCC, I get to create three separate cards, track what they’ve used it on, and if I see any suspicious transactions, I freeze the card immediately.”
Not only does the VCC form a compelling business case with its security features, it is also cost effective for the bank. Alliance Bank has seen its acquisition cost drop by 83% compared to traditional physical card channels. This is further evidenced by a 40% digital acquisition rate.
The demographics of these early adopters are predictably skewed towards “digital natives”, specifically Millennials and Gen Z who are heavy users of e-commerce platforms like Shopee and Grab, and frequent subscribers to services like Spotify. However, Gan notes that even older “wealth” customers are starting to learn and appreciate the security benefits.
Currently integrated with Samsung Pay and Google Pay, the utility of the VCC is set to expand further with the imminent addition of Apple Pay.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.