

This article first appeared in Capital, The Edge Malaysia Weekly on March 2, 2026 - March 8, 2026
FOR many Malaysian investors, building long-term wealth increasingly means looking beyond Bursa Malaysia. US equities — particularly via exchange-traded funds (ETFs) tracking the Standard & Poor’s 500 index — have become the default allocation, prized for liquidity, breadth and superior historical returns.
Between 2015 and 2025, the S&P 500 delivered a compound annual growth rate (CAGR) of 12.6%, far outpacing the FBM KLCI (2.8%), Hong Kong’s Hang Seng Index (4%), Singapore’s Straits Times Index (5.8%), MSCI World (10.4%) and MSCI Emerging Markets (5.9%). Exposure to roughly 80% of US market capitalisation through a single, low-cost vehicle explains its appeal to investors.
Yet, while investors obsess over expense ratios and tracking errors, the more consequential drag often lies elsewhere — taxation.
The hidden layer: Withholding and estate taxes
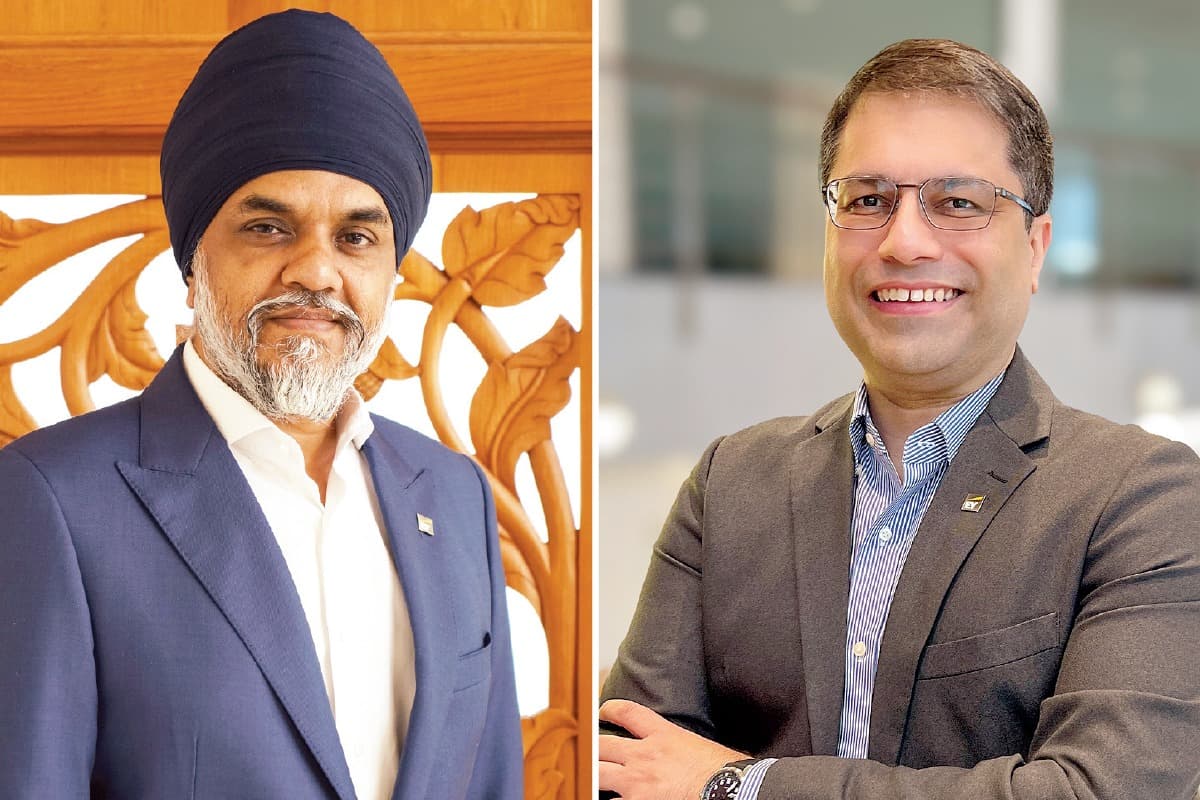
Ernst & Young (EY) Asean tax leader Amarjeet Singh cautions: “Direct holdings in US-domiciled ETFs face a 30% dividend withholding tax, as Malaysia has no tax treaty with the US.”

More critically, US estate tax applies to non-residents holding more than US$60,000 (RM233,188) in US-situs assets — property legally located in the US — with rates of up to 40%. The tax can materially erode the value of inherited portfolios, posing a structural risk for Malaysian investors focused on building generational wealth.
The long-term impact can be severe. A US$50,000 investment in an S&P 500 ETF in 2015 would have grown to about US$163,815 after 10 years. Upon death, however, estate tax could reduce the inherited amount to US$98,289 — compressing the realised CAGR from 12.6% to 7%. For investors building generational wealth, estate tax is a major factor; it is a structural risk that can undo decades of compounding in a single event.
The workaround: Domicile as strategy
A fund’s place of incorporation, or its domicile, determines how its returns are taxed.
EY Malaysia international corporate tax advisory leader Anil Kumar Puri says investors should check whether a relevant tax treaty exists and review the conditions required to qualify for a reduced withholding tax rate.
Essentially, when investing in US stocks through a foreign-domiciled ETF, taxation operates in two layers:
• Level 1: Tax imposed by the US on dividends paid to the ETF; and
• Level 2: Tax imposed by the ETF on distributions to investors.
Therefore, the key is to choose a jurisdiction with a favourable US tax treaty and minimal secondary taxation.
Irish-domiciled ETFs offer structural efficiency. Under the US-Ireland tax treaty, Irish-domiciled ETFs are subject to a 15% US dividend withholding tax — half the standard rate applied to non-treaty investors.
Malaysia also has a double-taxation agreement with Ireland, and non-resident investors are not subject to Irish estate or gift taxes.
The result:
• Dividend withholding is reduced to 15%;
• No US estate tax exposure; and
• No further Irish tax obligations.
For long-term investors, this efficiency outweighs marginal fee differences.
Why Ireland dominates

Irish ETFs typically operate under the Undertakings for Collective Investment in Transferable Securities (UCITS) framework, a European regime that enables cross-border “passporting”, larger fund sizes, tighter spreads and accumulating structures that reinvest dividends automatically. These advantages explain why Irish ETFs account for about 70% of Europe’s ETF market.
For investors without access to European exchanges, Hong Kong-domiciled ETFs offer another estate tax workaround. While dividends remain subject to 30% US withholding tax, Hong Kong imposes no estate tax. The Hang Seng S&P 500 Index ETF, launched in 2024, is one such option.
Buybacks reduce dividend tax impact
With US corporates increasingly favouring buybacks over dividends, the withholding tax gap between domiciles is narrower than many expect. A comparison of Vanguard’s US-domiciled Vanguard S&P 500 ETF and Irish-domiciled Vanguard S&P 500 UCITS ETF from 2013 to 2024 shows cumulative returns of 180.71% and 183.89% respectively — a difference of just US$82 over 12 years once reinvested dividends are factored in.
This underscores the point: While Ireland’s treaty rate improves efficiency, the far more consequential consideration for Malaysian investors is US estate tax — a potential 40% levy that can erase decades of compounding at the point of wealth transfer.
Malaysia’s evolving tax rules
Amarjeet points out that Malaysia’s own tax regime has shifted. Since January 2022, foreign-sourced income remitted into Malaysia has been taxable unless exemptions apply.
“Foreign-sourced dividend income received in Malaysia up until Dec 31, 2026, would be exempted where conditions are met. It has been proposed in Budget 2026 that this exemption period be extended to Dec 31, 2030,” he says.
These conditions include either proof that the dividend was taxed abroad at a rate of at least 15% or compliance with Malaysia’s economic substance requirements — employing staff and incurring operating expenditure locally. For investors, this means that structuring matters: The same dividend can be exempt or taxable, depending on how it is earned and reported.
Capital gains rules have also changed. Since January 2024, Malaysian resident companies, limited liability partnerships, trust bodies and co-operatives have been taxed on foreign capital gains remitted into Malaysia, unless they meet substance requirements.
Individuals remain exempted from taxation on capital gains, but trading gains are treated differently. For institutional investors, the change is significant: What was once a tax-free gain may now be subject to tax.
Navigating the tax minefield
Both experts stress the importance of mitigating double taxation.
Amarjeet warns: “A foreign tax credit can never exceed the Malaysian tax payable on the same income that has suffered foreign tax.”
Where no treaty exists, credits are capped at half the foreign tax suffered. This means investors could face unrecoverable leakage — paying tax abroad and again at home, with only partial relief.
For Malaysian individuals, exemptions on all foreign-sourced income received in Malaysia up until 2036 provide breathing room, but corporate investors must plan carefully.
Anil says: “The absence of a treaty can be costly. Investors should always map their portfolio against Malaysia’s treaty network to avoid unrecoverable tax leakage.”
While performance metrics and domicile strategies dominate investor conversations, Amarjeet and Anil emphasise that taxation is the less visible, but more enduring, determinant of net returns. Their warning is clear: Malaysian investors cannot afford to treat tax as an afterthought when venturing into foreign equities.
Amarjeet explains: “The rules differ significantly depending on where the investment is made, the type of income earned and the investor’s own profile.”
This dual exposure — foreign and domestic — creates a complex overlay that can erode returns if not managed proactively.
Anil reinforces the point: “Tax is not static. Rules evolve, exemptions expire and treaties differ. Investors who fail to anticipate these changes risk losing more to tax than to market volatility.”
Ultimately, the challenge for Malaysian investors is not simply to chase returns but to preserve them. The S&P 500’s 12.6% CAGR may look compelling on paper, but without careful structuring, estate tax, withholding tax and Malaysia’s evolving financial services industry regime can erode much of that advantage.
Amarjeet concludes: “The tax implications of investing abroad are not straightforward and can differ significantly based on the jurisdiction and the investor’s profile.”
For investors seeking to build generational wealth, understanding the tax terrain is as critical as choosing the right index.

Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.