

This article first appeared in The Edge Malaysia Weekly on February 23, 2026 - March 1, 2026
MALAYSIA was in the lead among Asean countries in the number of initial public offerings (IPO) in 2024 and 2025, thanks to the popularity of ACE Market listings. Yet it is Indonesia that has joined advanced markets such as Singapore and Hong Kong in allowing dual-class shares (DCS) or multiple-voting shares (MVS), preferred by tech entrepreneurs when going for listing.
Notwithstanding Indonesia’s long-standing low free-float issue that was recently flagged by index provider MSCI Inc, the archipelago allowed MVS on Dec 2, 2021, paving the way for the listing of its local tech giant PT GoTo Gojek Tokopedia Tbk in April 2022.
Incidentally, Grab Holdings Ltd — the ride-hailing company turned fintech giant, co-founded as MyTeksi in Kuala Lumpur in 2012 by Malaysia-born Anthony Tan and Tan Hooi Ling before relocating its headquarters to Singapore in 2014 — listed on Nasdaq on Dec 2, 2021 with DCS.
The silence on DCS in Malaysia is telling, given that almost three years have elapsed since Prime Minister and Finance Minister Datuk Seri Anwar Ibrahim reintroduced the proposal — when retabling Budget 2023 in February of that year — to spur listings of high-growth technology firms.
DCS essentially permits tech entrepreneurs to have more voting rights with less capital — meaning one share, more votes. The structure is designed to recognise talent as a form of capital and to provide temporary protection for founders during the capital intensive growth phase, when profits may remain elusive and investor pressure is high.
Detractors of DCS cite corporate governance-related concerns and flag the need for safeguards for investor protection and prevention of abuse. Supporters, however, argue safeguards dilute the allure to tech entrepreneurs. Others question if Malaysia needs to consider DCS, given there is already a robust IPO pipeline and a chequered track record among foreign listings here.
Apart from corporate governance-related concerns, another key reason Malaysia seems to be in no hurry to introduce DCS may well be because Indonesia has more unicorns and decacorns, basically technology start-ups valued at more than US$1 billion (RM3.9 billion) or over US$10 billion respectively.
The Securities Commission Malaysia (SC) had acknowledged the role of DCS.
“Allowing dual-class share structures will help high-growth, innovative companies to the Malaysian capital market, allowing investors access to more diversified investment opportunities,” the SC’s former chairman Datuk Seri Awang Adek Hussin said in a statement dated Feb 24, 2023, welcoming capital market-related measures mentioned in Budget 2023. He was succeeded by the current SC chairman Datuk Mohammad Faiz Azmi on June 15, 2024.
It remains to be seen if the SC would allow DCS when unveiling the Capital Market Masterplan 4 (CMP4), covering 2026 to 2030, to reinvigorate the capital market.
If Malaysia decides to go ahead, it should have some benefit of hindsight and lessons from regional markets, given that Hong Kong and Singapore have since 2017 introduced such structures to attract and retain high-growth technology companies or those in the new economy, followed by Shanghai in 2019.
Necessary safeguards

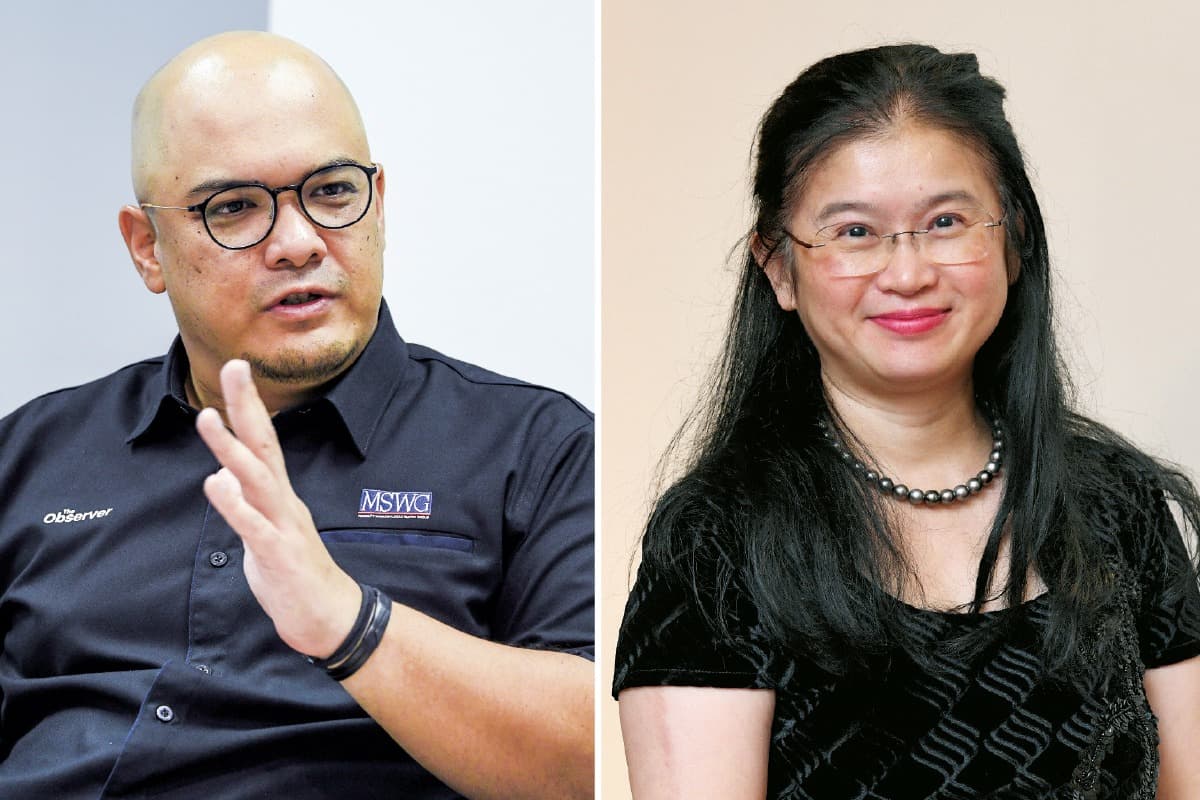
Ismet Yusoff, CEO of Minority Shareholders Watch Group (MSWG), says it “approaches the issue of dual-class or weighted voting shares with caution”.
“We believe the slow introduction and adoption of DCS structures in Malaysia reflects long-standing corporate governance concerns, the need for substantive legislative and regulatory amendments, and regulators’ prudence in balancing market innovation with robust investor protection,” he says, noting the need to amend both the Companies Act 2016 and Bursa Malaysia’s Listing Requirements, which adheres to the principle of one vote per share.
“As an organisation that advocates for minority shareholder protection and market integrity, our starting point remains the one-share-one-vote principle, which underpins accountability and investor confidence. International experience and governance research have shown that dual-class structures can, over time, weaken checks and balances and create misalignment between control and economic ownership.
“That said, we acknowledge that capital markets are evolving and welcome the SC’s decision to seek public feedback on a broader listing framework. The consultative process itself recognises that dual-class shares are not the only or inevitable pathway to enhancing Malaysia’s listing attractiveness, and that any reform must be carefully weighed against its long-term implications for governance and investor trust.
“In the absence of strong safeguards, DCS structures risk entrenching founders or management, potentially enabling them to prioritise personal or related-party interests, for example, remuneration or RPTs (related-party transactions), over the interests of minority shareholders. This could weaken accountability, suppress shareholder dissent and undermine active investor engagement. Highly concentrated voting power may ultimately allow controlling parties to pursue agendas misaligned with the long-term interests of the wider shareholder base.”
If dual-class shares were to be considered, Ismet says MSWG’s support “would be highly conditional and limited to exceptional circumstances”.
“Any such framework would need to be accompanied by strong and clearly defined safeguards to preserve market confidence and protect minority shareholders. These would include restricting such structures to new listings only, clear and enforceable sunset mechanisms to ensure an eventual reversion to one-share-one-vote, limits on the concentration of voting power, enhanced board independence, and robust minority protections on key decisions such as related-party transactions and changes in control,” he says.
“In addition, transparency and ongoing regulatory oversight would be critical, as global experience suggests that safeguards are often challenging to enforce in practice. From MSWG’s perspective, these protections are fundamental and cannot be treated as optional trade-offs.”
Ismet, who was previously CEO of the Malaysian Institute of Corporate Governance (MICG) and had contributed to the development of corporate governance-related guidelines when he was with the SC, reckons that the “evidence that dual-class shares alone would significantly alter listing decisions remains mixed and far from conclusive”.
“In practice, companies, particularly technology firms, assess a wider range of factors when choosing where to list, including market liquidity, valuation outcomes, depth of institutional capital, regulatory certainty and post-listing credibility. While dual-class structures may appeal to a narrow segment of founders, they can also lead to governance-related valuation discounts and heightened investor scrutiny. We therefore believe that Malaysia’s competitive advantage lies in maintaining strong governance standards, regulatory credibility and a supportive market ecosystem, rather than diluting shareholder rights,” Ismet says, noting that the SC’s “decision to consult widely on the new framework reflects an understanding that there are multiple ways to attract quality listings without relying solely on dual-class structures”.
Moving with the times

Datin Wong Muh Rong, managing director of Astramina Advisory Sdn Bhd, is fully supportive of the introduction of DCS.
“The introduction of DCS structures is critical if Bursa Malaysia is to position itself as a credible alternative platform for AI (artificial intelligence) and technology companies, particularly those seeking to list via M&A (mergers and acquisitions) routes such as reverse takeovers or backdoor listings using a market-capitalisation-based assessment framework. For founder-led, innovation-driven businesses, retaining strategic control is often a prerequisite for accessing public capital. Without DCS, Malaysia will remain structurally disadvantaged in competing for such listings,” Wong says.
Singular Asset Management founder and chief investment officer Teoh Kok Lin also sees introduction of DCS as “a critical catch-up” for Malaysia’s stock market.
“We must accelerate [DCS] immediately. While we debate, our neighbours moved on years ago — Hong Kong and Singapore in 2018, Indonesia in 2021. We likely lost unicorns to Nasdaq or Singapore during this delay. We cannot attract founder-led tech if we force immediate dilution. Investors will accept fewer voting rights for growth, provided we enforce sunset clauses (10 years, for example) to eventually normalise governance,” Teoh says.
“Given the competitive landscape among our regional peers — where Hong Kong, Singapore and Indonesia already permit weighted voting rights — it will be timely for our regulators to accelerate implementation of a Malaysian DCS regime with strong safeguards to protect minority investors,” says CGS International Securities Malaysia CEO Khairi Shahrin Arief Baki, recalling that Malaysia announced the intention in the revised Budget 2023 to attract founderled, highgrowth issuers.
Ding Su Lynn, partner for Corporate Finance at Baker Tilly Malaysia, says DCS can attract founder-led growth companies, but should only be allowed with strong safeguards such as sunset clauses for minority protection.
Tradeview Capital Sdn Bhd CEO Ng Zhu Hann concurs, noting that the DCS structure is “widely adopted in US, especially in the tech sector”.
“If we want to attract more companies of this manner, it is a good idea. However, the danger lies with actual management control being tied to shareholding to ensure alignment of interest. This is a fine line to walk.”
Indeed, investor protection is important in a robust capital market. Malaysia will need to decide on the right balance of safeguards while paving the way for current and future home-grown technology champions to consider Bursa Malaysia as its choice listing destination where local institutions have ample liquidity.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.