

This article first appeared in The Edge Malaysia Weekly on February 16, 2026 - February 22, 2026


MALAYSIA’S express delivery companies expect margin pressure to persist this year as an entrenched price war shows little sign of easing. With no respite on the horizon, incumbents and disruptors alike are taking matters into their own hands by strategically diversifying their revenue streams to stay afloat and expanding into areas traditionally served by full-service logistics providers.
While remaining committed to last-mile delivery, Ninja Logistics Sdn Bhd (Ninja Van Malaysia) — one of the disruptors that entered the market in 2015 — is responding to intense competition by expanding into higher-margin integrated logistics services, such as cold chain, warehousing and cross-border freight. The strategy is to reduce reliance on commoditised parcel delivery, where pricing power has eroded.
Established players are also recalibrating. Incumbents like Pos Malaysia Bhd (KL:POS) and GDEX Bhd (KL:GDEX) have revamped operating models and stepped up technology adoption to stay competitive.
Pos Malaysia began a transformation programme in 2021, shifting from being a purely mail operator to a technology-driven logistics group with expanded offerings spanning retail, logistics, aviation and digital services.
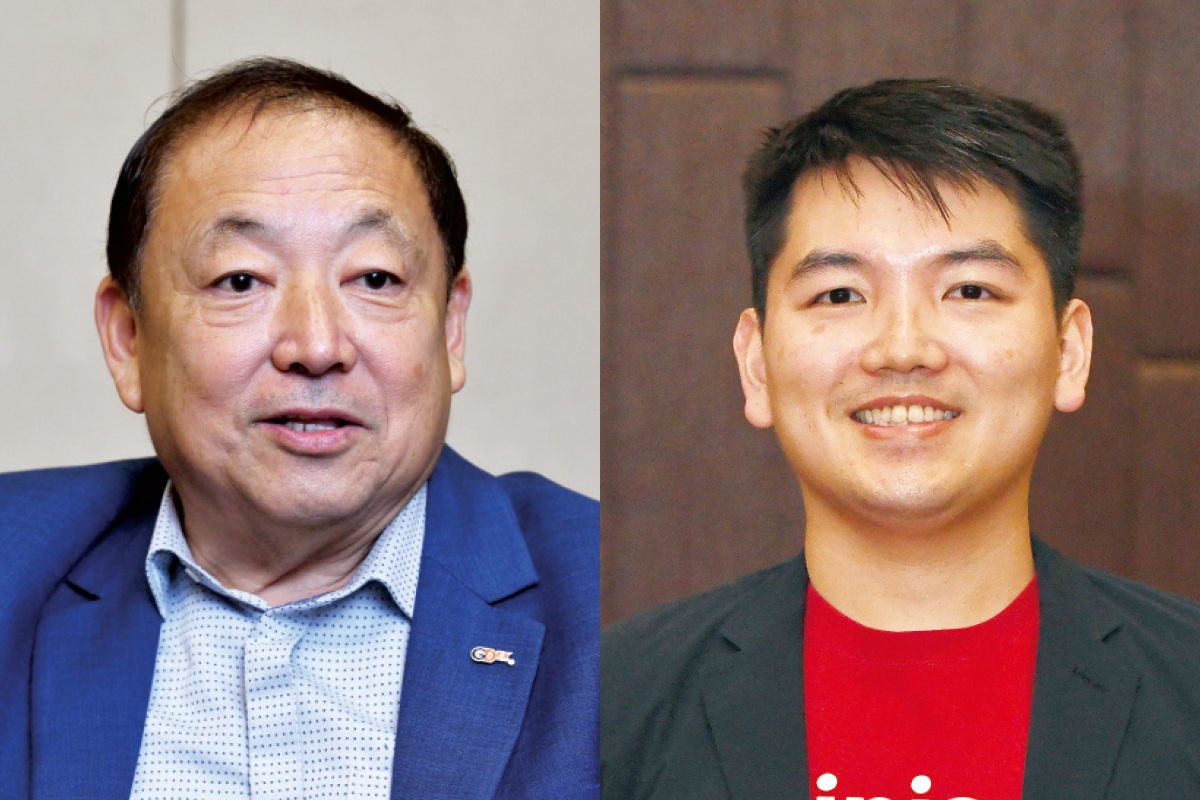
GDEX managing director and group CEO Teong Teck Lean says the group’s pivot towards the provision of information technology (IT) services and solutions such as smart retail management systems, web and enterprise solutions as well as cybersecurity software distribution, has gained traction since its launch in 2022.
The initiative, branded as “GDEX 2.0”, focuses on service differentiation and integrated digital offerings, reducing the group’s exposure to aggressive price competition in courier services.
“Under GDEX 2.0, we’ve rethought how the business should operate by integrating digital services into logistics. When customers require end-to-end solutions, pricing becomes less sensitive. The GDEX 2.0 concept is starting to mature and this year may not be a bad one for us,” Teong tells The Edge.
Losses persist across the sector
The prolonged price war has weighed heavily on earnings across the sector.
Pos Malaysia’s net loss widened to RM132.17 million for the nine months ended Sept 30, 2025, from RM125.5 million the previous year. The national postal company has remained in the red since the quarter ended Sept 30, 2018.
GDEX has been making losses since the quarter ended March 31, 2022. After a brief reprieve in the three months ended Dec 31, 2024, GDEX was back to reporting quarterly losses. For the nine-month period ended Dec 31, 2025, however, its net loss narrowed to RM4.96 million from RM6.52 million a year earlier, as its strategic pivot gained traction.
Companies Commission of Malaysia filings show Ninja Van Malaysia recorded losses for three consecutive financial years through the year ended June 30, 2024 (FY2024), after posting a record net profit of RM23.82 million in FY2021. Its diversification into the broader logistics segment helped narrow its net loss to RM3.41 million in FY2024, from RM83.4 million in FY2023.
In contrast, Indonesia-based J&T Express (Malaysia) Sdn Bhd returned to profitability in the financial year ended Dec 31, 2024, posting a net profit of RM69.94 million after losses of RM44.7 million in FY2023 and RM179.14 million in FY2022.
Still, GDEX’s Teong does not expect pricing pressure to subside anytime soon.
In December 2024, the Malaysian Communications and Multimedia Commission (MCMC) introduced reference pricing guidelines, including a RM5 floor price for parcels weighing 2kg and below, to curb predatory pricing. Operators have largely disregarded the guidelines, citing their non-binding nature.
Last November, Communications Minister Datuk Fahmi Fadzil said the MCMC was studying a proposal to introduce a mandatory floor price for courier services. Express delivery players, however, are not optimistic that the move will materialise in the near term.
“Even if the government agrees, it must go through parliament and be gazetted under the Postal Services Act 2012. That will take time. Rather than wait, we have to focus on building our new business model,” says Teong.
Ninja Van Malaysia CEO Lin Zheng says he supports the move to regulate the industry but cautions that setting the right floor price is complex.
“If it’s too high, it raises costs across the board and creates friction for e-commerce. If it’s too low, it defeats the purpose. The final price point will determine whether it helps stabilise the industry,” he opines.
Lin says the company has been engaging with the MCMC to provide input on what constitutes sustainable pricing.
“Ultimately, it is up to the government to decide. More efficient players may be able to operate at lower prices but those cutting rates purely to gain market share are unlikely to sustain that strategy over the long term.”
Consolidation underway
Following an unprecedented boom during the Covid-19 pandemic, when online shopping became an indispensable part of daily life and attracted a new breed of player that is tech-savvy and backed by private equity funds, the sector is now consolidating. Several players, including Nationwide Express Holdings Bhd, Pgeon Delivery, Flash Express Malaysia and CJ Century Logistics Holdings Bhd’s (KL:CJCEN) courier arm, have exited or divested.
The liberalisation of the courier industry in 2012 led to the proliferation of operators, with as many as 130 to 150 companies previously active, Teong recalls. That number has since fallen below 100 after one or two courier firms ceased operations in the past month.
According to the MCMC, there were 102 courier companies as at Oct 15, 2025. Of these, 21 were foreign owned while 81 were locally based. J&T Express and Shopee’s logistics partner SPX Xpress (Malaysia) Sdn Bhd remain the largest names in the sector, jointly controlling 73.5% of the domestic market.
“Unlike before, when a new entrant appeared almost every month, the pace has slowed. Even if new players enter, they are less likely to dump prices as aggressively as in the past,” says Teong.
The continued growth in trade, along with double-digit expansion in e-commerce, offers a silver lining, as it is expected to support delivery volumes while competition stabilises.
GDEX expects improved performance this year, underpinned by higher delivery volumes and reduced losses from its Vietnam unit. The group is also resuming capital expenditure to expand capacity, including the purchase of electric delivery trucks. “In the past five years, we did not build additional delivery capacity,” Teong explains.
In a Feb 3 report, Apex Securities projects GDEX’s core earnings to rise to RM19.4 million in FY2026, RM36.8 million in FY2027 and RM46.5 million in FY2028, representing a compound annual growth rate (CAGR) of 55%. The growth is expected to be driven by a recovery in the domestic express delivery and logistics business; cost-cutting measures at its Vietnamese unit Noi Bai Express and Trading Joint Stock Co (Netco); increased revenue and profit from its newly launched GD Xchange ecosystem of digital solutions; and further internal cost optimisation initiatives.
Ninja Van Malaysia is doubling down on integrated logistics, expanding last-mile services, cold chain capabilities and its Ninja B2B Restock inventory solution. In its cold chain segment, the company currently handles more than 100,000 parcels per month and plans to increase this capacity.
“For 2026, our plan is to be more efficient in our network and optimise routes to provide better service,” says Lin.
“Integrated logistics is really the next competitive edge. Offering multiple services through a single provider is what we will continue to develop this year,” he adds.
Lin acknowledges the fact that the express delivery market is “saturated” compared with pandemic-era growth rates. Courier fees remain depressed and volume growth increasingly depends on merchants’ pricing power and platform commission structures rather than shipping rates.
“That’s why, over the past two years, we have focused on diversification, providing integrated logistics solutions for our customers — from last-mile delivery to B2B, cold chain, cross-border logistics and warehousing.
“Customers focus on selling; we handle the logistics. That helps with their growth,” he says.
“We will maintain our last-mile delivery business, which is expected to deliver stable growth, while other segments such as cross-border, warehousing and B2B are projected to expand at a faster pace,” he adds.
Lin notes that lower pricing is not the main driver of volume. “The main factor is the shipper’s ability to absorb costs. Those who can absorb higher costs can achieve greater volume, while others must adjust prices to remain sustainable.”
“That may have some impact on costs but, overall, volumes are still rising as e-commerce purchasing trends have grown steadily over the years,” he says.
Ninja Van Malaysia expects its domestic parcel volumes to rise by 5% to 10% in 2026 from last year’s 20 million recipients, in line with the projected 5% annual growth in Malaysia’s logistics market to RM153.78 billion by 2030 from RM117.36 billion last year.
Asked when Ninja Van Malaysia might turn profitable, Lin says, “That’s a question we ask ourselves every year but we do see the industry consolidating a bit, which eases some of the pressure. If there’s further consolidation this year, it could benefit the sector by preventing prices from falling further.
“That said, the competition remains. We need to focus on differentiating ourselves rather than going head-to-head with everyone,” he adds.
“Hopefully, within a year or two, we can turn profitable. We are seeing recovery signs from our diversification efforts, which also provide a more sustainable long-term path for the business.”
At the group level, Lin says a stock market debut for Ninja Van remains on the back burner, with profitability taking priority. “Our focus is on building a sustainable business. While we remain open to an initial public offering or other capital market moves, there is no timeline.”
Ninja Van operates in seven markets — Singapore, Malaysia, Indonesia, Thailand, the Philippines, Vietnam and China. Indonesia is its largest revenue contributor, followed by Malaysia.
Logistics to ride e-commerce boom
Kenanga Research expects growth in Malaysia’s logistics sector to remain steady into 2026, benefiting from the booming e-commerce market, a global tech upcycle driven by AI demand, a resilient US economy and potential trade diversion amid US-China tensions.
“The domestic logistics sector still fared well as Malaysia’s total trade grew 5.4% year to date through October 2025 versus a full-year 2024 growth of 9.2%. Trade surplus remained high at RM125 billion over the same period versus RM139.1 billion in 2024, especially in the domestically driven third-party logistics sector, which is less vulnerable to external headwinds, being buoyed by the onshoring business trend and e-commerce boom,” it says in a Jan 5 report.
According to the research house, industry experts project local e-commerce gross merchandise volume to grow at a CAGR of 5% from 2024 to 2027, reaching RM1.5 trillion by 2027 from RM1.2 trillion in 2024.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.