

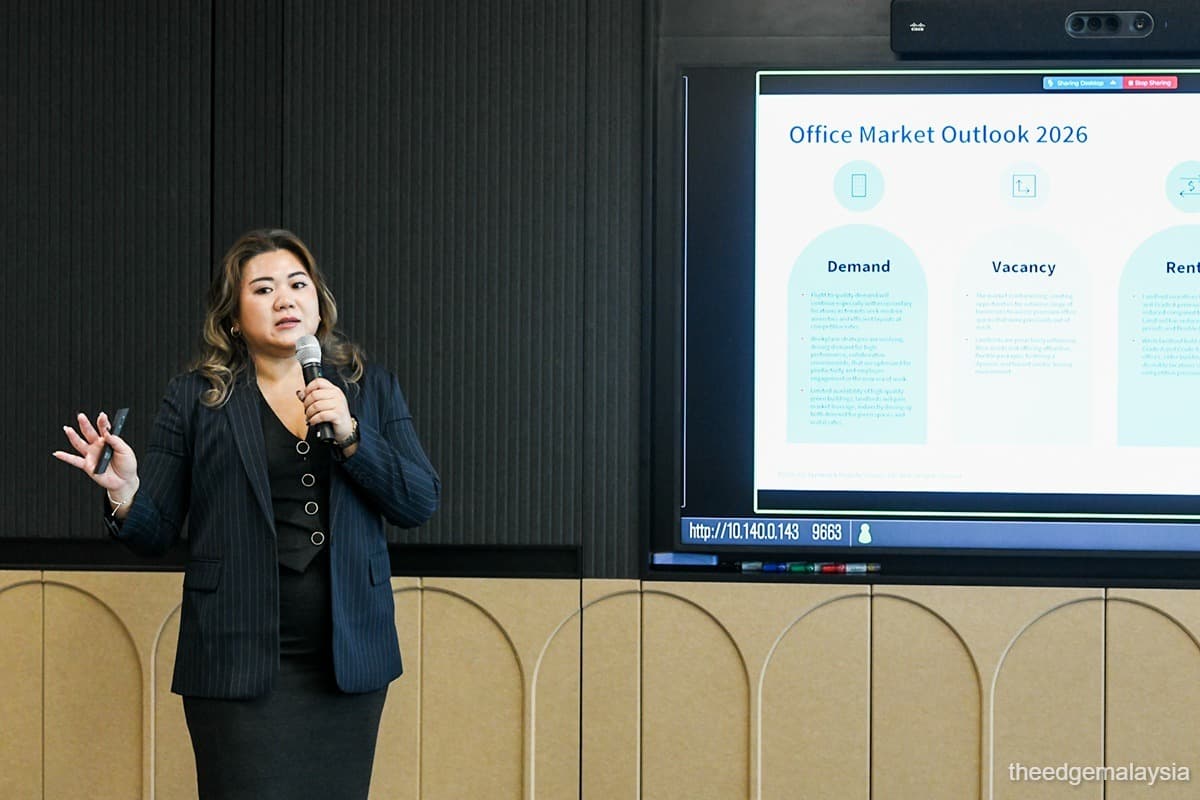
KUALA LUMPUR (Jan 27): The Greater Kuala Lumpur office market is expected to turn increasingly landlord-favoured over the next few years, as a tightening pipeline of Grade A office space coincides with sustained flight-to-quality demand, according to JLL Malaysia at its 4Q2025 press conference on the Malaysian property market on Tuesday.
“As a result, demand pressure is expected to intensify in KL city and fringe locations, potentially shifting the market towards a landlord-favoured position in the medium term,” said JLL Malaysia head of office leasing advisory Quiny Lee.
Lee said net absorption reached about 430,000 sq ft in 4Q2025, as businesses undertook strategic relocations and space consolidation exercises. Vacancy rates improved across all submarkets, with Kuala Lumpur city at 18.6%, KL fringe at 6.7%, and decentralised locations at 22%.
However, supply constraints are expected to emerge from 2027 onwards, with very limited non-strata Grade A office completions scheduled between 2027 and 2028.
“Only one new Grade A office building — The Capitol at Bandar Utama, Petaling Jaya — is expected to be delivered in 2027 in a decentralised area, while no new supply is anticipated in 2028,” Lee said.
On the shortage of new office supply, Lee said developer decisions continue to be influenced by investment returns. “Office rentals and yields are not as attractive as what developers would want them to be.”
She added that tenancy structures in Malaysia also affect development appetite. “In Malaysia, we don’t usually practise long-lease agreements — we practise tenancy agreements. Most tenants are only looking at three-year terms, and that affects how developers plan to build.”
Lee noted that much of the supply originally planned before and during the pandemic has already been delivered, contributing to the reduced pipeline in the coming years.
“This is where we expect pressure to build — in terms of tighter vacancy and firmer rents,” she said, adding that rental performance has already shown early signs of upward pressure, with overall achievable office rents averaging RM6.81 psf per month in 2025, reflecting 0.33% of year-on-year growth amid tightening supply.
Nevertheless, Lee stressed that developers remain cautious. “The key reason developers are not rushing to build new office buildings is because from an investment and yield perspective, office assets are still not as attractive compared with other alternative markets.”
Looking ahead, Lee said the Greater Kuala Lumpur office market will continue rebalancing as future Grade A supply tightens. Landlords of Grade A and premium Grade A buildings are expected to gain greater market leverage, supporting firmer rents and reduced incentives.
At the same time, older buildings and less desirable locations will continue to face competitive pressures, prompting landlords to enhance, reposition or adopt more flexible leasing strategies as occupier demand remains firmly anchored on quality space.
Meanwhile, JLL Malaysia managing director Jamie Tan said that 2026 would be a bit more volatile amid continued geopolitical turmoil, with investors being more selective. “Outperformers of 2025 such as data centres and the industrial sector are also expected to continue performing, and doing well in 2026,” said Tan.