

This article first appeared in The Edge Malaysia Weekly on January 19, 2026 - January 25, 2026
BIGGER has not always meant better for shareholders in Malaysia’s corporate landscape. Despite bold strategic narratives and ambitions to create national champions, some mega mergers have struggled to translate scale into sustainable value, raising doubts over whether headline-grabbing deals truly serve long-term investor interests.
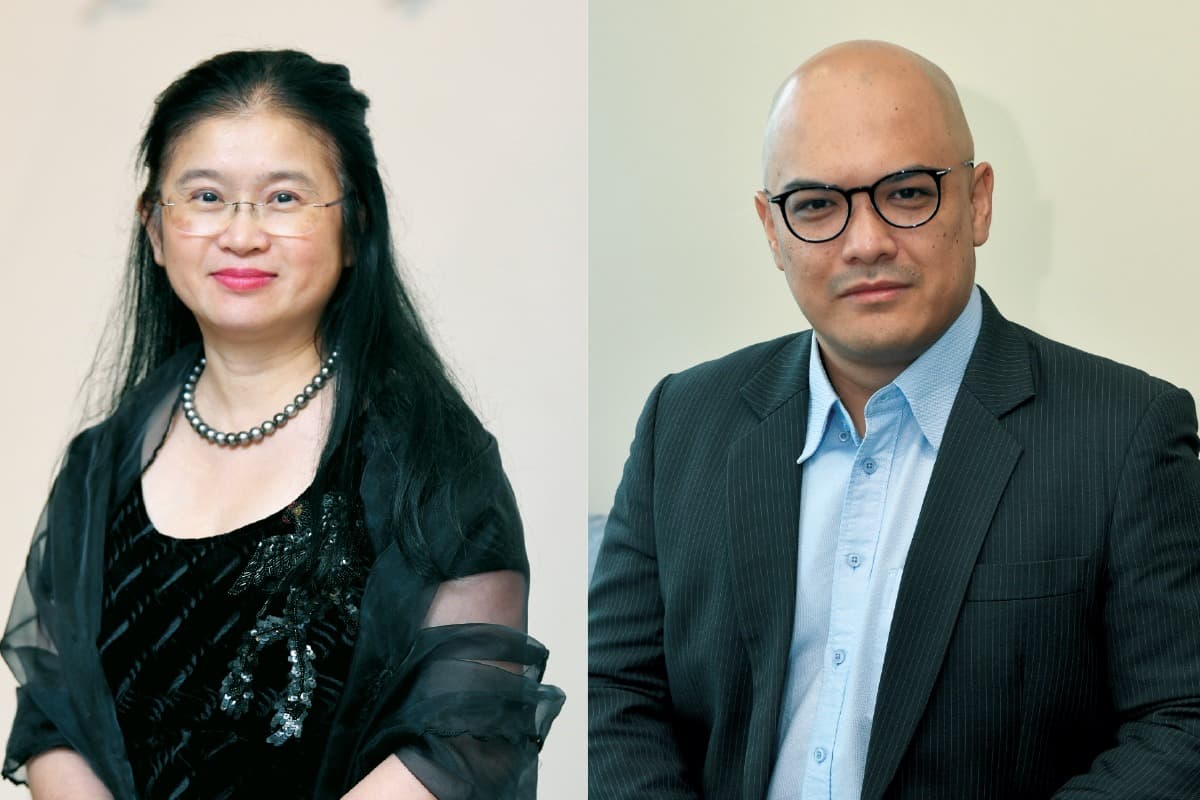
Astramina Advisory Sdn Bhd founder and managing director Datin Wong Muh Rong observes that mega mergers in Malaysia have generally failed to create sustained shareholder value.
While the strategic rationale behind such transactions is often compelling, she says execution risks, balance sheet stress and overestimated synergies have frequently undermined the original investment case.
She cites Synergy Drive Bhd — which consolidated nine listed companies into a single Sime Darby conglomerate — as a case in point.
“Despite its ambition to create a national champion, the complexity of managing multiple unrelated businesses eventually diluted operational focus and capital efficiency. The outcome was telling: the group was later demerged into three sector-specific listed companies, effectively reversing the mega merger,” she notes.

The demerger of Sime Darby (KL:SIME) into Sime Darby Plantation Bhd (now SD Guthrie Bhd [KL:SDG]) and Sime Darby Property Bhd (KL:SIMEPROP) was carried out in 2017 under a pure-play strategy aimed at unlocking value.
Wong also points to the merger between Sapura Crest Petroleum Bhd and Kencana Petroleum Bhd — later renamed Sapura Energy Bhd — which came at the cost of significant leverage. The oil and gas services group was unable to service its debt when the Covid-19 pandemic struck, compounded by deteriorating industry conditions. Now known as Vantris Energy Bhd (KL:VANTNRG), the group is still working towards an exit from Practice Note 17 (PN17) status.
“In this case, scale magnified financial risk rather than resilience,” she sums up.
More value seen from mid-sized mergers
Nonetheless, Wong sees valuation creation in focused, mid-sized mergers.
“The merger between IJM Corp Bhd (KL:IJM) and Road Builder Group is a good example, where complementary operations and disciplined execution led to clear earnings accretion and genuine synergies.
“For a healthier capital market, Malaysia should encourage more mid-sized M&A (mergers and acquisitions) transactions rather than headline-driven mega mergers. Mid-sized deals are typically earnings-accretive, less debt-dependent and easier to integrate,” she explains.
To facilitate more mid-sized M&A transactions, Wong says regulatory reform is needed, particularly for reverse takeovers and backdoor listings.
“Allowing market capitalisation to be used as an additional qualifying criterion would facilitate more M&A activity, attract quality regional companies, and improve capital recycling within Bursa Malaysia,” she opines.
She adds that Malaysia should welcome foreign and regional companies via M&A routes.
“Many fast-growing, asset-heavy or technology-focused businesses may not yet be profitable, but have strong valuations and growth visibility. Excluding them by rigid profit tests pushes them to remain private or list elsewhere,” she observes.

Interestingly, IJM itself — formed in 1983 — was the result of a merger between three medium-sized construction firms, namely IGB Construction Sdn Bhd, Jurutama Sdn Bhd and Mudajaya Sdn Bhd. In 2008, IJM acquired the Road Builder Group, cementing its position as one the largest builders in Malaysia.
Turning to the property sector, one of the most notable mega mergers was the 2010 merger of UEM Land Bhd and Sunrise Bhd, which became UEM Sunrise Bhd (KL:UEMS).

Since then, the sector has faced persistent headwinds, including property cooling measures, overhang and economic downturns. After peaking at RM3.65 in May 2013, UEM Sunrise’s shares have remained under pressure, falling below RM1 in 2018 and subsequently below 20 sen in 2022. The stock closed at 65 sen last Friday for a market value of RM3.3 billion.
In comparison, the Bursa Malaysia Property Index was down about 17% between May 2013 and mid-January 2026.
UEM Sunrise’s earnings per share has also plunged over the same period, declining from 13.3 sen per share in 2013 to an annualised 1.6 sen in 2025.
It is also worth noting that UEM Group Bhd mooted a plan in 2020 to merge UEM Sunrise with Eco World Development Group Bhd (KL:ECOWLD), although the proposal was called off a year later.

Minority Shareholders Watch Group CEO Ismet Yusoff says it is difficult to generalise that past mega mergers in Malaysia have consistently created shareholder value.
“There is no strong or conclusive body of evidence — whether from empirical research or market experience — showing that large-scale corporate mergers in Malaysia reliably deliver sustained value for acquiring companies and their shareholders,” he says.
This, he adds, mirrors global and historical trends.
“Internationally, many mega mergers have struggled to generate long-term shareholder value for the acquirer, often due to integration complexity, cultural mismatches, execution challenges and synergies that were overestimated but failed to translate into meaningful cost savings or cash flow improvements.”
As such, Ismet stresses that merger success hinges on strong strategic and operational fit, disciplined execution and conservative deal pricing, rather than sheer scale.
“For a merger to be genuinely accretive, it must enhance cash flows on a per-share basis. In particular, the target’s cash flow yield should exceed the acquirer’s marginal cost of capital, resulting in immediate and sustainable cash flow accretion. This must be achieved without excessive financial engineering,” he adds.
Take CelcomDigi Bhd (KL:CDB) as an example. Its integration process is still ongoing more than three years after the merger was completed in November 2022. Network modernisation is about 90% complete, while information technology consolidation has exceeded 80%. The merger is expected to deliver RM700 million to RM800 million in annualised operating expense savings by 2028.
Capital discipline, Ismet stresses, is equally critical.
“The acquiring party should pursue transactions at fair and conservative valuations, avoid over-reliance on leverage, and base synergies on realistic, achievable assumptions. It has to ensure that the deal does not materially dilute earnings, dividends or balance sheet strength.”
While it is not uncommon for corporates and controlling shareholders to reassess asset portfolios and capital structures during periods of market uncertainty or valuation dislocation, he says any corporate exercise must be underpinned by a clear strategic rationale, robust governance and fair treatment of all shareholders — particularly minorities.

Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.