

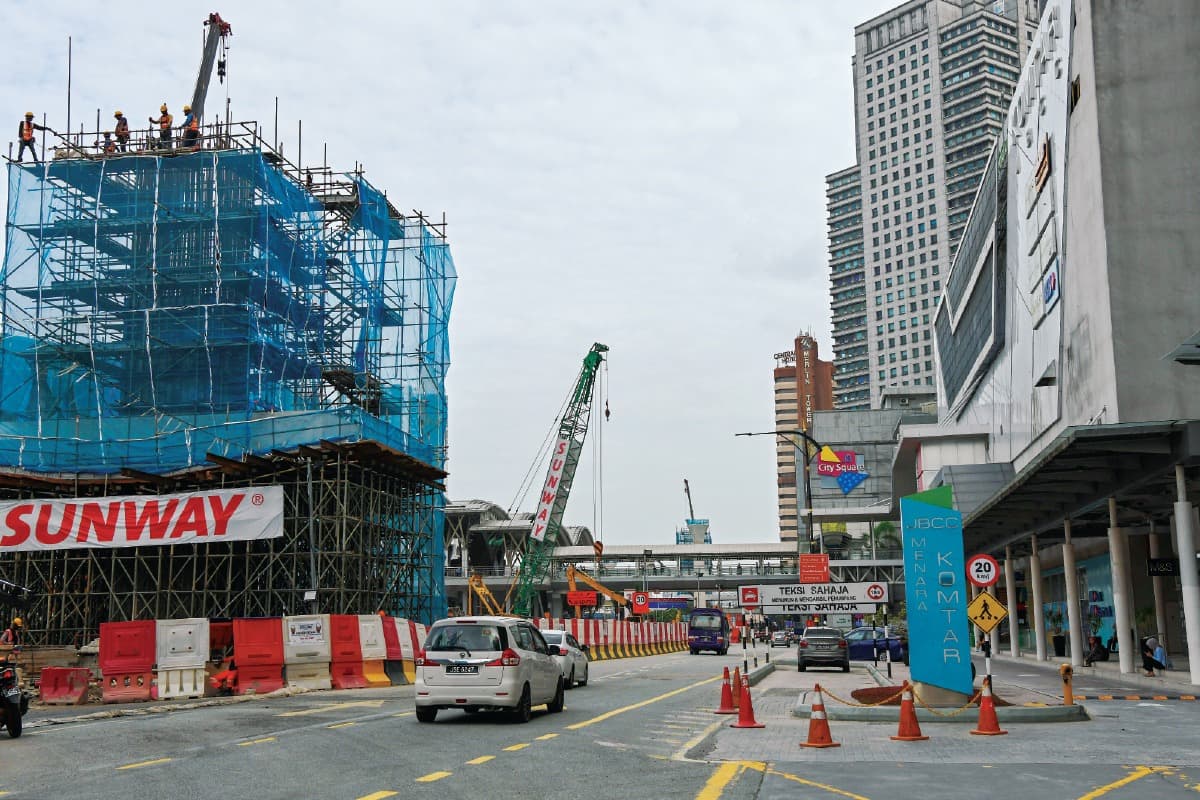
This article first appeared in The Edge Malaysia Weekly on January 19, 2026 - January 25, 2026
IJM Corp Bhd (KL:IJM) went from one milestone to another on the back of mergers and acquisitions in the first three decades of its history. From the merger between IGB Construction Sdn Bhd, Jurutama Sdn Bhd and Mudajaya Sdn Bhd in 1982 to the acquisition of Road Builder (M) Holdings Bhd and later Kumpulan Europlus Bhd, the conglomerate was built on the assets and capabilities of these companies.
Now, IJM is a takeover target.
Sunway Bhd (KL:SUNWAY) has made a buyout offer of RM3.15 per share to IJM in a cash and shares deal that values the latter at RM11 billion. IJM’s total assets amounted to RM11.25 billion at end-September 2025.
As Sunway’s share price is currently at a peak, the company only needs to fork out RM1.1 billion in cash and issue 1.75 billion new shares for the takeover exercise. The number of consideration shares issued will be roughly equivalent to 25% of its existing issued share capital of 6.8 billion.
Sunway Group’s founder Tan Sri Jeffrey Cheah and his family will remain the largest shareholder of Sunway, with 49% held via Sungei Way Corp Sdn Bhd and 9.5% via Jef-San Enterprise Sdn Bhd.

Meanwhile, the Employees Provident Fund (EPF) is a shareholder of both IJM (18.04%) and Sunway (8.86%). The provident fund is the largest shareholder of IJM. Should the takeover exercise materialise, its shareholding will be 7.3%, remaining the third-largest shareholder of the enlarged Sunway.
The other substantial shareholders of IJM are Amanah Saham Nasional Bhd at 14.54% and Retirement Fund Inc (KWAP) at 9.64%. Collectively, the three institutional funds hold 40.97% — about 9% shy of the 50% plus one share acceptance stipulated in Sunway’s takeover offer.
Sunway will take IJM private if it garners 75% shareholding, and invoke its right to compulsory acquisition once it crosses the 90% mark.
Sunway’s rationale is simple — the need for a strong property and construction player in Malaysia in anticipation of more investments coming into the country. The group intends to fill that space.
If the deal succeeds, there will be one less capable infrastructure builder in Malaysia but there will be an even bigger construction and property development conglomerate.
Is bigger better in the corporate world? Only time can tell (see story on page 53).
A good bargain or decent offer?
It is nothing short of a masterstroke for Sunway to propose a share-swap deal when its shares are almost fully valued at RM5.65 apiece, based on analysts’ target prices. Notably, Sunway’s share price has doubled over the past two years as it looks to list its medical arm, Sunway Healthcare Holdings Bhd, to unlock asset value. But IJM’s shares are not trading at such a hefty valuation, hence making the deal a bargain.
Sunway’s takeover offer of RM3.15 per share, 10% of which will be in cash and the remainder in new Sunway shares, at a ratio of one Sunway share for every two IJM shares held. The consideration shares will be issued at RM5.65 apiece.

For illustrative purposes, an IJM shareholder with 1,000 shares would receive about RM2,835 worth of ordinary shares, or 501 units, in Sunway and RM315 in cash.
Kenanga Research has advised IJM’s shareholders to reject the offer, noting that the offer price is not attractive. According to the research house, the implied valuation of the offer is only RM2.69, which is below both the current share price of RM2.75 and its target price of RM3.40.
“While we are unfavourably inclined towards the offer price, we acknowledge that the enlarged entity could enhance operational efficiency, potentially improving IJM’s construction margins, alongside possible synergies across the property and industrial manufacturing segments,” says Kenanga Research.
CIMB Securities says in a Jan 13 report that the offer price is a 12.5% discount to its target price of RM3.60 for IJM, but it stops short of saying whether to accept or reject the deal. “Overall, the proposed CVO (conditional voluntary offer) is positive for Sunway as it provides long-term diversification benefits and integration of IJM’s infrastructure and logistics assets,” it adds.
The offer price is a 14.5% premium to IJM’s last traded price of RM2.75, a 17.6% premium to its six-month volume-weighted average market price and a 27.89% premium to its 12-month VWAMP.
The offer of RM3.15 — which is 7.51% premium to IJM’s net asset value per share of RM2.93 as at Sept 30, 2025 — seems decent. But the long-term IJM shareholders may beg to differ, noting that the potential value of the group’s many assets have yet to be reflected in its share price.
Simply put, the assets or businesses that IJM has nurtured in the past have not yet come to fruition, so investment analysts are unlikely to value them for now. Examples would be the group’s highway assets, land bank that has not been revalued for 20 years and ventures in the UK.
The West Coast Expressway, for instance, has been delayed for the longest time due to land acquisition issues. The highway is a major infrastructure project involving a 233km network connecting Banting in Selangor to Taiping, Perak. IJM holds a direct stake of 43% in the highway concessionaire and 28.2% in its holding company, WCE Holdings Bhd (KL:WCE).
Meanwhile, IJM only received the nod for the 15km extension of the New Pantai Expressway (NPE) — dubbed NPE 2 — in May 2025, after the project was cancelled in 2012. The group also owns the concessions for the Kajang-Seremban Highway (LEKAS) and Sungai Besi Expressway (Besraya).
According to IJM’s 2025 annual report, a total of 52.68ha (130.18 acres) of commercial and agricultural land in Negeri Sembilan still carry the RM641.63 million valuation the parcels had when they were acquired in 2004. Meanwhile, 174.63ha of leasehold land in Pengerang, Johor, still carry the RM310.16 million valuation the tract had when it was acquired in 2008.
IJM has indicated its plan to monetise its highway concessions, but it needs time to complete the WCE and NPE 2 to build a decent highway portfolio.
As one observer puts it succinctly, the worst-case scenario for IJM shareholders would be if the acceptance level came in at between 50% and 75% shareholding, as it would make the group a public-listed company controlled by Sunway.
“If IJM remains a public-listed company with Sunway as the controlling shareholder, will both IJM and SunCon (Sunway Construction Group Bhd, KL:SUNCON) be bidding for the same jobs? Even if they do, will clients see them as two competing bidders, or bidders from the same group?” he says.
According to CIMB Securities, the takeover offer is marginally accretive at +1.5% (18.1 sen) for the enlarged Sunway Group’s pro forma FY2024 earnings per share in the full acceptance scenario, but flat at 17.8 sen in the minimum 50%-plus-one-share scenario.

Why does Sunway want IJM?
Both Sunway and IJM are prominent players in the property development and construction industries. In fact, they often bid for the same local infrastructure jobs, including the mass rapid transit and light rail transit (LRT) projects in the Klang Valley, as well as the LRT in Penang.
At the press conference announcing its proposal, Sunway president Datuk Anuar Taib said the change in global economic dynamics will result in a lot of investments coming to Malaysia, which raises the need for a strong property development and construction player.
“I guess that as you get larger and stronger, you will be faced with different challenges. Scale usually helps, especially on availability of financing, on availability of capabilities that we can bring forward,” he said.
“But this is not just about one plus one equals two. This is not just about the P&L (income statement) or the balance sheet. This is also about the pool of talent,” he continued.
“When we see IJM has good talent, and we also have good talent, with the two of us combined, we can deploy really good talent to places that we know the combined entity would actually have markedly differentiating capabilities to win a lot more things.”
It is hard to imagine that Sunway needs talents from IJM and vice versa, as these two groups have been bidding for the same jobs and winning contracts in the same sector.
A construction sector analyst whom The Edge spoke to says there is no major need for the acquisition in the context of the construction business. “Both build DCs (data centres), both build railways, both build properties. The only advantage that IJM has over SunCon (Sunway’s construction arm) is its exposure to the industrial property space. But that doesn’t mean IJM must be acquired by Sunway to get that exposure,” he adds.
The analyst says the synergies or pull factor for Sunway to acquire IJM are the non-construction assets and businesses — IJM’s land bank, port and highways.
In terms of property development, Sunway’s potential gross development value (GDV) is higher than that of IJM despite the latter owning a larger land bank. IJM owns 3,316 acres, while Sunway has 2,369 acres, mostly in Johor, the Klang Valley and Perak.
Sunway highlighted that its property developments are valued higher due to the presence of medical centres, universities and colleges, as well as retail assets. In essence, the group builds new cities, while IJM builds new townships.
“The GDV per acre of IJM’s land is lower at RM13 million per acre compared with Sunway’s RM30 million per acre. So that could be an opportunity for Sunway to make things better,” says the analyst.

This was echoed by CGS International Securities in a Jan 12 note on the proposed acquisition. It says the upside for Sunway would be IJM’s residential townships and industrial land bank, its Innova Partnership with Network Rail and JRL Group for construction in the UK, its manufacturer of pretension high strength piles, toll business and Kuantan Port.
The research house recommends that IJM shareholders accept the offer as it presents an opportunity to migrate to a larger entity with exposure to other businesses, such as Sunway Healthcare, and an established track record in adding shareholder value.
Nevertheless, some anticipate the upward trajectory of Sunway’s share price may reverse after the initial public offering of Sunway Healthcare.
What are EPF and PNB’s considerations?
EPF will be the third-largest shareholder in an enlarged Sunway-IJM. Some quarters see acceptance of the offer as the provident fund trading majority control of a construction and property development conglomerate with a minority stake in a much larger group.
EPF will have to decide whether it wants to have controlling say in IJM or a minor but still substantial vote in an enlarged Sunway-IJM that could probably offer more dividends and higher valuations. Still, EPF should not sell its stake cheap.
Interestingly, EPF is already the largest shareholder of Gamuda Bhd (KL:GAMUDA), with 18.67% equity interest. The provident fund also has a 36.21% stake in Malaysian Resources Corp Bhd (KL:MRCB), another construction and property development group.
Losing its status as the largest shareholder of IJM is unlikely to be the key concern for EPF, whose mandate is to generate investment returns for its members.
Meanwhile, Permodalan Nasional Bhd (PNB) — the country’s largest asset management firm — appears to be on a divestment spree to unlock investment value.
It is known that PNB is exploring its options in terms of selling its 51% stake in Prolintas Infra Business Trust (KL:PLINTAS), which it listed almost two years ago. It is also looking for buyers for its Projek Lintasan Kota Holdings Sdn Bhd (Prolintas), which operates the Damansara-Shah Alam Elevated Expressway and the Sungai Besi-Ulu Kelang Elevated Expressway.
IJM is among the bidders for PNB’s highway assets.
Would there be reasons for EPF and PNB to hold on to their IJM shares, apart from receiving an offer that might not reflect the group’s intrinsic value?
IJM’s share price closed at RM2.80 last Friday, a gap of 35 sen or 11% against the offer price of RM3.15. Some see this as a reflection of the uncertainties that could be in the way for Sunway to buy out IJM.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.