

This article first appeared in The Edge Malaysia Weekly on December 8, 2025 - December 14, 2025
LAC Med Bhd (KL:LACMED), en route to list on the Main Market of Bursa Malaysia on Dec 10, is positioning itself not as another medical equipment distributor but as a specialist in high-value, highly specialised machines — a space dominated globally by only a handful of manufacturers.
The group currently distributes 49 main products for 11 principals, with its core strength being in angiography, magnetic resonance imaging (MRI) and computed tomography (CT) systems.
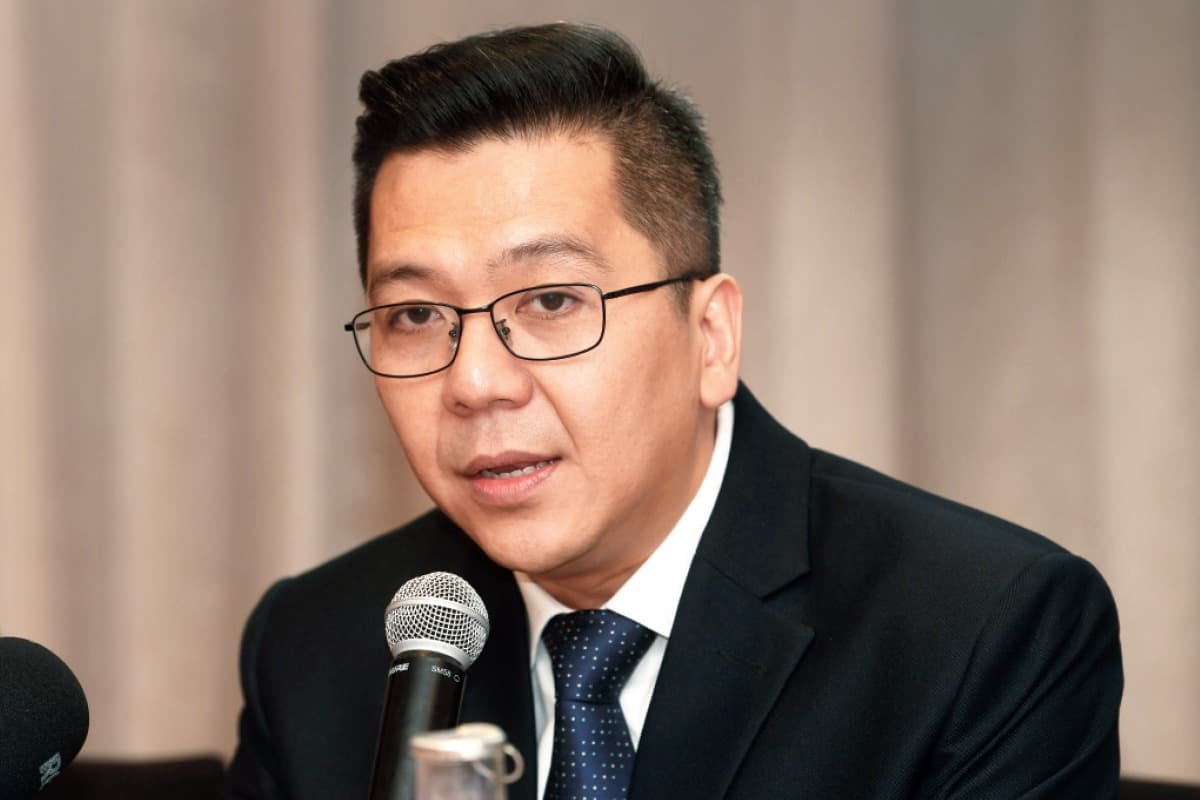
CEO Liew Yoon Poh says staying focused on solution-based selling and support, rather than pure distribution, has shaped the company’s value proposition.
“We are in a niche segment. Our strength is large-scale machines — an entirely different playing field with only a few global brands. Our model is distinct from many of our peers’,” he tells The Edge in an interview at the company’s headquarters in Kelana Jaya, Selangor.
LAC Med’s next chapter, however, is to broaden earnings beyond one-off equipment sales.
This year, the home-grown company rolled out an Equipment-as-a-Service (EaaS) model — bundled with maintenance, upgrades and uptime guarantees — where revenue is tied to equipment performance rather than ownership.

First billings began in September, and EaaS contribution remains below 5%, but early adoption by both public and private hospitals shows traction.
“There’s been industry talk about leasing, but what we do is very different. Leasing is purely a financing mechanism — essentially a rental agreement. Under our model, we go on a risk-sharing, outcome-based partnership. If the equipment goes down, the hospital loses revenue — and we will not be paid for the down time,” Liew explains.
So far, the take-up has been encouraging as this business model makes the most sense for large, high capital expenditure (capex) equipment.
“It is less suitable for small, inexpensive items because the conversion effort doesn’t justify the economics. But as hospitals look to conserve capex and pivot to operating expenditure, we believe adoption will continue to grow,” says Liew.
According to him, over the next two to three years, EaaS is anticipated to increase LAC Med’s market share without cannibalising its existing businesses.
Indonesian expansion
The group is also making its first overseas foray into Indonesia, where regulatory approvals were secured only this year.
Liew sees the market as a long-term build rather than a fast grab — large, fragmented, but rich with potential as healthcare infrastructure modernises and digitalisation eases specialist shortages across the archipelago.
“We established the Indonesian entity in December last year, but regulatory approvals took time. We only entered the market in the third quarter of this year. We expect Indonesia to represent a modest contribution to the group in the initial phase,” he says.
Liew highlights that Indonesia is roughly eight times larger than Malaysia in market size, and the population alone is 10 times bigger.
“The growth rate is extremely exciting but because of the size and fragmentation, it is a long-term play — not something we intend to rush into aggressively.”
Despite the presence of existing local distributors, the market remains highly fragmented. What gives LAC Med the edge is the company’s track record in Malaysia, as well as its skilled resources.
“Many principals have asked whether we plan to expand regionally. They’ve seen what we can deliver here and believe we can replicate that performance in Indonesia,” says Liew.
LAC Med’s operations have begun in Jakarta, and there are plans to open branches in Sumatra, Surabaya and Kalimantan in 2026 and 2027.
“Our Indonesian team comprises reliable, experienced local providers integrated from a former medical device distributor. We have already secured an exclusive distributor agreement with South Korea’s Alpinion Medical Systems.
“We aim to leverage our existing brand partnerships in Malaysia and extend them to Indonesia at the appropriate time, allowing us to provide wider product offerings,” says Liew.
The group has a workforce of over 90 in Malaysia and an initial team of over 20 in Indonesia. The more immediate growth, he admits, lies closer to home.
For perspective, LAC Med currently supports the Malaysian healthcare sector with over 2,500 units of medical equipment installed for more than 300 active clients. The company’s growth could come from three areas — new hospitals, existing hospital expansions and the replacement of ageing assets.
“Demand is amplified by major projects, such as Sunway Healthcare Group, Sena Healthcare, KL Wellness and many more. The industry expects 3,000 new beds in the next three years alone, creating vast demand for medical equipment to provide sufficient patient care,” Liew remarks.

Founded in 2003, LAC Med started out by distributing basic medical goods and imaging equipment. The first decade was its proof-of-concept phase, where the company built the trust to handle life-saving technologies.
LAC Med’s growth accelerated after securing distributorships from Samsung Electronics Co Ltd and Samsung Medison Co Ltd in 2013, and later Koninklijke Philips NV in 2017 — placing the group among the country’s biggest distributors of radiographic and ultrasound systems.
“Today, with a portfolio of 11 brands, our mission is bigger. We are addressing complex operational challenges, such as physician burnout and patient care, with a wide array of devices and solutions.
“We have moved from a hardware vendor to a long-term partner who handles everything, from facility design to ensuring optimal asset performance over a 10-year horizon,” says Liew.
Moreover, having added nine new principals, including Stryker, LG, Abbott and Bayer in recent years, LAC Med could also cross-sell to its existing clients — a faster pathway to lift revenue.
“We can now supply critical departments like operating theatres and laboratories, moving far beyond imaging devices. We are now a comprehensive partner, providing a wide array of solutions essential to healthcare operations,” he says.
LAC Med has a market coverage of 58% in Malaysia, serving 217 hospitals out of a total of 373. The group also services over 800 clinics nationwide.
Liew reveals that the company’s client base includes major public sector facilities and major private groups such as IHH Healthcare Bhd (KL:IHH), Sunway Healthcare Group and Columbia Asia.
“Our growth strategy in Malaysia is less about finding new hospitals. Greenfield hospitals together with hospitals undergoing expansion plans only form 25% of our group’s revenue contribution. The balance of revenue is generated from the asset replacement cycle of respective healthcare providers,” he points out.
High-growth stock?
At the initial public offering (IPO) price of 75 sen apiece, LAC Med is expected to raise RM78.15 million from its listing exercise.
About RM55.65 million will be fresh capital for the company while the remaining RM22.5 million will go to the existing shareholders, including Liew, his brother and non-executive chairman Liew Yoon Kit, as well as substantial shareholder Giam Teck Eng.
The proceeds will be used to fund the company’s EaaS and medical equipment asset management services (MEAMS) business segments, to support its regional expansion in Indonesia, as well as to build a new head office with expanded storage and a dedicated showroom.
MEAMS is a software solution for optimising asset utilisation and reducing downtime using tracking technologies such as radio-frequency identification (RFID) and barcodes, whereas EaaS focuses on asset ownership and performance guarantee.
Post-listing, the combined stake of the Liew brothers and Giam will drop from 75% to 53.7%. Giam’s uncle, Chan Yue Mun, will see his stake diluted from 25% to 18.6% despite not selling any shares.
Upon listing, LAC Med will have a market capitalisation of RM300 million. The IPO values the company at a price-to-earnings multiple of 14.7 based on the financial year ended Dec 31, 2024 (FY2024) net profit of RM20.4 million. The company has adopted a 30% dividend policy.
RHB Investment Bank is the lead adviser, joint underwriter and placement agent, with Alliance Bank as joint underwriter.
Liew believes LAC Med is “a high-growth company that prioritises shareholder returns”, as the group is deepening its market leadership in Malaysia by aggressively introducing its expanded portfolio of global brands.
LAC Med has no direct peer comparisons on Bursa currently as the others are focusing on manufacturing.
“We are exclusively focusing on our core business as a medical device and integrated solutions provider. We have no plans to move into manufacturing.
“Our exclusive focus aligns us with our global partners. By partnering with globally recognised device brands, we can strengthen our market credibility, accelerate access to advanced technologies and expand distribution capabilities,” he adds.
Liew says LAC Med competes directly with global giants like Siemens Healthineers and GE Healthcare Technologies Inc, but the firm differentiates itself through its speed, specialised engineers and clinical application teams, as well as local execution capability.
“At a PER (price-earnings ratio) of 14 to 15 times, we offer investors a unique entry point into a market leader. We have a dividend payout policy to distribute at least 30% of our annual net profit, but we position ourselves primarily as a growth stock.”
For comparison, Main Market-listed UMediC Group Bhd (KL:UMC) — a Penang-based medical device distributor and manufacturer controlled by UWC Bhd (KL:UWC) co-founders Datuk Ng Chai Eng and Datuk Lau Chee Kheong — is trading at a historical PER of 15 times, with a market capitalisation of about RM125 million.
ACE Market-listed BCM Alliance Bhd (KL:BCMALL), via its unit Best Contact (M) Sdn Bhd, also distributes medical devices for Hitachi, Carestream and Ziehm. However, it remains loss-making and trades as a penny stock, and has a market cap of only about RM20 million.
In a Nov 24 report, Tradeview Research gives LAC Med a target price of 94 sen, representing an upside potential of 25%.
“Our target price is based on FY2026 PER of 13.9 times, in line with UMediC’s forward PER. This implies a 21% discount to the simple average forward PER of its domestic medical equipment distributor peers of 17.6 times and a 27.2% discount to its foreign medical equipment distributor peers of 19.1 times.”
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.