

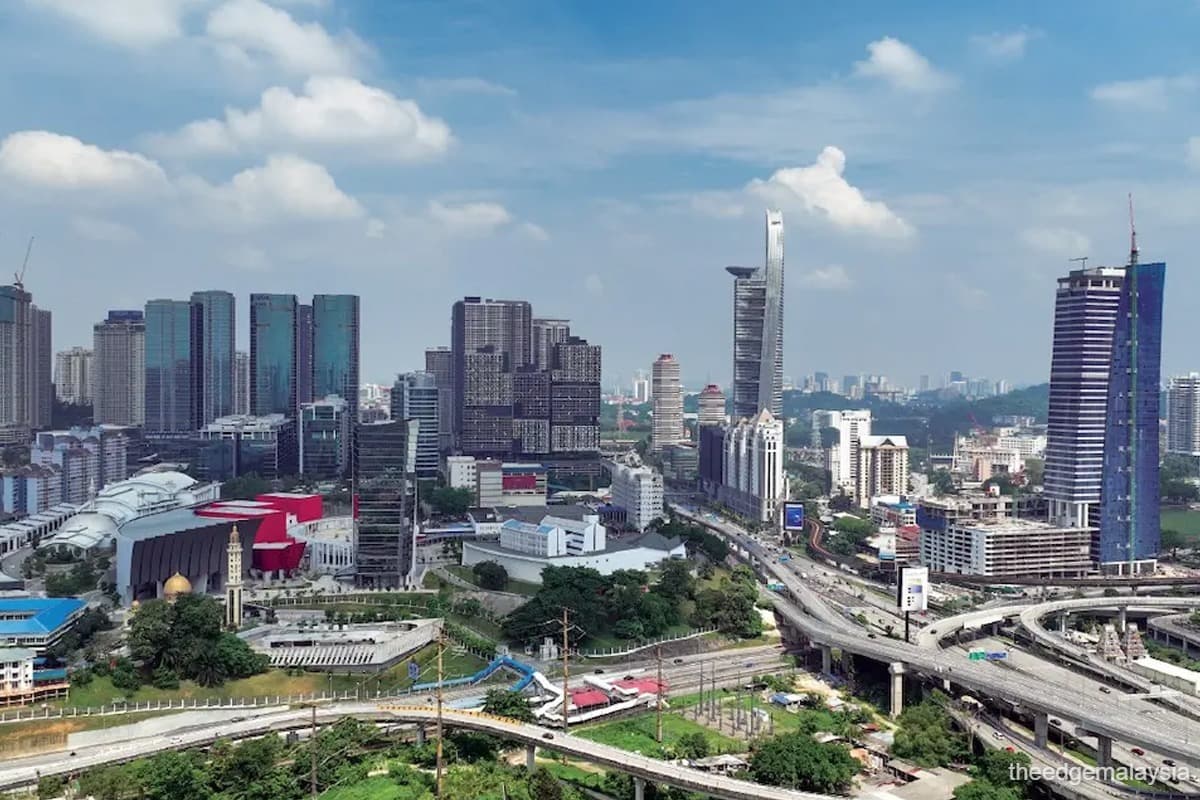
This article first appeared in City & Country, The Edge Malaysia Weekly on December 1, 2025 - December 7, 2025
The Klang Valley office market remained stable in 3Q2025, with a marginal increase in rental rates and improvement in net absorption rates, according to Knight Frank Malaysia executive director of research and consultancy Amy Wong in presenting The Edge Malaysia | Knight Frank Kuala Lumpur and Selangor Office Monitor 3Q2025.
“Klang Valley recorded an improvement in net absorption to about 677,000 sq ft during the quarter. On a year-to-date basis, net absorption has already exceeded the full-year 2024 total, reflecting sustained yet selective leasing activity,” she says.
Breaking down the numbers, Wong explains that the net absorption rate for Kuala Lumpur improved to 609,000 sq ft during the period in review, while for Selangor, net absorption totalled 68,000 sq ft.
Wong says this shows that the market is steadily recovering and has continued occupier interest in well-connected business locations.

As for occupancy rates, Knight Frank Malaysia executive director of office strategy and solutions Teh Young Khean says they are holding steady across most submarkets. “Leasing demand continued to centre on well-located Grade A buildings, supporting consistent rental levels. Nonetheless, the recent implementation of the sales and service tax has prompted occupiers to reassess cost structures and space strategies, leading to slightly longer decision-making cycles.”
Average office occupancy in Kuala Lumpur showed mixed movements in 3Q2025, with the new central business district (CBD) recording the strongest performance. Occupancy in the CBD rose to 76.8% from 75.3% in the previous quarter, marking a 1.5-percentage-point (ppt) increase.
In contrast, occupancy in the old CBD declined notably to 54.4% from 58.4% in 2Q2025, which translates into a decrease of 4ppt. The KL City Centre peripheral area remained largely unchanged, with occupancy easing marginally to 51.3% from 51.4% in the previous quarter. Overall, KL City’s average occupancy improved to 70.1% in 3Q2025, a slight uptick from 69.6% in the preceding quarter.

Average occupancy across the KL Fringe submarkets presented mixed results in 3Q2025, with several localities recording steady improvements while one area saw a sharp decline due to newly completed supply.
Damansara Heights saw an increase to 83% from 81.9% in the previous quarter. KL Sentral remained stable, edging up to 96% from 95.7%. The Taman Tun Dr Ismail, Mont’Kiara and Dutamas cluster also saw higher occupancy of 78.2% from 77%, while Mid Valley City and KL Eco City advanced to 88% compared with 86.5% in 2Q2025.
Bangsar South and Kerinchi remained stable at 98.1%, unchanged from the previous quarter. The only significant decline was recorded in the Pantai and Bangsar area where occupancy fell sharply to 72.5% from 86.2%, largely due to the recent completion of Menara TNB Bangsar, which added substantial new space. Overall, the KL Fringe achieved an average occupancy rate of 88.3% in 3Q2025, down from 89.7% in the previous quarter.
Meanwhile, in Selangor, office occupancy trends were mixed as well, with Petaling Jaya providing the only improvement while other key markets softened due to new supply and marginal demand shifts.

Petaling Jaya’s occupancy rate rose slightly to 75.9% from 75.4% in the previous quarter. Subang Jaya, however, registered a steep drop to 61.2% from 68.7% — a decline linked to the recent completion of Sunway Square Corporate Tower 1, which expanded available space.
Shah Alam also saw a mild contraction, with occupancy easing to 86.9% from 87.7%, while Cyberjaya remained relatively stable, slipping marginally to 69.5% from 69.6% in 2Q2025. Overall, Selangor’s average office occupancy decreased to 72.5% in 3Q2025 from 73.8% in the previous quarter.
Teh says, “Despite a marginal dip in overall occupancy, rental levels continued to edge higher. Demand in the office market remains largely driven by multinational corporations pursuing flight-to-quality and expansion strategies. Grade A buildings in integrated developments and with good accessibility to public transport remain a priority for occupiers.”

New supply slightly affects occupancy
Wong says the Klang Valley’s purpose-built office market continues to expand steadily, with total supply now estimated at 120.62 million sq ft. KL City remains the largest contributor, accounting for 60.63 million sq ft, followed by the KL Fringe, with 32.18 million sq ft, and Selangor, with 27.81 million sq ft.
An additional 3.12 million sq ft of space is under construction and scheduled for completion between 4Q2025 and 2026. KL City is expected to add 390,000 sq ft during this period, while the KL Fringe will see the largest incoming supply at 1.53 million sq ft. Selangor will contribute another 1.2 million sq ft of new office space.
Some new completions this quarter include Menara TNB Bangsar, offering an estimated net lettable area of about 475,000 sq ft. In Selangor, Sunway Square Corporate Tower 1 in Sunway City Kuala Lumpur will contribute about 433,000 sq ft of space, while Sunsuria Forum in Shah Alam is expected to add around 379,000 sq ft.
Teh says as at 3Q2025, total new completions for the year reached about 2.4 million sq ft, with no further additions expected in the final quarter.
“The market is gradually absorbing the new supply, including recent major completions, while another 3.1 million sq ft is scheduled for 2026. Against this backdrop, differentiation and tenant-centric upgrades will remain crucial for older buildings to stay competitive in an increasingly quality-driven environment,” he stresses.
Concurring with Teh, Wong notes that the influx of new space weighed slightly on overall occupancy levels in both the KL Fringe and Selangor, while KL City continued to see slight occupancy gains as tenants relocated to newer, high-spec offices in prime locations.

As such, several notable tenant movements were recorded across KL City, KL Fringe and Selangor in 3Q2025.
In KL City, Integra Tower saw one of the largest transactions, with about 95,000 sq ft taken up by a banking and finance occupier undergoing consolidation and relocation. Equatorial Plaza secured about 63,000 sq ft from a business process outsourcing tenant relocating to the building.
Plaza Conlay recorded around 38,000 sq ft of new occupancy from an energy and oil and gas-related company, while Menara Prudential added roughly 31,000 sq ft from an online travel services firm expanding its presence.
Leasing activity in the KL Fringe was similarly active. Menara LGB registered about 48,000 sq ft of new space taken up by occupiers involved in professional services, consulting, as well as healthcare and life sciences as part of expansion and relocation plans. Mercu Aspire saw around 40,000 sq ft committed by a co-working and flexi space operator, alongside a chemical and industrial tenant establishing or expanding operations.
Menara Ken TTDI added about 10,000 sq ft from a fast-moving consumer goods company expanding in the market. However, Tower 3 Avenue 7 at The Horizon recorded a move-out of roughly 18,000 sq ft by a banking and finance tenant.
In Selangor, Menara CelcomDigi recorded a relocation-driven move-in of about 51,000 sq ft from a banking and finance company. Sunway Square Corporate Tower 2 (completed in 2Q2025) saw about 15,000 sq ft absorbed by a manufacturing-related occupier relocating to the building. Meanwhile, The Ascent registered a move-out of around 12,000 sq ft by a tenant from the manufacturing sector.

Rental rates improving
In terms of rental rates, Wong says rents rose marginally across most submarkets, particularly in the KL Fringe and Selangor.
“This was driven by the entry of newer, higher-quality buildings. Flight-to-quality and cost rationalisation trends continued to shape leasing preferences, benefiting newer or recently upgraded buildings,” she says.
Average office rents in KL City remained largely stable in 3Q2025, with only marginal adjustments across submarkets. Rents in the new CBD recorded a slight uptick of 0.3% to RM7.35 psf from RM7.33 in the previous quarter. Rents in the old CBD held steady at RM4.45 psf, unchanged from 2Q2025, while the KL City Centre peripheral area also maintained its rate at RM5.70 psf.
Overall, the KL City average inched up to RM6.72 psf from RM6.70 previously, marking a 0.3% quarter-on-quarter improvement.
Office rental rates across the KL Fringe showed minor adjustments in 3Q2025, with most submarkets holding steady. Damansara Heights and KL Sentral maintained their rates at RM4.62 and RM6.41 psf respectively, while Taman Tun Dr Ismail, Mont’Kiara and Dutamas also stayed unchanged at RM5.28 psf. Mid Valley City and KL Eco City saw a slight increase of 0.3% to RM6.49 psf from RM6.47 previously.
Bangsar South and Kerinchi remained stable at RM5.70 psf, whereas Pantai and Bangsar recorded the largest gain, rising 5.1% to RM5.33 psf, driven by the recent completion of Menara TNB Bangsar. Overall, the KL Fringe average rent edged up to RM5.83 psf from RM5.81 in 2Q2025.
Office rental rates in Selangor showed modest changes in 3Q2025, with most submarkets holding steady. Petaling Jaya maintained its rate at RM4.57psf, while Shah Alam and Cyberjaya remained unchanged at RM3.46psf and RM3.72psf respectively.
Subang Jaya recorded the largest increase of 2.7% to RM4.62psf from RM4.50, driven by the recent completion of Sunway Square Corporate Tower 1. Overall, Selangor’s average office rent edged up to RM4.29psf, a 0.7% increase from the previous quarter.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.