

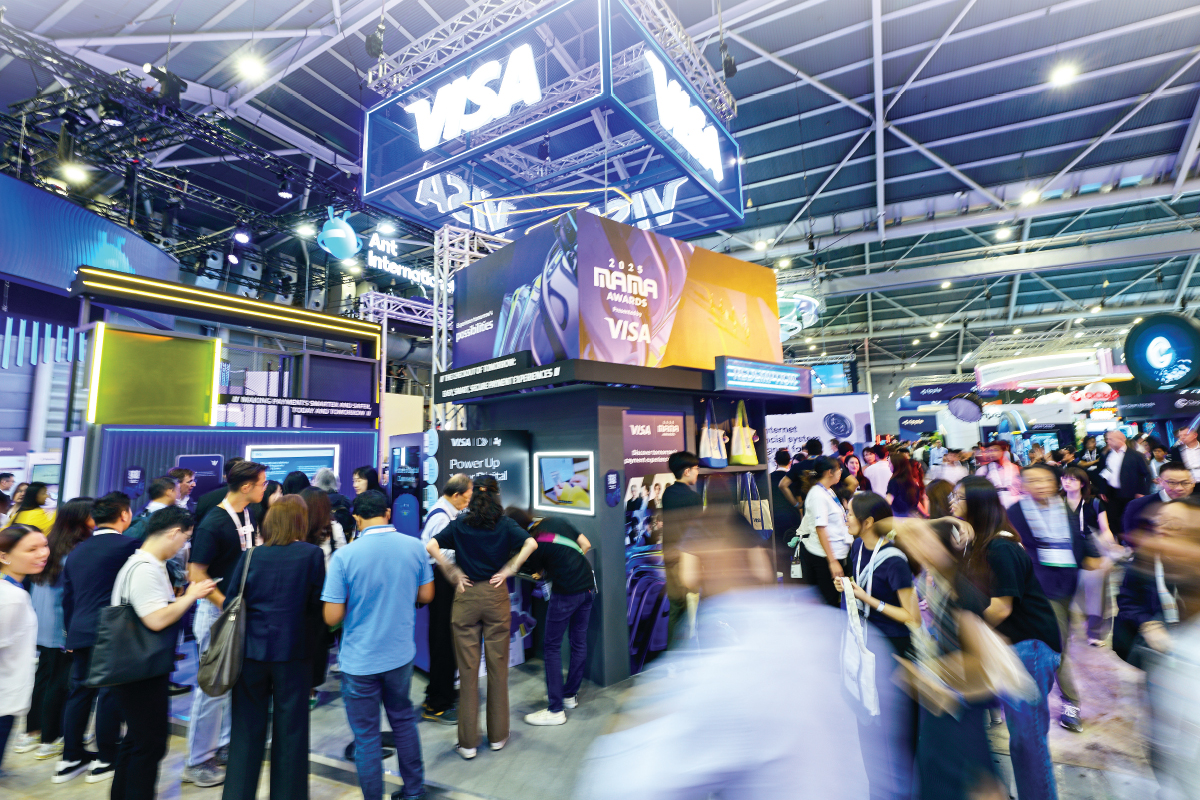
This article first appeared in Wealth, The Edge Malaysia Weekly on November 24, 2025 - November 30, 2025
Visa Inc, one of the world’s largest payment network companies, announced its plans for stablecoins and agentic artificial intelligence (AI) at the recently held Singapore Fintech Festival. It was a clear sign that the industry was entering a new phase where payments could be automatically completed using AI and transacted in not just fiat currencies, but also asset-backed cryptocurrencies issued by private entities.
During the media briefing, T R Ramachandran, Visa’s head of products and solutions in Asia-Pacific, announced the company’s plans to expand Visa Intelligent Commerce across the region to accelerate its push into agentic commerce where AI-powered agents shop and pay on behalf of consumers.
How does it work? Simply put, consumers can use an AI chatbot (such as ChatGPT) to search for products, receive personalised recommendations and automatically complete payments using an AI agent with just a click of a button for approval. Five key processes are involved in the solution.
First, consumers are prompted to upload their card credentials online securely, such as by tapping on a smartphone, through a process called tokenisation. Then, they go through an authentication process, such as a face or fingerprint scan, to prove they are the rightful owner of the card.
The third step is personalisation, where consumers can opt in to share their past transactions with the AI agent for better recommendations. When all this is done, they only need to instruct the AI agent to complete the payment, which is performed automatically with just a click of a button.
The fifth step, known as payment signals, is less obvious to consumers. These signals, including contextual and behavioural data such as device information, geolocation and transaction patterns, help the AI and payment network validate transactions, detect fraud and optimise routing.
“So, it not only says that I’ve made a transaction at, say, Uniqlo. It also says that I’ve made a transaction at 11.30am for a pair of size eight white hiking socks, for instance. The extra data is important to handle chargebacks and disputes within the ecosystem,” said Ramachandran.
Questions asked during the event included if there is indeed a ready market for agentic commerce, as shoppers may prefer to go through the process on their own — as a form of “retail therapy” — instead of outsourcing it to AI. Stephen Karpin, Visa’s regional president for Asia-Pacific, said the demand for such services was indeed huge.
“Based on the research we’ve done in the US and Australia, those who are using large language model-based chatbots, the majority of them are interested in empowering an AI agent to finish that loop that we explained, including to make payments for them as long as it is secure and the trust is there. We have huge conviction that it is one of the biggest shifts that we’re ever going to see in e-commerce,” he added.
Ramachandran said there are different types of things people buy online. There are those that you prefer to conduct your own research, such as buying a smartphone, and those that you would outsource to an AI agent, like booking the hotel of your preference when travelling in a country, with a set of parameters.
“There are categories [of online shopping] which lend themselves more intuitively to a sort of agentic experience. Think of the agent as your trusted concierge. Anything you want to delegate to a concierge will automatically lend itself to that behaviour. Travel could be one of them,” he added.
According to its press release, Visa is actively collaborating with some of the biggest players in AI, tech and payments, including Ant International, LG Uplus, Perplexity, Stripe and Tencent, to enable agentic commerce transactions.
Looking ahead, the company plans to launch Visa Intelligent Commerce pilots across Asia-Pacific as early as 2026 with regulatory and ecosystem advancements.

Tokenisation reshaping lending and FX markets
It was only five months ago that Visa’s share price fell by more than 5% after The Wall Street Journal reported that major retailers were exploring stablecoin options to bypass traditional card payment fees.
Fast forward to November, Nium, a global infrastructure provider for real-time cross-border payments, announced its participation in Visa’s stablecoin settlement pilot, an initiative that enables selected partners to settle with the payment network company using stablecoins across supported blockchains.
According to the press release, Nium will harness supported stablecoins, including Circle’s USDC, as a digital settlement rail via Visa. The firm aims to reduce friction, cost and delays in cross-border settlement, including addressing pain points such as weekend cut-offs, time zone delays and slow reconciliation windows.
Cuy Sheffield, Visa’s vice-president and head of crypto, said the stablecoin market has grown to over US$260 billion in circulation in the past five years, with every major payment company investing in integrating stablecoins into their products.
The US government, particularly, has gone from having a hostile regulatory environment to actively supporting it this year under the Trump administration.
“We are optimistic that the regulatory environment is going to continue to develop and improve in many markets across the world, as the US makes a major bet to improve the financial plumbing behind how the [US] dollars move [around the globe]. It’s really important for other governments and regulators to figure out how to make their financial systems compatible with some of its modern infrastructure,” said Sheffield.
He said the popularity of stablecoins is due to the strong demand for the US dollar. It is essentially an easier way for consumers and small businesses, especially in emerging markets, to access the greenback. Many don’t pay much attention to the underlying blockchain technology.
Sheffield estimated that there are 100 million to 200 million people holding stablecoin balances today, using them as a proxy to the US dollar.

As the number of stablecoin holders grows, use cases have sprung up, including business-to-consumer and business-to-business payments. In fact, some of the largest companies in the world accept local payments and use stablecoins to send them back to the US, he said.
“Overall, across these categories, we estimate about US$50 billion to US$100 billion of volume [transacted] annually, and it is growing very quickly. So, we are really excited for Visa to be part of many of these cross-border payment plans,” he added.
Sheffield said an area in the cryptocurrency universe that some may have overlooked is on-chain lending, which means borrowing and lending activities that happen on the blockchain.
“I asked my team how many loans have been disbursed in stablecoins on-chain through smart contracts? I thought it was a simple question. It turned out that we took about 1½ months to figure that out as there are so many stablecoins that run on many different blockchains. You have many lending protocols on each of those blockchains. It’s a hard data problem to solve, but we figured it out,” he said.
“Over US$70 billion in loans have been disbursed in an automated way on-chain and [through] stablecoins. Many of these loans are moving across the world. You can have a lender in Brazil that is depositing stablecoins for borrowers in the Philippines.
“We’ve talked a lot about cross-border payments, but we haven’t talked about cross-border lending. And we think there are major innovations that are happening [in this area] that are going to apply to the broader financial ecosystem.”
For now, those lending activities happening on-chain are fully collateralised by crypto assets. But Sheffield foresees a world with more asset classes being tokenised and used as collateral for loans, including tokenised US Treasuries, receivables or gold, all of which can be used as collateral for loans in smart contracts.
What this means for Visa is that these borrowings have to be spent, which leads to more payments taking place in the form of digital currency, not just domestically but abroad. Meanwhile, more currencies other than the US dollar will have its version of stablecoin moving forward.
“You now have this global foreign exchange (FX) market with stablecoin-to-stablecoin conversions. We look at stablecoin as a technology. We think every major currency will be represented on-chain at some point. So, if you have a digital dollar, a digital euro, a digital peso, you can now have a fully on-chain FX market that allows you to trade 24/7, and we are just starting to see that emerge,” said Sheffield, adding that this is a market Visa wants to tap into.

The ‘network of networks’ strategy
As one of the largest payment network companies in the world, Visa had a payments volume of US$13.2 trillion in its 2024 fiscal year. It processed US$233.8 billion worth of transactions, involving 160 currencies, and generated revenue of US$35.9 billion. Net income came in at US$19.7 billion, up 14% from the previous year, according to its official website.
One of the strategies of the payment network giant is being the “network of networks”, said Karpin.
“There are new [payment] networks forming around stablecoins and CBDCs (central bank digital currencies) and so forth. But interoperability is key, which the Visa network can provide. We are a network of networks. And it’s not just about moving money. It’s [being involved in] all those different cases where you need to make sure [payments between the same or different networks] are done securely, that they are following regulations and so forth,” he pointed out.
“I think what you’ll see is that we are committed to the community that we connect with all the different networks that fit the criteria of trust,” he added.
Axel Boye-Moller, head of Visa’s value-added services (VAS) in Asia-Pacific, explained how the company is evolving beyond the card payment network and how it is growing.
He said the VAS include the provision of loyalty solutions for card-issuing banks and consumers as well as payment gateway services for merchants. It also provides risk solutions, a suite of products that utilise AI and data analytics to help banks and merchants manage fraud across the payment life cycle.
The VAS, while relatively unknown to the mass market, saw its revenue grow about 25% in Visa’s last financial quarter, with total revenue approaching 30% of the company’s overall revenue, according to Boye-Moller. He said value added services, such as its risk solutions, can be used to support different payment networks and methods, in line with the company’s overall “network of networks strategy”.
Moving forward, he is excited about its Pismo solution, an all-in-one cloud native platform for banking and payments, whose solutions include core banking, corporate banking, investments and digital lending. He said its banking clients, especially the large banks, are relying on legacy technology to run their businesses, which leads to challenges in product innovation, cost management and resilience.
For instance, a company with a traditional banking system intent on launching a new credit card product or enhancing existing products may require extensive changes across its traditional core systems. But with Pismo’s modular, cloud native architecture, banks can make targeted updates without disrupting the entire system, accelerating innovation and reducing complexity.
“Legacy systems are highly interconnected, even small changes require full testing. With a cloud native platform, updates can be isolated and implemented faster,” said Boye-Moller.
“VisaNet is the network that connects banking institutions, acquirers and merchants around the world. But each of these institutions, they also need technology platforms to run their own business [efficiently]. This is what Visa can provide through Pismo,” he added.
According to its official website, Visa completed its acquisition of Pismo in January 2024 to provide clients with core banking and card-issuer processing capabilities across all product types via cloud native application programming interfaces (APIs).
Boye-Moller said he believed that Pismo was something interesting to the Malaysian market. “I feel that there’s a lot of potential for Pismo in Malaysia due to some of the challenges I mentioned earlier that financial institutions are facing. We want to continue to expand our risk solutions [services] as well as move into [the area of] account-to-account risk solutions. We want to help our clients not just with card transactions. You’ll hear more from us on this front,” he added.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.