

This article first appeared in The Edge Malaysia Weekly on November 17, 2025 - November 23, 2025
MOST working Malaysians continue to depend almost entirely on their Employees Provident Fund (EPF) savings for their retirement — and for many, even that is not enough.
EPF data from 2023 showed that more than half of its members aged 55 had less than RM10,000 in their accounts, raising serious concerns about financial preparedness in old age. As at late 2024 and early 2025, only about 37% of active formal members met the basic savings threshold, rising from 30% in 2022.
This is despite total monthly contributions of around 23% to 24% of employees’ income — 11% from workers and 12% to 13% from employers. The numbers suggest that the problem lies not in the contribution rate but in the underlying issue of low wages.
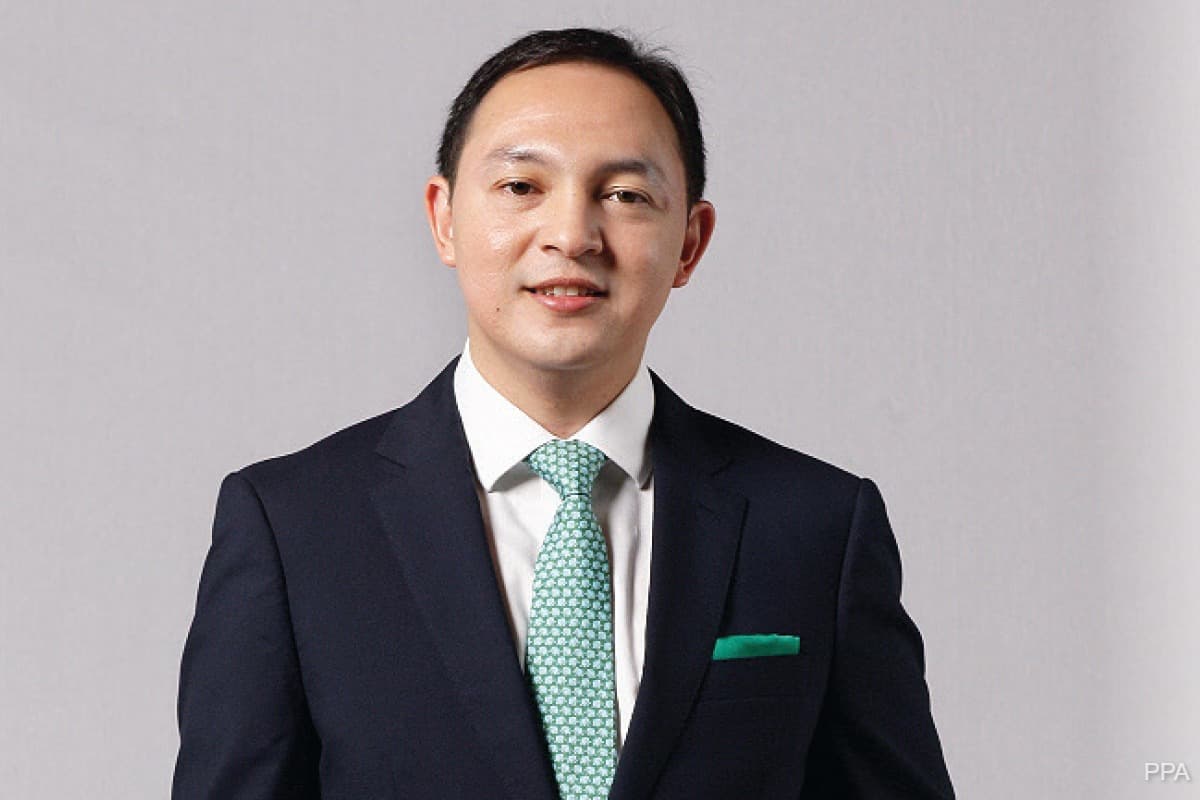
“We’ve been using a low-wage economic model for the past 30 to 40 years to drive growth,” newly minted Private Pension Administrator Malaysia (PPA) CEO Taufiq Iskandar tells The Edge.
The PPA is the central administrator of the Private Retirement Scheme (PRS).
“Even though Malaysians are already contributing about 23% to 24% of their income every month, it’s still not enough. That tells us the issue isn’t the contribution rate, but the income base itself.”
He adds that stagnant wages and rising living costs have made it increasingly difficult for Malaysians to save beyond their mandatory EPF contributions.
“We can’t expect the government to increase contribution rates further — in fact, there are arguments they may need to be reduced, though that would be very unpopular,” he says.
He points out that Malaysia’s pension system is largely funded by individual members and their employers, embodying the principle of self-reliance.
“However, with a relatively low income base, it has become increasingly difficult for many to achieve an adequate replacement income upon retirement. While strong family values and intergenerational support have traditionally cushioned the impact of financial insecurity in old age, this social safety net cannot be taken for granted,” says Taufiq, who held senior roles at Kumpulan Wang Persaraan (Diperbadankan), Penjana Kapital and ValueCap Group prior to his appointment at PPA.
As such, Malaysians have little choice but to seek alternative or supplementary savings options to secure their financial futures. This is where the PRS comes into play — a voluntary, long-term savings vehicle established to encourage additional retirement savings beyond EPF.

Modest take-up for PRS, over a decade on
Introduced in 2012 and governed by the Capital Markets and Services Act 2007, PRS was designed to complement EPF by providing individuals with the flexibility to invest for their retirement through professionals. Managed by licensed fund managers who are regulated by the Securities Commission Malaysia (SC), PRS allows Malaysians to voluntarily set aside additional funds that grow over time through diversified investments.
However, more than a decade on, take-up has been modest. As at mid-2025, PRS’ assets under management stood at around RM8.52 billion, with just over 645,000 members — a small fraction compared with the 16.5 million EPF contributors.
Taufiq is targeting the PRS fund to grow to at least RM10 billion by the end of 2026.
Economists say the slow adoption reflects low financial literacy, limited disposable income and a general lack of awareness about the importance of long-term savings.
Socio-Economic Research Centre executive director Lee Heng Guie says it is also timely for the government to review the overall monthly EPF contribution rate, either by increasing it or by offering additional tax incentives for individual contributors.
“At the end of the day, you cannot expect the government to ensure enough retirement savings. Individuals would also need to step up and take their own initiative,” he says.
“Many Malaysians still view retirement savings as something handled entirely by EPF,” says Taufiq. “PRS remains underutilised because it is seen as optional rather than essential, but in reality, it is becoming critical for financial security.”
To encourage participation, the government has introduced tax incentives, whereby contributors can enjoy personal income tax relief of up to RM3,000 per year up until 2030 for investments via PRS. However, more needs to be done to encourage retirement savings.
For instance, Taufiq suggests strengthening the PRS Scheme through automatic enrolment, similar to the system used in the UK and New Zealand, where employees are automatically signed up and can opt out if they choose.
“The single most powerful intervention Malaysia can implement is automatic enrolment. When saving is the default option, participation rates soar. Saving for retirement should be a default, not an exception.
“Coupled with proven tangible incentives such as tax relief, there’s a high chance Malaysia’s savings behaviour will change.”
Taufiq adds that financial literacy programmes must be expanded, especially among young workers and informal-sector employees. As gig work becomes more common, millions of Malaysians remain outside formal pension coverage, leaving them vulnerable in old age.
Looking ahead, he says PPA is exploring a matching grant scheme — where, for instance, every RM100 saved by contributors is matched by RM100 from the administrator. The organisation also plans to revamp its online portal and simplify fund options to make it easier for users to choose suitable investment portfolios.
PPA also aims to enrol gig economy workers, including drivers and delivery partners from platforms like Grab and Foodpanda — many of whom lack formal retirement savings — onto the PRS.
“Ultimately, retirement planning is a personal responsibility,” says Taufiq. “The government alone cannot provide for everyone. Malaysians must start saving early to ensure a more secure and dignified retirement.”
About 73.65% of PRS members are employed, which means they have EPF savings as well. Meanwhile, 9.65% of PRS members are self-employed and 16.7% did not declare their employment status as at September 2025.
According to PPA, the largest segment of PRS members are those aged 30 to 34, suggesting that younger workers are more likely to participate. The median wage of PRS members is about RM7,900 a month, with average savings of RM12,000 to RM13,000 per member.
It should be noted that members are not allowed to withdraw their savings until they are 55, unless under specific conditions.
According to Morningstar, a Chicago-based investment research firm, five of the 79 PRS funds outperformed EPF’s (conventional account) annualised return of 5.64% over the past five years, as at the end of September this year.
PRS’ top eight funds yielded average annualised returns of between 5.07% and 9.05% (see table) for five years between October 2020 and September 2025.
However, the downsides of PRS are apparent. For one, a minimum dividend of 2.5% per annum is guaranteed to EPF members under the EPF Act 1991. PRS does not have the same statutory guarantee.
“Because of the lock-in period, most people invest in PRS mainly for the tax relief,” says FA Advisory CEO Bryan Zeng. FA Advisory is a full-fledged financial planning and advisory firm.
“There are now many other investment options available out there that charge very low fees such as robo-advisors, ETFs (exchange-traded funds) and unit trusts, and offer more flexibility.
“Meanwhile, for bumiputera investors, alternative savings avenues like Amanah Saham Bumiputera and Lembaga Tabung Haji are also more familiar, cheaper and accessible. In general, not many Malaysians are actively saving specifically for retirement,” he says.
“Then, EPF also allows additional voluntary contributions and the dividend yield is more predictable and also attractive, while PRS returns fluctuate with the market, which makes it less predictable,” says Zeng.
“Nevertheless, PRS is a good long-term product, but public understanding remains limited. Many still prefer the EPF model because of its consistency and perceived stability. With so many other investment choices in the market, PRS faces stiff competition and remains a harder sell, especially given its variable returns.”

Real problem lies in low wage and stagnant productivity
While encouraging voluntary savings is important, economists warn that the real problem lies deeper — in Malaysia’s low-wage economic structure and stagnant productivity.
For decades, Malaysia’s growth model has relied on low-cost labour, particularly in manufacturing and services, which has kept wages suppressed. According to the Department of Statistics, median monthly wages in 2024 stood at RM2,793, while the estimated “living wage” in Kuala Lumpur for a single adult is RM3,100.
That gap leaves little room for savings. Even with 23% of income going into EPF, the absolute amount is not enough to have meaningful retirement funds over time.
This is especially important as Malaysia moves towards becoming an ageing society by 2030, when 15% of its population will be aged 60 and above. The urgency for comprehensive pension reform is growing.
As a matter of fact, according to Institute for Capital Market Research Malaysia (ICMR) associate director of research and development Datin Aida Jaslina Jalaludin, in less than 20 years, Malaysia will move from an ageing society to an aged society.
“Malaysian retirement outcomes are limited because our system relies heavily on individual savings, while wages are low and national contribution is minimal,” she said during her speech at the PRS campaign launch last Monday.
She added that low median wages lead to low savings accumulation, making it insufficient for retirement protection.
Ultimately, the challenge of ensuring adequate retirement income cannot be solved through policy tweaks alone. It requires a national rethinking of wages, productivity and financial planning.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.