

This article first appeared in The Edge Malaysia Weekly on November 10, 2025 - November 16, 2025
IT has been three years since car upholstery manufacturer Pecca Group Bhd (KL:PECCA) first unveiled its ambition to move up the production value chain and become a Tier-1 automotive supplier. Negotiations are currently underway between the group and several Chinese carmakers to secure seat assembly contracts, marking a key milestone in Pecca’s journey towards achieving that goal.
Under the plan, Pecca aims to move beyond its core business of providing leather car seat covers, with the involvement in seat assembly and design and eventually, the assembly of completely knocked down (CKD) parts.
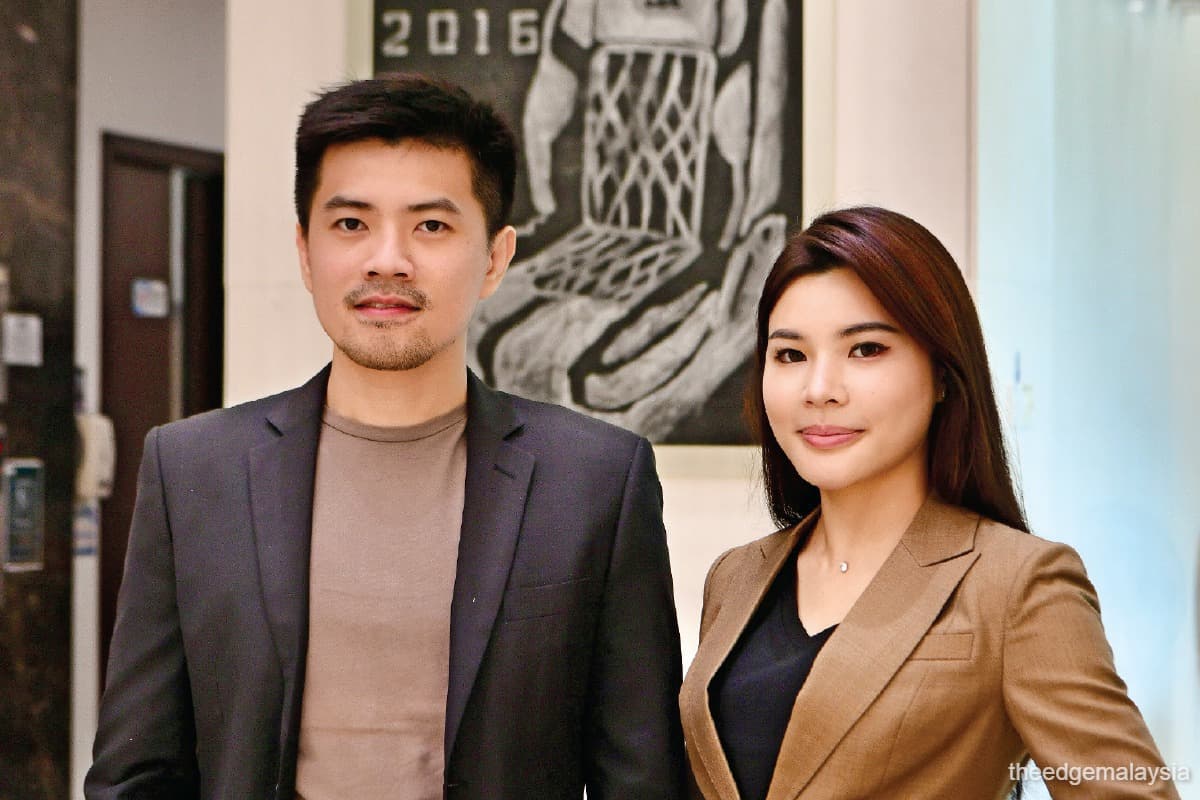
“The Chinese carmakers are setting up their CKD plants in Malaysia, creating new opportunities for us. They welcome us with open arms because they want to leverage Malaysia’s localisation programmes to qualify for more government tax incentives. We are already in talks with them,” Pecca executive director Hugo Teoh Zi Yi, 32, tells The Edge in an interview.
With a strong project pipeline, Hugo assures that Pecca is making good progress towards achieving Tier-1 component supplier status within the next few years.
According to executive director Kelly Teoh Zi Yuan, 30, Tier-1 suppliers deal directly with original equipment manufacturers (OEMs), while Tier-2 suppliers support the Tier-1 players.
“Preparing ourselves to handle components such as instrument panels, seats and doors positions Pecca to become a Tier-1 supplier that can work directly with OEMs in the future,” she says.

Both Hugo and Kelly joined Pecca’s board in October 2020. They are the son and daughter of founder and group managing director Datuk Kelvin Teoh Hwa Cheng, who holds a 3.36% direct stake and an indirect 51.5% interest through MRZ Leather Holdings Sdn Bhd.
MRZ Leather is co-owned by Kelvin and his wife and executive director Datin Christine Sam Yin Thing, who holds 7.55% equity interest in Pecca. Hugo also owns a 0.18% direct stake in the group.
Pecca’s former CEO Foo Ken Nee resigned in June this year after three years at the helm. Despite the leadership change, the group is not rushing to appoint a replacement.
Hugo says the absence of a CEO has had minimal impact on its day-to-day operations.
“We are exploring our options, but we will only move forward if the right person comes along. As the second generation, we are already very hands-on with operations and all the projects,” he adds.
Despite the normalisation of Malaysia’s car sales this year, he highlights that Perusahaan Otomobil Kedua Sdn Bhd’s (Perodua) relatively stable performance has helped to mitigate the overall impact on Pecca. Perodua contributes to half of Pecca’s OEM sales. Its other key OEM customers are Proton Holdings Bhd, Toyota, Nissan and Mitsubishi.
“The normalisation in TIV (total industry volume) is a healthy kind of cycle after the surge in demand last year. Furthermore, Perodua hasn’t launched any new models this year, but new releases, including an EV (electric vehicle) model, are expected next year. So we foresee an increase in TIV in 2026,” he notes.
For the first nine months of 2025, Malaysia’s total industry sales fell 3% to 579,336 units from 595,883 units a year earlier, according to the Malaysian Automotive Association (MAA). Perodua’s sales slipped 2% to 255,094 units in the same period. MAA has forecast total sales of 780,000 units for 2025.
Despite softer revenue, Pecca posted a record net profit for the financial year ended June 2025 (FY2025), up 3.8% to RM57.1 million from RM55 million in FY2024. The improved performance was driven by better production cost efficiency and strict cost controls on selling, distribution and administrative expenses.
Revenue declined 7.4% to RM224.5 million from RM242.42 million due to normalised order flows, but net profit margin rose to 25.4%, from 22.7% in FY2024.
Looking ahead to FY2026, Kelly remains optimistic about Pecca’s prospects, citing higher-margin contributions from the automotive and locomotive segments.
For FY2025, Pecca declared a five sen per share dividend, down from 6.5 sen in the previous year. This represents a lower payout ratio of 63.8%, compared with 88% previously, but still exceeds its minimum 40% payout policy, offering a dividend yield of about 3.7%.
As at end-June 2025, Pecca maintained a strong net cash position of close to RM100 million, or 13.8 sen per share, supported by RM104.91 million in cash and cash equivalents against RM5.38 million in borrowings.
Allocation of RM40 million-RM50 million for new plant
To support its new seat assembly business, Hugo says a new manufacturing facility will be set up on its recently acquired land in Bandar Serendah, Rawang, Selangor. The group has allocated RM40 million to RM50 million in capital expenditure (capex) for the project, with the first phase of operations expected to commence by the second quarter of 2026.
While the OEM segment was Pecca’s largest revenue contributor in FY2025, accounting for 83.1% of total sales, the group is looking to further expand its aviation business, targeting double-digit revenue growth for the segment.
In 2023, Pecca obtained certification from the European Union Aviation Safety Agency, allowing it to provide refurbishment services and supply upholstery seat covers for European-registered aircraft, in addition to Malaysia-registered aircraft. Notably, Pecca is one of only three companies in Southeast Asia to hold this licence.
“Last year, we began promoting ourselves more actively by participating in international air shows to raise our global profile. This year, we have been approached by several international carriers such as Singapore Airlines, Myanmar National Airlines and Maldivian,” says Hugo.
Pecca’s existing commercial airline clients include Malaysia Airlines, AirAsia and Batik Air.
Beyond seat covers, he says the group is setting its sights on bagging other kind of contracts within the aviation segment, such as seat structure work.
“In the aviation and locomotive sectors, clients appoint us as their main contractors for entertainment systems, lighting and plastics. This is a very good challenge for us,” he adds.
To undertake these jobs, Hugo says Pecca has been actively pursuing mergers and acquisitions, strategic alliances and partnerships with other suppliers.
Recently, Pecca signed a memorandum of understanding with Betamek Bhd (KL:BETA) to jointly develop advanced entertainment systems for both in-flight and in-train use. Under the MoU, Betamek will take the lead on the technical side, focusing on the development of the core digital components, while Pecca will focus on the physical integration and compliance aspects.
Meanwhile, Hugo says the group is targeting to generate more sales from Europe for the replacement equipment manufacturer (REM) segment, whose current biggest exports include Singapore, the Netherlands and the US.
In Indonesia, Pecca is seeking to replicate its Malaysian success through its subsidiary PT Pecca Gemilang Indonesia, which is involved in the upholstery leather wrapping and seat covers business for the automotive industry.
“Although Indonesia’s TIV has declined, we are already in talks with new clients such as Honda, Toyota and BYD there. The Indonesian market may not be very exciting, but we expect to see a healthy increase in sales,” he adds.
Pecca’s shares trade at a 12-month forward price-earnings ratio of 16.3 times. The stock is currently covered by UOB Kay Hian Research, which has a target price of RM1.53, representing an upside potential of 13% from its closing price of RM1.35 last Thursday that valued the group at RM978 million. Since hitting a high of RM1.70 in July, the stock has fallen 21%.
Pecca employs about 800 people, comprising 600 foreign workers and 200 locals.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.