

This article first appeared in The Edge Malaysia Weekly on October 13, 2025 - October 19, 2025
FOLLOWING a weak start to the year, QES Group Bhd (KL:QES) expects its financial performance to improve in the second half ending Dec 31, 2025 (2HFY2025), driven by recovering semiconductor demand and higher loading at its manufacturing facilities.
Co-founder and managing director Chew Ne Weng says the Selangor-based semiconductor test equipment firm’s business was badly affected in 1QFY2025 but showed signs of improvement in 2Q.
“Overall, our 1HFY2025 was down as compared to 1H2024. We are expecting wafer fab-related revenue to grow significantly for both [the] manufacturing and distribution divisions in 2HFY2025, and it will probably rise significantly in FY2026 due to semiconductor recovery by then,” he tells The Edge in an interview.
QES’ wafer fab revenue contributed 10.8% to the group’s total revenue in 1H2025, down from 22.8% a year earlier. The softer performance reflected the broader industry slowdown and reduced order book at the end of FY2024.
Headquartered at Hicom Glenmarie Industrial Park, in Shah Alam, Selangor, QES operates two main divisions — distribution and manufacturing.

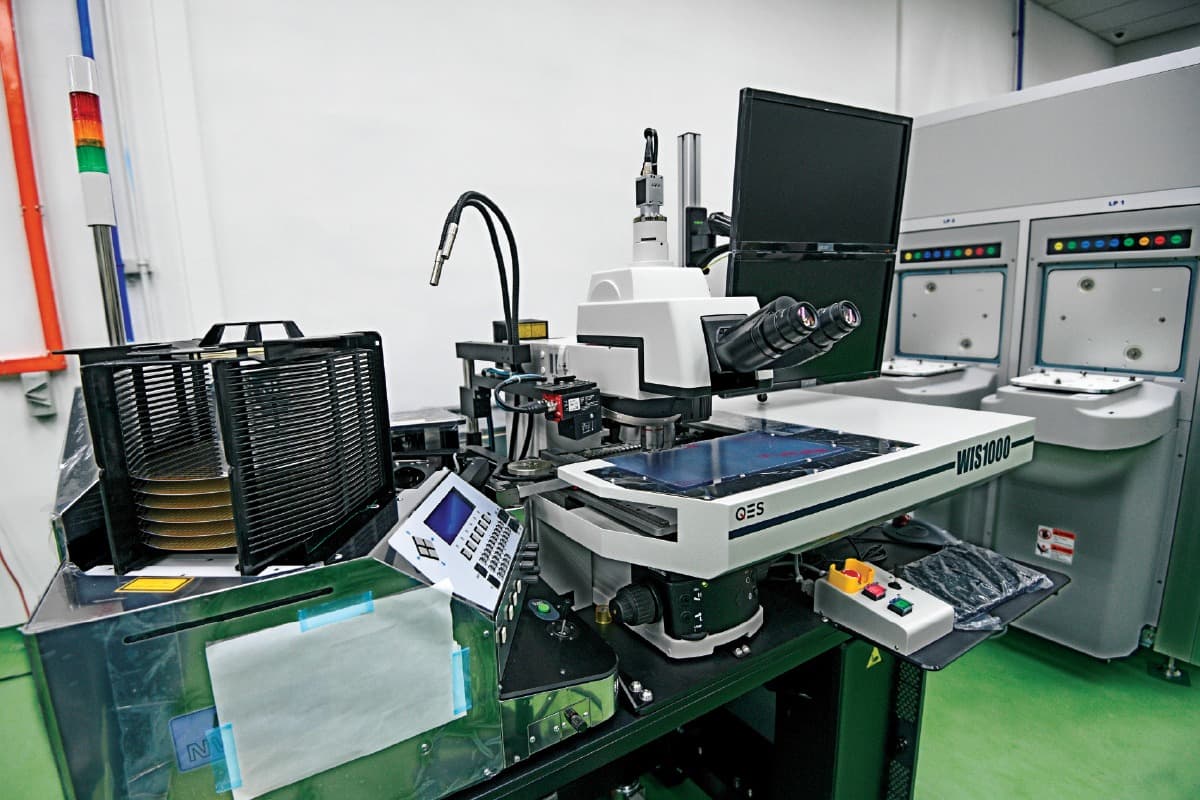
The group distributes analytical instruments, materials and engineering solutions, as well as inspection, test and measurement equipment. It also manufactures semiconductor inspection and measurement equipment and semiconductor automated handling equipment.
QES employs 482 people, with nearly half — 239 employees — based at its Selangor headquarters.
Chew notes that plant loading fell below 60% in 1HFY2025 as the manufacturing order book contracted substantially.
“Our Glenmarie plant started to get more loading by June this year and we are expecting to reach more than 75% by 4QFY2025 as the order book for manufacturing is beginning to come back.
“With our Batu Kawan plant in Penang coming on stream by early 4QFY2025, we will have the total capacity (at both plants) to produce about 150 to 180 machines per annum, depending on [the] complexity of each [piece of] equipment,” he says.
Chew adds that space is no longer a constraint, as it has a combined manufacturing area of more than 100,000 sq ft. The key limitation now lies in engineering and assembly man-hours.
“Wages have been rising fast [in the] past few years and we are hiring fresh university graduates [at salaries] ranging from RM3,500 to RM4,500 [per month] depending on their qualifications and relevancies.
“With QES’ Batu Kawan plant coming online soon, we are hiring engineers — both experienced and fresh — but we are pacing the hiring and carefully monitoring the market volatility.”
Born in Alor Setar, Kedah, Chew started his career as an engineer at Cairnhill Precision Private Ltd, Singapore, in 1987. He co-founded QES in October 1991.
Now 62, Chew is the largest shareholder of QES, with a 30.12% stake, of which 26.13% is held through his private vehicle WA Capital Sdn Bhd. Its second-largest shareholder is QES executive director Liew Soo Keang, who has a 22.87% direct stake.
According to QES’ 2024 annual report, its top 30 shareholders include Sun Life Malaysia Takaful Bhd and Maybank Malaysia Smallcap Fund. It is estimated that institutional investors collectively own a 9% stake in the company.
From FY2020 to FY2022, QES’ revenue nearly doubled from RM155.2 million to RM264.4 million, driven by robust demand amid the semiconductor up cycle and global chip shortage during the Covid-19 pandemic. Net profit expanded more than threefold from RM8.7 million to RM26.4 million over the same period, lifting the net margin from 5.6% to 10%.

However, FY2023 and FY2024 saw a moderation as the global semiconductor market cooled, with revenue easing slightly in FY2023 before rebounding to RM269.6 million in FY2024 — its highest to date.
Net profit, however, declined to RM18.5 million and RM17.3 million for FY2023 and FY2024 respectively, translating into thinner margins of 7.7% and 6.4%. Its bottom line was partly dampened by foreign exchange losses as a result of the weakening US dollar. For 1HFY2025, QES posted a revenue of RM123.1 million and net profit of RM5.3 million, with a net margin of 4.3%.
According to Chew, QES’ automated optical inspection (AOI) equipment business has started to gain traction, after a slow start.
“Our AOI series has been rather spotty with revenue in 1HFY2024 at a paltry RM600,000, but increased to RM1.6 million in 1HFY2025. We have successfully delivered to two wafer fab plants over the last 12 months.”
Chew expects stronger demand in the second half. “We will add another delivery to an advanced packaging plant in Singapore and some to test assembly plants in Malaysia and the Philippines. In short, I am confident we can get more orders for the AOI series when semiconductor production starts to gradually ramp up in FY2026.”
While acknowledging that the tariffs announced by US President Donald Trump in April this year have caused great uncertainties, QES is optimistic on its 2HFY2025 financial performance, with the group’s earnings in FY2026 expected to surpass that in FY2022.
“Based on all the inputs from our customers, we should be heading towards a very good FY2026, which will surpass FY2022’s performance, with a caveat that geopolitical tension remains calm with no major crisis happening.”
QES maintains a net cash position of RM83 million, which Chew describes as healthy. “I am very comfortable with this and we have many plans to look into pursuing more expansionary plans within the sectors we are targeting.
“Currently, we have strength in the semiconductor, metal, automotive and electrical & electronics (E&E) sectors. We are aggressively looking at medical tech potential based on our core competencies in the areas of inspection, measurement and automation.”
Chew adds that the group is also exploring opportunities in advanced packaging within its distribution and manufacturing divisions.
Year to date, shares of QES have declined by 31% to close at 41 sen last Wednesday, giving it a market capitalisation of RM341.66 million. The counter is currently trading at a historical price-earnings ratio (PER) of 24.8 times.
In comparison, ViTrox Corp Bhd (KL:VITROX) is trading at a PER of 85 times, Pentamaster Corp Bhd (KL:PENTA) at 60 times, and MI Technovation Bhd (KL:MI) at 51 times, according to AskEdge data.
Chew reiterates that the company remains focused on fundamentals rather than short-term market movements. “We are not really concerned about the ups and down of QES’ share price. As usual, we are more inclined to building the business and churning out good revenue and profit growth. We are also investing [in our] talent pipeline for the long term and continuously building our Asean infrastructure and manufacturing division.”
In an Oct 8 research report, Tradeview Research initiated coverage on QES with a “buy” call and target price of 48 sen, applying a FY2026 PER of 20 times.
“We expect revenue growth to remain modest in the near term, with a recovery in FY2026/27 as industry conditions improve,” the research house says.
Tradeview favours QES for the organic growth in its distribution segment, supported by a strong networking base across Asia, as well as its strategic diversification into the manufacturing segment to enhance profitability within the semiconductor industry.
Moreover, there is also sustained recurring income from its services and spare parts division, it notes. “Despite ongoing geopolitical uncertainties, QES remains cautiously optimistic, aiming to strengthen its financial performance by expanding its network in neighbouring countries, introducing new product innovations and pursuing strategic collaborations as a beneficiary of trade diversion trends.”
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.